rbc_toc_for_mmm_action

Key takeaways

  • Canada and the U.S. are each other’s largest minerals trading partner, amounting to $146 billion in bilateral trade1.
  • The U.S. is 100% import reliant for 12 of its identified list of 50 critical minerals, and net import reliant (>50%) for 29 of those critical minerals2.
  • China is the primary foreign source for a quarter of the U.S.‘s critical minerals3.
  • Disruptions to the supply of critical minerals could cause material damage to the U.S. economy. One example: a 30% supply restriction of gallium could cause a $600 billion (U.S.) decline in U.S. GDP4.
  • Defense procurement is an underutilized source of financing for key defence critical minerals, particularly graphite, tungsten, scandium, and gallium.

Bedrocks of a Fourth Industrial Revolution

Minerals are the bedrock of any industrial economy. From steel to copper to aluminum, they lay the foundation of economic, civil, and defence infrastructure. And increasingly, a growing cohort of minerals underlie the critical components of the so-called Fourth Industrial Revolution — an era of disruptive technological forces driven by human-machine interaction across research, manufacturing and an ever-expanding data economy.

In this new age, the demand for that cohort of “critical minerals” will be driven by a growing use of semiconductors and data processing machines, increased adoption of battery technologies and new energy sources, and advancements in defence and aerospace technologies. For Canada, the race to develop and process these minerals is about much more than the mining sector; it underscores a new security paradigm to protect and enhance our economic and national interests in an evolving world order. Here’s some of what’s at stake:

Semiconductors

The early days of generative AI are showing how much more computing power we will need. Global semiconductor sales are on pace to reach $1 trillion (U.S.) by 2030, with high-powered artificial intelligence (AI) chips likely accounting for the majority of sales5. To date, silicon has been the material of choice but AI is testing silicon’s thermal limits. Gallium nitrade’s (GaN) superior conductivity results in over 30% improvements in wafer power efficiency6. Palladium, arsenic, copper, and cobalt are also used in chip fabrication (plating, wiring).

Batteries

Whether it’s for EVs on the road, energy efficiency at home or long-duration storage at power generation sites, we’ll need a lot more battery technology in the years ahead. An EV battery requires an average of 205 kilograms of critical minerals (or six times that of an internal combustion engine), comprised of lithium, cobalt, nickel, graphite and manganese7. Based on Bloomberg New Energy Finance’s Economic Transition Scenario, we estimate North American battery minerals demand (transport and utility storage) is likely to increase between four to five-fold by 2040, relative to today8.

Frontier energy

We’re likely to see more oil and gas consumption over the next decade in North America, but we also will see much more growth in newer energy sources, including small modular nuclear reactors, geothermal, wind and solar. The rapid growth in renewable power, which is now about 15% of global power9, is increasing the demand of a number of critical minerals. Silicon, silver and aluminum are needed for solar panels with cobalt, tellurium and rare earth elements for wind. Based on Bloomberg New Energy Finance’s Economic Transition Scenario, we estimate North American renewables (solar and wind) electricity generation to at least triple on the back of increased demand for electricity by 2040, compared to 2024 levels10.

Defence

The push for materially more defence and security spending across the West, including in Canada, will require a lot more heavy equipment and the materials and minerals that go into them. A typical artillery tank requires over 20 different critical minerals across navigation, communications, and combat systems11, while an F-35 jet relies on almost 1,000 pounds of rare earth elements12. Batteries and semiconductors are also increasingly important to military operations, along with more traditional needs to strengthen artillery, naval and aerospace (antimony, beryllium, titanium, among others). And then there’s border security; tungsten is used in automobile x-rays and germanium within thermal imaging and night vision goggles.

A New Great Game

The battle for global tech supremacy between China and the U.S. is manifesting a critical mineral resource war, and a geopolitical great game for the 21st century that may soon rival the race for oilfields that came out of the Second World War or the competition for trade routes that shaped the 19th century.

For the U.S. and its Western allies, this competition is at risk of being lost to China. In areas of EVs, renewable energy, and advanced civil and defence technologies, China is proving to be as innovative as America. Global autos rely on Chinese battery technology. Ford CEO Jim Farley views China a decade ahead on battery technology – and still innovating13. On defence, China can bring on new weapons systems five times as quickly as the U.S.14.

Even more concerning is that the U.S. has little to no presence across the critical minerals value chain. The country is 100% import reliant for almost a quarter of its identified 50 critical minerals, and over 50% import reliant on 29 minerals15. In many instances, that reliance is on China. The country is the primary import source for a quarter of U.S. critical minerals and is the leading global producer of 16 of the U.S.’s list of critical minerals16.

China has dominant positions in either the production and/or refining across the six ‘core’ critical minerals, i.e., lithium, graphite, cobalt, nickel, copper, and rare earth elements (REE). At the most extreme, China has 75% or more global market share of produced and refined graphite, refined rare earth elements, and refined cobalt17. Across the entire six minerals, China has control of, on average, two-thirds of global processing/refining output18.

Critical mineral production is characterized by meaningful concentration risk

Top 3 suppliers as a percent of global supply, 2023
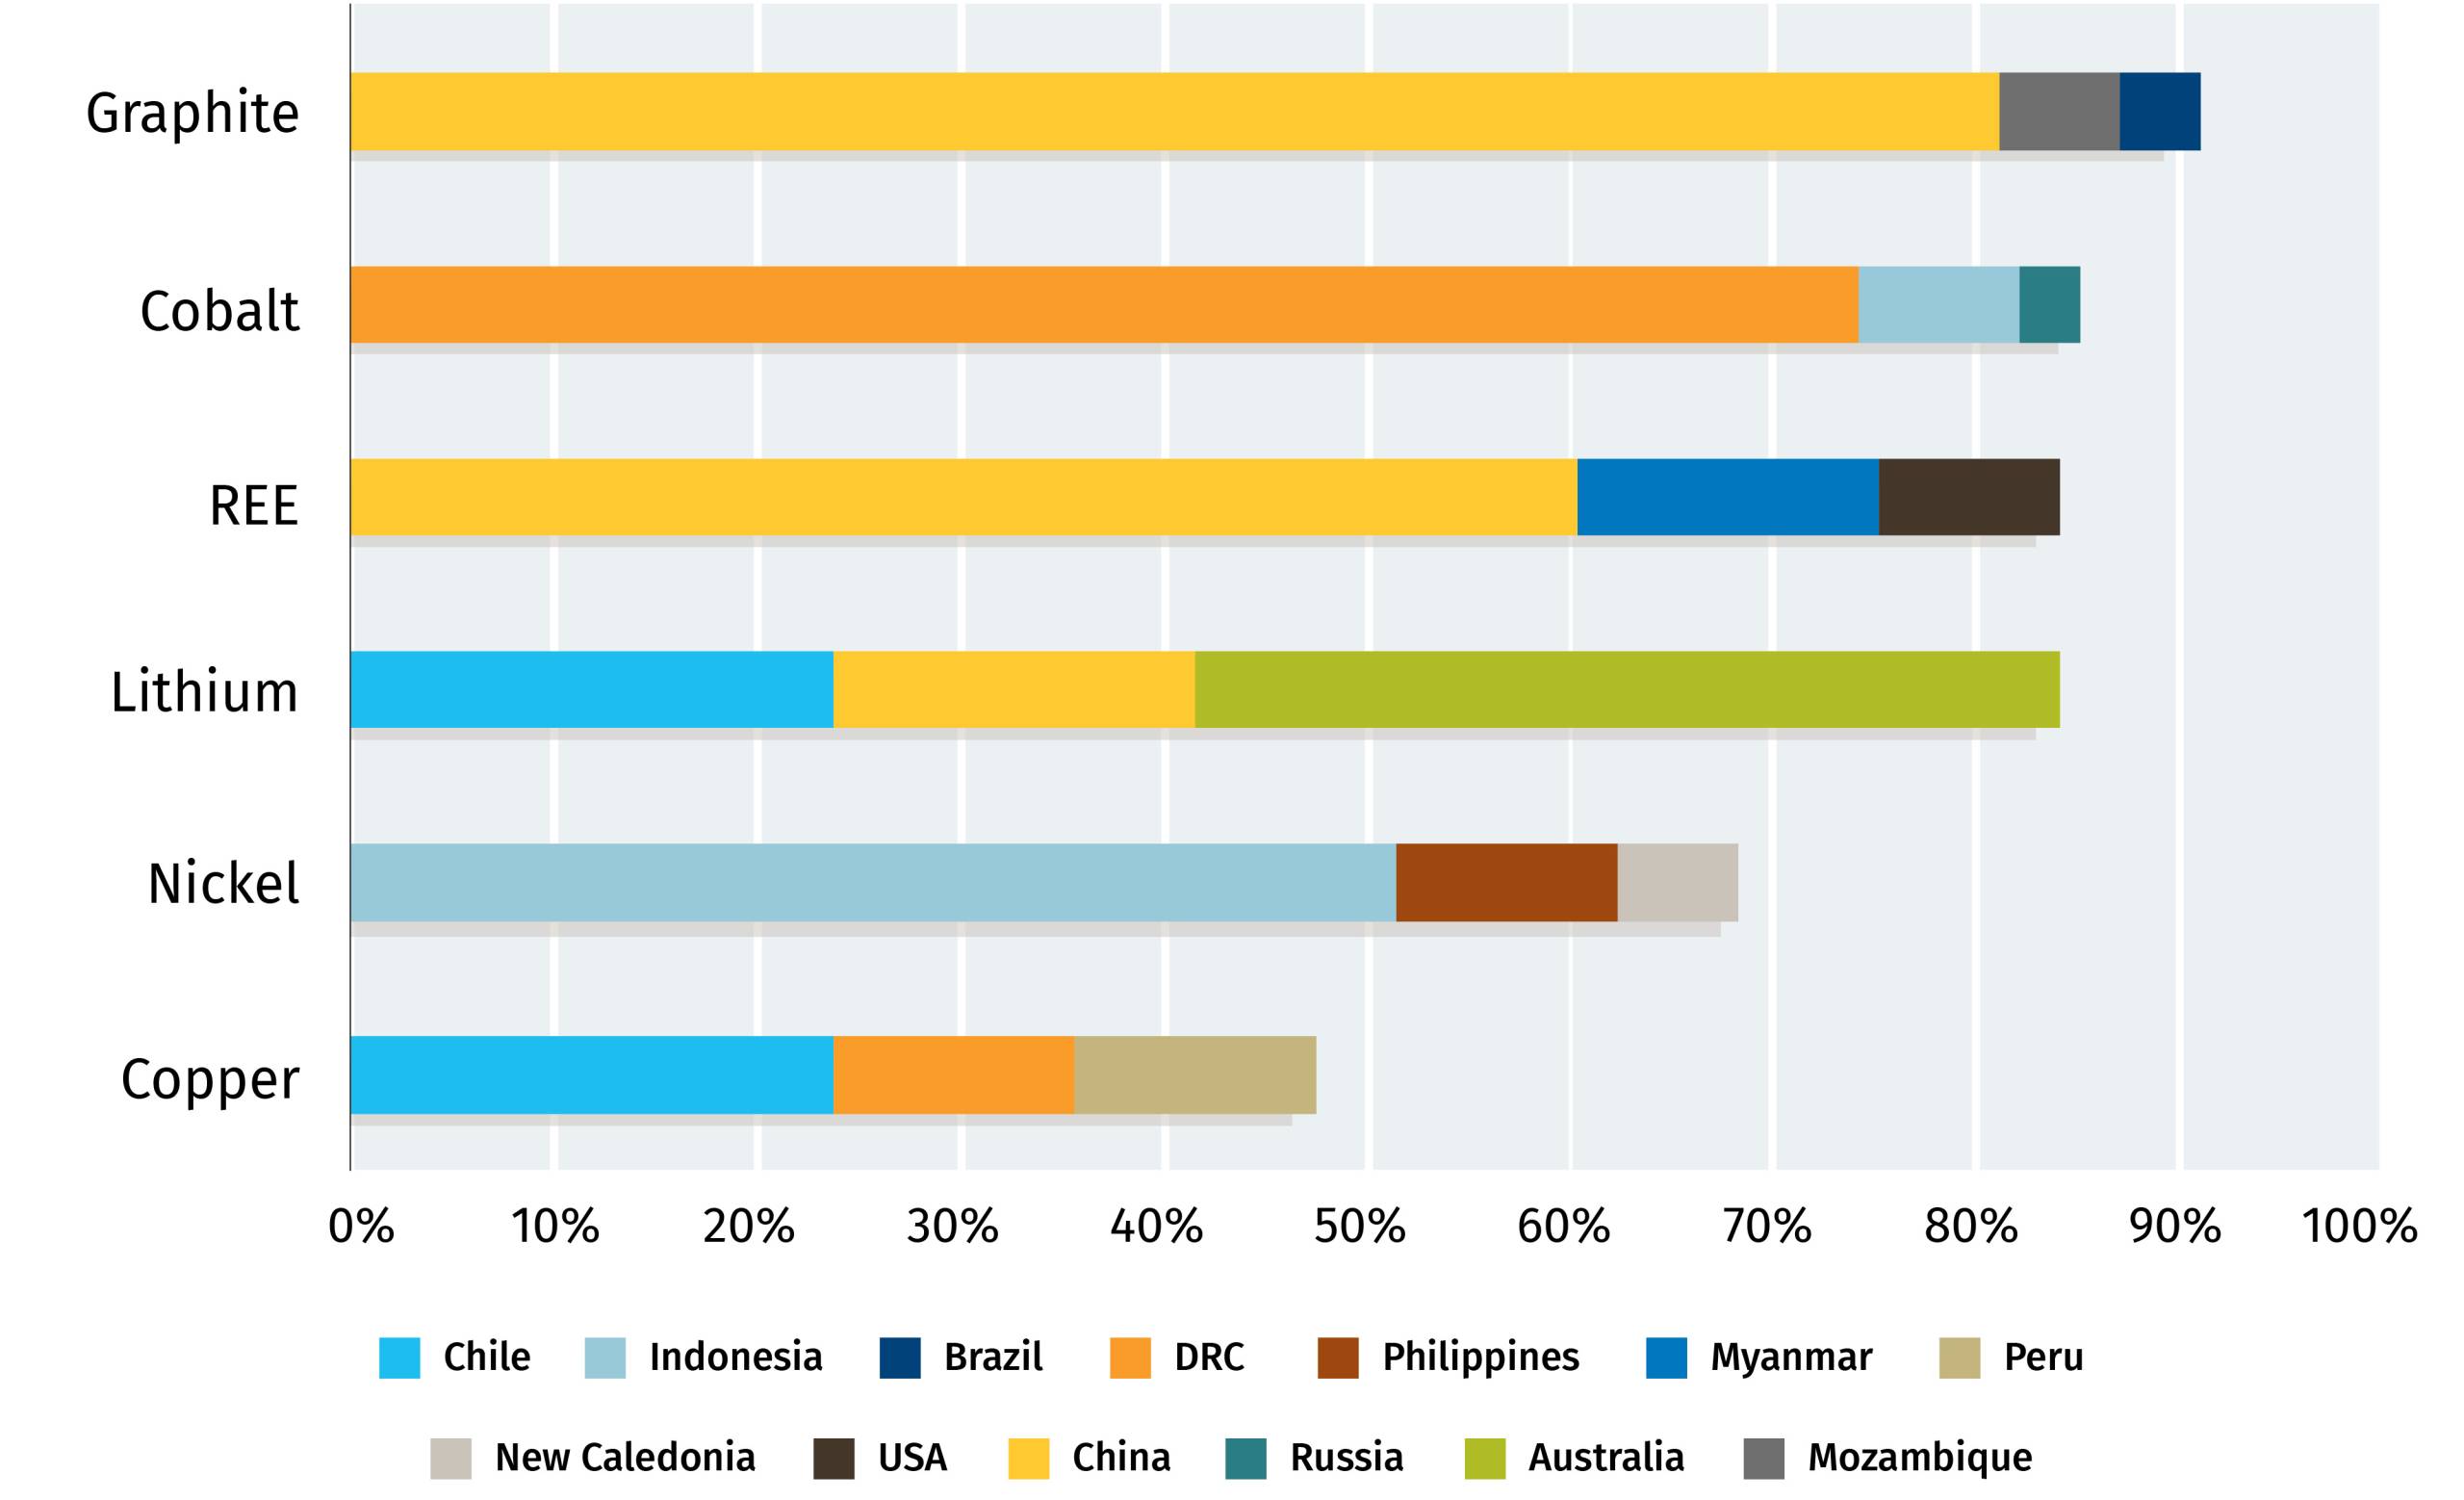
Source: IEA and RBC Thought Leadership

And even more so for critical mineral refining, which is dominated by China

Top 3 suppliers as a percent of global supply, 2023
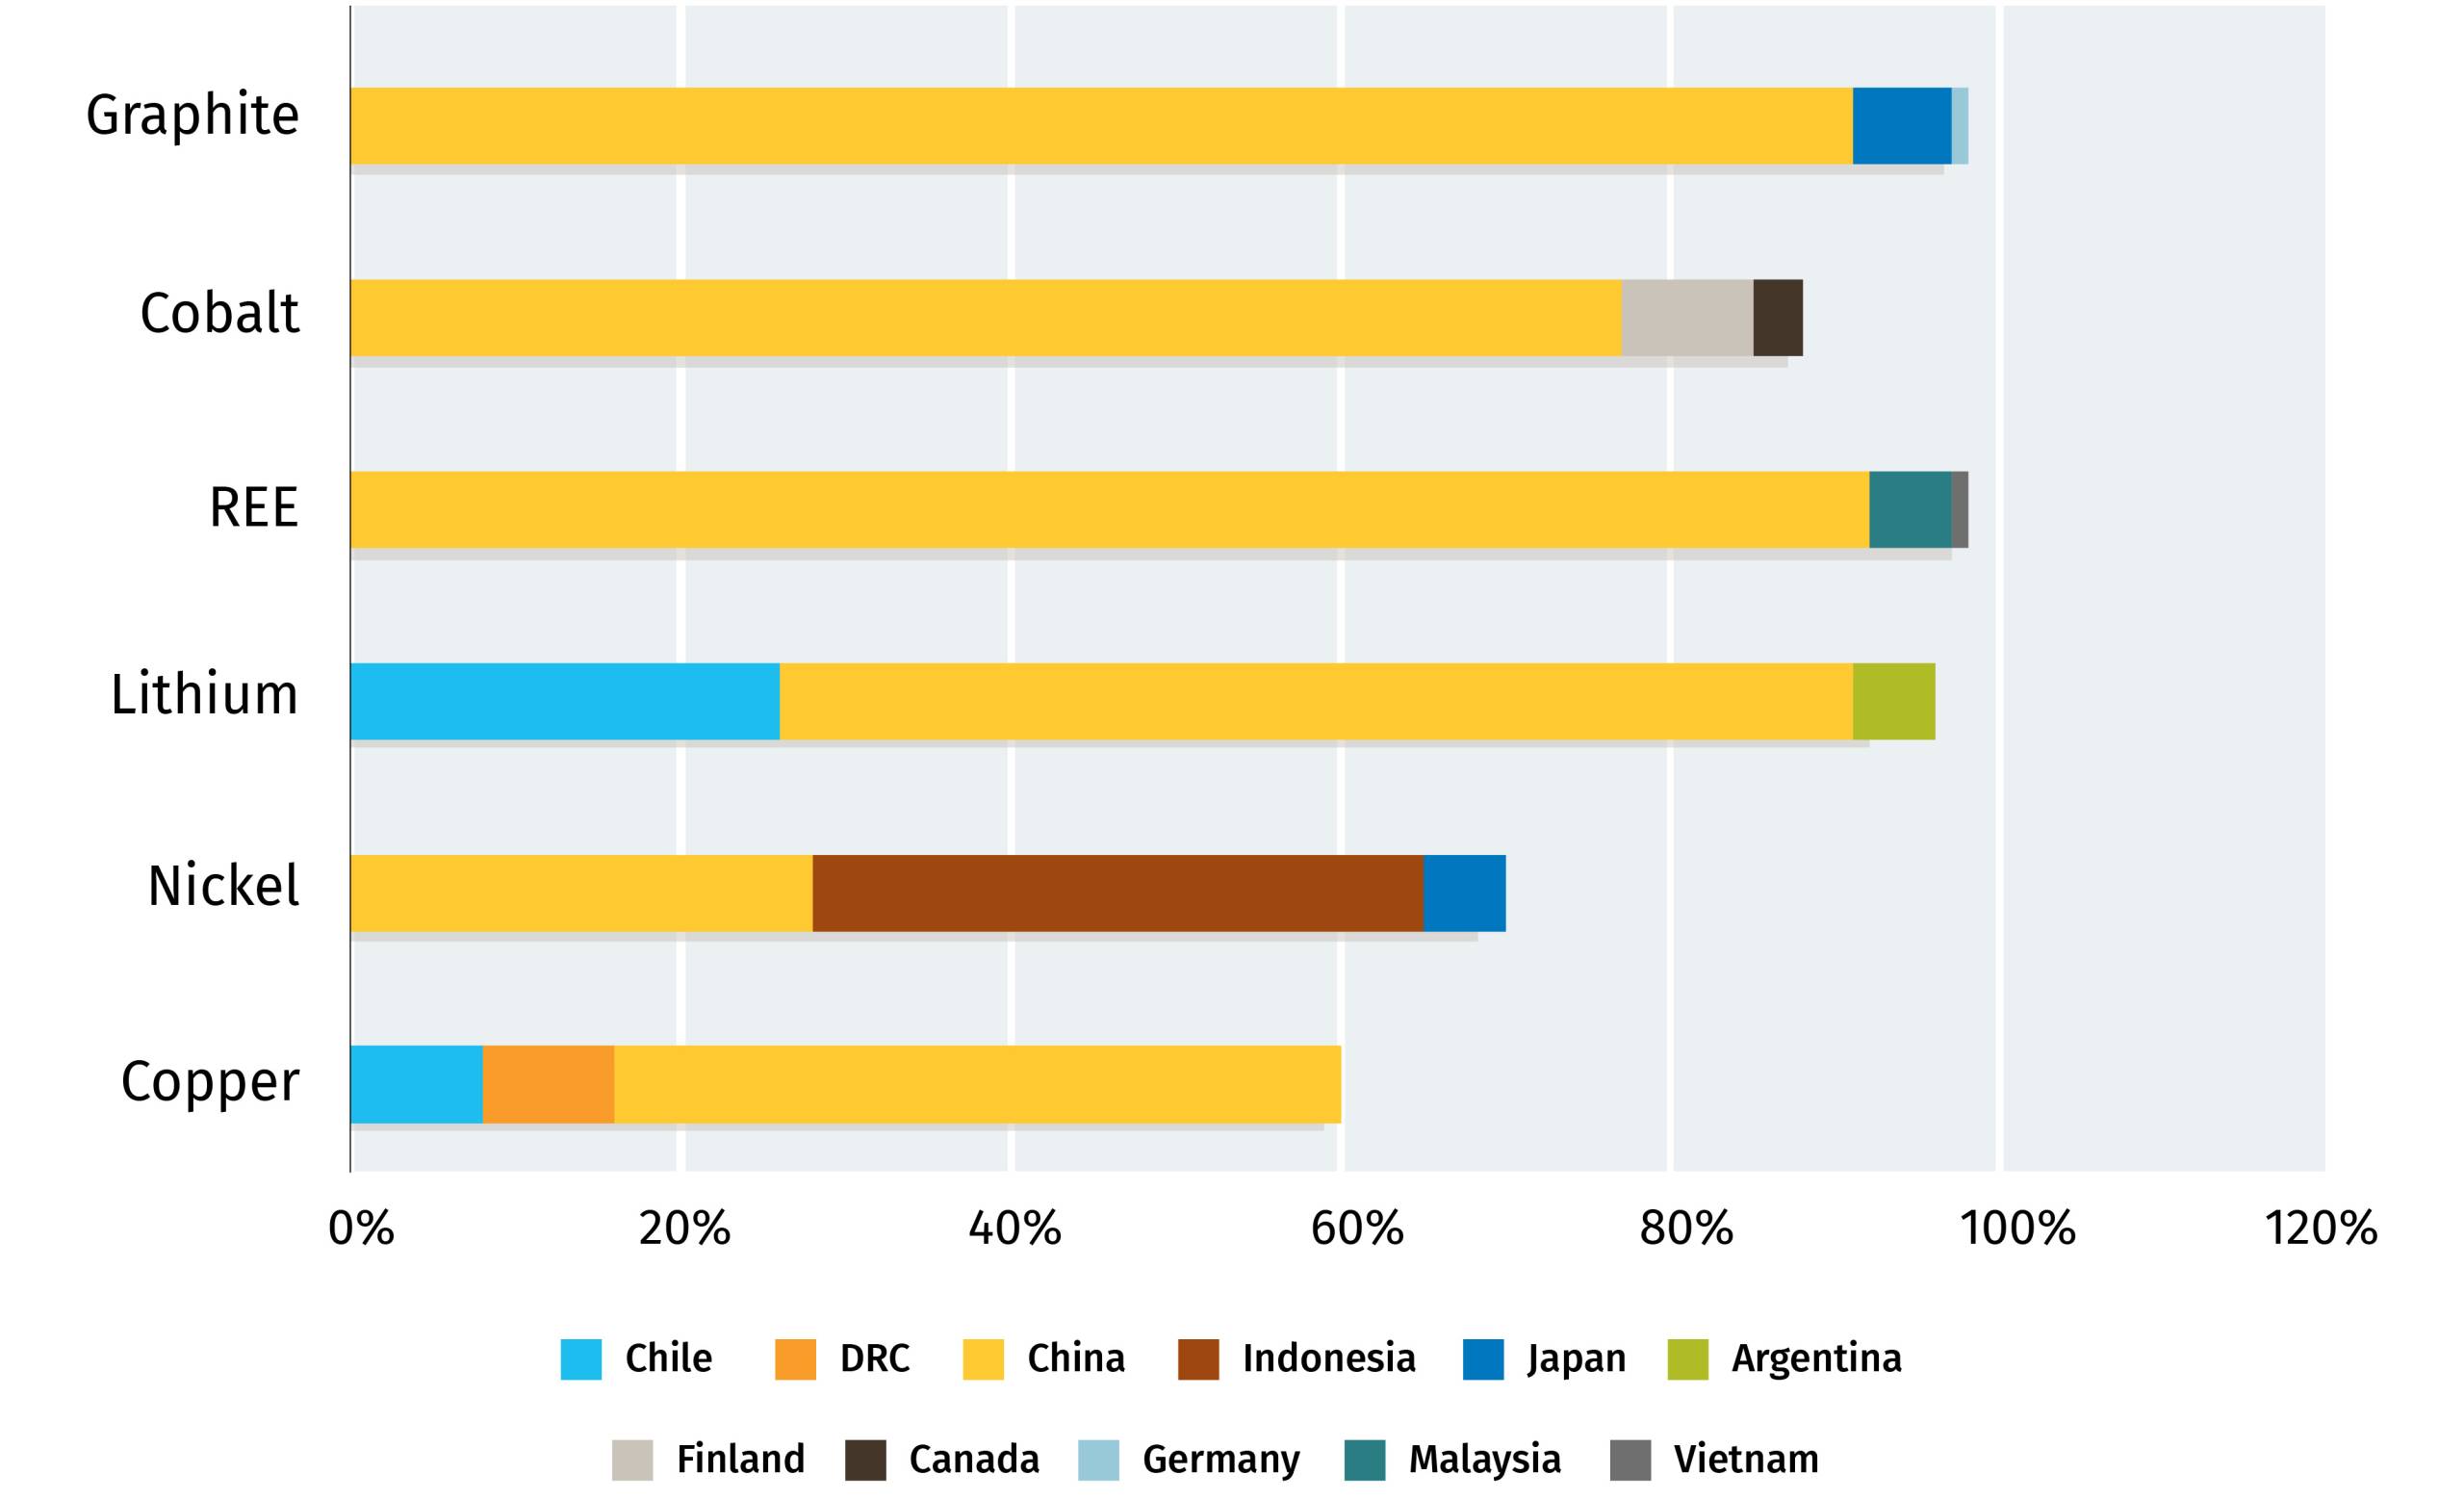
Source: IEA and RBC Thought Leadership

In foreign markets, Chinese state-owned miners have meaningful operations in Peru, the Democratic Republic of Congo and Indonesia (Chinese firms control almost 75% of Indonesia’s nickel capacity)19. The country also has established investment ties and is the largest trading partner for mineral producers/refiners across virtually every country in South America, Africa, Southeast Asia and Oceania (Australia).

Playing catch-up in this rush for critical minerals will be difficult, and far more challenging than the West experienced with oil, for several reasons:

  • 1.
    Exotic minerals. Critical minerals are a varied, diverse set of both traditional and exotic minerals, with their own unique processes to both produce and refine. The process is far more complex than crude refining or natural-gas processing, which situate within a narrower molecular band of hydrogen and carbon compounds.
  • 2.
    End use matters. In critical minerals, the end use predicates the type of production and level of refinement required. For instance, primary gallium is recovered as a byproduct of processing bauxite and even at refinement, high purity gallium is refined up to 99.99999% purity.
  • 3.
    Technology. Decades of experience have allowed China to innovate refining techniques, such as perfecting the solvent extraction process to refine rare earth elements.
  • 4.
    Limited domestic resources. The U.S. has limited domestic resources of critical minerals, with less than 1% of the world’s reserves of cobalt, nickel and graphite and less than 2% of manganese and rare earth elements20.
  • 5.
    No state champions. The Seven Sisters, ancestors of British-American siblings BP, Chevron and ExxonMobil, birthed the oil industry. The seven were provided immense political (and military) assurances to traverse foreign lands in pursuit of securing reserves. In contrast, most major North American miners have smaller global footprints relative to the U.S. oil majors, especially downstream (albeit less so for Barrick Gold, Teck Resources and First Quantum Minerals).

The U.S. will be challenged to catch up to Chinese dominance, at least on its own. As a result, it’s creating new strategic spheres to secure the minerals critical to its global technological leadership, targeting resource deals – and perhaps deeper relationships – in the Ukraine, Greenland and Canada. The U.S. may even re-integrate unrestricted Russian commodities back into global markets, if that furthers its own ambitions for resource security.

Canada must be at the centre of this sphere. The country can de-risk critical mineral supply chains – reducing the reliance on China but also providing additional capacity to markets dominated by a handful of suppliers. Canada is a geologically rich, responsible mining nation with significant mineral potential including nickel, cobalt, zinc, aluminum, potash and more niche minerals such as indium, graphite, germanium and gallium. We are also a trading nation, the only G7 nation with free trade agreements across all other G7 members, complemented by a historically strong security relationship with the U.S.

How China gained the lead

The Trump Administration has made critical minerals a strategic priority. A renewed focus on defence is widely seen as a positive investment. The new administration’s executive order immediately pausing the disbursement of funds through the Inflation Reduction Act, along with recent uncertainty around the Biden Administration’s CHIPS and Scient Act, may be more problematic, as it threatens to freeze some critical investment plans at a time when Beijing is not slowing its pace. Put simply, the U.S. may need to embrace all demand drivers because China is embracing all demand drivers: batteries, renewable power, EVs, defence and AI.

We have identified four key drivers that led to China’s dominance – some of which employ industrial and foreign policy approaches that the West may be forced to take to unbalance this great imbalance:

Policy

Industrial policy targeting steel, aluminum and copper (initial industrialization) was followed by policies to further adoption of EVs and renewables. On the supply side, state assistance was provided to create national champions to compete with global majors. This was complemented with foreign policy objectives, such as One Belt, One Road, which invested $1 trillion (U.S.) in foreign countries — often in resource rich nations21. The Inflation Reduction Act was America’s industrial policy response, and while successful in stimulating capital directed towards research, development and manufacturing, little has been put towards mineral mining and/or refining.

Market

Today, China accounts for 70% of the value of global clean technology22 manufacturing within an ecosystem that is often vertically integrated; minerals are mined, refined to the specificity of end components. Demand pulls supply, which is sourced by state-owned miners operating in lower cost jurisdictions, all while being provided state support. Western miners, in contrast, are beholden to higher standards by public investors, lacking in state subsidies, and are often subject to higher social license costs in foreign resource development, given the lack of political support (state-investor dispute, versus state-state dispute).

Technology

In China, targeted state-support for both supply and demand fostered breakthroughs in technology and riding down the cost curve – especially in renewables and batteries. On the supply side, technological innovation in Chinese production and refining has allowed China to perfect the solvent extraction process to refine REEs.

Mindset

China takes a war-time mindset to allocating capital and other resources to ensure security of supply and demand through an entire value chain approach. The U.S., in contrast, lacks such urgency. It’s even moved away from strategic mineral reserves, by either not replenishing reserves relative to historical levels or, in the case of helium, selling reserves altogether. This is vastly different than the approach taken to crude oil, which maintains a strategic reserve and until 2015 had a continental export ban.

The big five: Canada’s non-fuel critical minerals

U.S. imports of all non-fuel mineral and metals reached $167 billion (U.S.) in 202423. Canada remains the largest source of U.S. imports (US$40 billion, or 24%), and is the #1 provider of steel, aluminum, potash, nickel and zinc to the U.S. (#2 for copper)24. Across the U.S.’s 50 critical minerals, Canada is also the largest source of imports (US$4.5 billion, or 20%)25.

With that said, the U.S. remains reliant on China for many less commercial yet strategically important critical minerals. Even more, China has implemented export controls on a number of these minerals, such as gallium. The economic significance from this supply risk is material; the U.S. Geological Survey estimates a 30% supply reduction in gallium (China is 90% of global supply) alone could cause a $600 billion (U.S.) drop in U.S. GDP26.

In the near to mid-term, Canada has an opportunity to gradually displace Chinese supply, while also furthering a U.S.-Canadian strategy to secure production across a range of technologies and applications critical to both continental security and the Fourth Industrial Revolution. Below, we identify five key critical minerals best situated around this opportunity.

1. Gallium


Gallium has one of the highest thermal conductivities among metals. It is used in the production of highly specialized integrated circuits and semiconductors for AI and advanced computing. Gallium-based semiconductors are also vital to U.S. next-generation missile defence, radar systems and electronic communications.

The U.S. remains 100% import reliant for its supply of gallium27. In 2024, Canada was the #1 provider of gallium metal to the U.S., accounting for over 50% of imports (effectively displacing Chinese supply)28. Current supply is sourced from recycled gallium at Neo Performance Materials’ site in Peterborough, Ontario. Rio Tinto’s Saguenay demonstration project could add another 5-10% of total global primary gallium metal production if it can reach commercial viability29. A proposed expansion at Teck Resource’s Trail, B.C. operations could also increase production of germanium and add gallium and antimony.

2. Graphite


High electric conductivity, temperature resistance, chemical inertness, and lubricity characterize this battery metal increasingly relevant in defence applications. Graphite’s unique properties make it difficult – even impossible – to substitute in many applications, such as where thermal resistance is essential to equipment performance and durability.

Global demand for graphite is forecast to nearly double by 203530. Canada has a unique opportunity to develop a full graphite value chain, a highly valuable proposition given China is 82% and 91% of global graphite production and refining, respectively31. Quebec is furthest along with Northern Graphite’s operating mine in Lac des Iles, northwest of Mt. Tremblant, and Nouveau Monde Graphite’s development projects underway for mining in Matawinie, north of Montreal, and refining in Bécancour, outside Trois-Rivieres. Ontario offers another potential graphite mine, Northern Graphite’s Bissett Creek, near the Ottawa River north of Algonquin Park, which is undergoing permitting.

3. Nickel


Nickel has high ductility (flexible), toughness and strength. The mineral is used in lithium-ion batteries and in the production of stainless steel. Global demand is forecast to grow 70% by 2035, largely on the back of demand for batteries, both within transport and stationary (utility)32.

The Dumont Nickel project (Nion Nickel) in Quebec’s Abitibi region is vertically integrated and under construction. Canada Nickel’s Crawford mine (world’s second largest nickel reserve) north of Timmins, Ontario, is undergoing permitting. Canadian nickel provides much needed diversification of supply, with Indonesia and the Philippines together alone accounting for two-thirds of global production33. Canadian nickel could exceed 100% of U.S. import needs if all projects come online34.

4. Tungsten


With the highest tensile strength (the maximum stress a material can bear without breaking) and melting point of all naturally occurring metals, tungsten-based alloys are key inputs for defence aircraft, naval vessels, and armour-piercing ammunition. Tungsten is also used within automobile x-ray machines, used in enhancing U.S. border security.

China produces 83% of the world’s tungsten and accounts for 52% of global reserves35. Canada is a past producer, with substantial reserves that include some of the world’s largest tungsten deposits. Northcliff Resources’ Sisson project, northwest of Fredericton, and Fireweed Metals’ Mactung mine, in eastern Yukon, are notable Canadian tungsten projects. In December 2024, the Canadian government and U.S. Department of Defense announced a joint investment of $35 million USD in the Mactung project, the world’s largest high-grade tungsten deposit36.

5. Germanium


The mineral has semiconducting characteristics comparable to those of silicon, but with superior optical and thermal properties. Its use is critical in night vision, space exploration, fiber optic cables, and semiconductors. The growing need for datacenters (fibre) has spurred demand in recent years.

Canada supplied 20% of U.S. germanium (oxide) imports in 202337. Canada’s Teck Resources holds an integrated germanium supply chain with zinc ores mined in Alaska and refined in Trail, B.C. The Trail facility has a proposed expansion to increase germanium production largely in response to China’s germanium export ban late last year.

Ensuring Canadian Competitiveness

Canada’s natural resource wealth has attracted natural resource investors and operators for over a century, backed by quality infrastructure, rule of law, robust environmental and labour standards, and deep trading relationships. Canada can build on those strengths, taking the following steps:

  • Leverage government capital. Critical mineral projects face capital shortages. Governments can help bridge this gap with either direct equity positions or by providing long-term offtake agreements. Defence procurement is a focal point, where Canadian, U.S. and allied nations defence departments can source future supply of critical minerals and stockpile reserve through “virtual inventories” or long-term purchase commitments. If Canada meets a commitment to spend 2% of GDP on defence, this could unlock as much as $17 billion of new capital, annually, for mine development.
  • Limit price distortions from China. The mining industry now requires a “China premium” to counteract market distortions – primarily to offset the risk of China oversupplying markets to suppress global pricing. A minimum price floor, supported by government purchase agreements and other intervenions, adds price transparency and establishes revenue certainty to buffer price fluctuations. Alternatively, restrictions on Chinese products could support domestic pricing. This includes restricting Chinese supply outright, or enacting price adjustments such as anti-dumping, countervailing duties, or border adjustments (environmental and human rights standards).
  • Expand tax credits. Canada’s Critical Mineral Investment Tax Credit (ITC) excludes key defence critical minerals such as tungsten, indium, and beryllium. Eligibility could be further expanded beyond the current list of 15 minerals. Other options: allow for the stacking of tax credits, introduce Production Tax Credits (PTC) to support operating expenses (buffering against Chinese dumping) and enhance various government programs to more explicitly support critical minerals, including the Strategic Innovation Fund and Canada Growth Fund.
  • Secure market access. Tariff threats and Buy America programs hinder capital flows into non-U.S. jurisdictions. Minimizing tariff barriers abroad and investing in domestic refining and processing capacity ultimately secures demand for our products. On the supply side, securing our own supply chain is also critically important. Gallium is a Canadian success story, but relies on imported electronics from Taiwan (via the U.S.).
  • Invest in human capital. The Toronto Stock Exchange and TSX Venture Exchange are home to more miners than any other major developed world index, and with them comes a deep bench of mining talent. This talent is at risk, however, as engineers and a tech-minded generation increasingly looks to software and AI for careers. One startling fact: China has 39 university degree programs to train engineers in critical minerals; Canada has none.
  • Reduce approval times. Canada needs to consolidate processes, where possible. Critical minerals are as strategic as transportation, and related projects can be declared to be in the national interest to accelerate their development. The same sort of pragmatism can be applied at the provincial level, where collaboration across departments, with local communities and with Ottawa can be improved. Lastly, and perhaps most importantly, we will need to find new ways to accelerate project approval processes while not undermining the duty to consult Indigenous communities. More Indigenous equity in these projects, including through the national and various provincial loan guarantee programs, can unlock greater Indigenous wealth and capital for re-investment in societal infrastructure and future resource projects.
  • Enabling infrastructure. Given the remote nature of many critical mineral deposits, the lack of existing infrastructure is problematic including rail, road, ports, power transmission, and cell towers. Increased collaboration by Federal and provincial governments to provide anticipatory, enabling infrastructure can support project economics and limit mine development times.

For more, go to rbc.com/thetradehub.
Download the Report

Download

Contributors:

Shaz Merwat, Energy Policy Lead, RBC Climate Action Institute

John Stackhouse, Senior Vice-President, Office of the CEO, RBC

Vivan Sorab, Senior Manager, Clean Technology, RBC Climate Action Institute

Caprice Biasoni, Graphic Design Specialist

Shiplu Talukder, Digital Publishing Specialist

  1. Natural Resources Canada
  2. Center for Strategic and International Studies, Critical Minerals and the Future of the U.S. Economy, February 2025; Natural Resources Canada
  3. Natural Resources Canada
  4. U.S. Geological Survey
  5. Deloitte, 2025 Global Semiconductor Industry Outlook
  6. Arrow Electronics, Silicon vs. gallium nitride (GaN) semiconductors: Comparing properties & applications, March 21, 2024
  7. IEA, Minerals used in electric cars compared to conventional cars, May 5, 2021
  8. Bloomberg New Energy Finance, RBC Thought Leadership
  9. IEA, Renewables 2024, October 2024
  10. Bloomberg New Energy Finance, RBC Thought Leadership
  11. Natural Resources Canada
  12. Science History Institute, Manufacturers Case Study, Using the Rare Earth Elements
  13. Wall Street Journal, What Scared Ford’s CEO in China, September 14, 2024
  14. Center for Strategic and International Studies, Critical Minerals and the Future of the U.S. Economy, February 2025
  15. Ibid
  16. Natural Resources Canada
  17. IEA, Global Critical Minerals Outlook 2024, May 2024
  18. Ibid
  19. Reuters, Chinese firms control around 75% of Indonesian nickel capacity, report finds, February 5, 2025
  20. Center for Strategic and International Studies, Critical Minerals and the Future of the U.S. Economy, February 2025
  21. AidData, Power Playbook: Beijing’s Bid to Secure Overseas Transition Minerals, January 28, 2025
  22. IEA, Energy Technology Perspectives 2024, October 30, 2024
  23. U.S. International Trade Commission, data accessed via DataWeb
  24. Ibid
  25. U.S. Geological Survey Mineral Commodities Survey; U.S. International Trade Commission, data accessed via DataWeb; USA Trade Online, U.S. Census Bureau
  26. U.S. Geological Survey
  27. Ibid
  28. U.S. International Trade Commission, data accessed via DataWeb; USA Trade Online, U.S. Census Bureau
  29. Company website
  30. Natural Resource Canada
  31. IEA, Global Critical Minerals Outlook 2024, May 2024
  32. Natural Resources Canada
  33. IEA, Global Critical Minerals Outlook 2024, May 2024
  34. Company website
  35. IEA, Global Critical Minerals Outlook 2024, May 2024
  36. Natural Resources Canada
  37. U.S. International Trade Commission, data accessed via DataWeb; USA Trade Online, U.S. Census Bureau

rbc_toc_for_mmm_action

Climate action is often associated with groundbreaking technologies, new data, and fresh approaches. But what if the next big climate innovation isn’t something new—but something we already have, simply seen through a different lens?

As Climate Action 2025 highlights, this year has brought turbulence for climate priorities, as trade and geopolitical tensions, particularly with the U.S., dominate attention. With climate action slipping down the priority list, industries must pivot—embedding sustainability into core business strategies, not as an add-on, but as a driver of efficiency, resilience, and growth.

With shifting priorities competing for resources and investments, innovation found right under your nose may hold the key to unlocking new market ready opportunities. Semex, a leading genetics company based in Guelph, Ontario shows us how.

Methane emissions from cattle—driven by enteric fermentation, a natural digestion process— is the largest source of GHG emissions in agriculture and among the toughest to abate. What if the key to reducing them was ready and waiting to be unlocked?

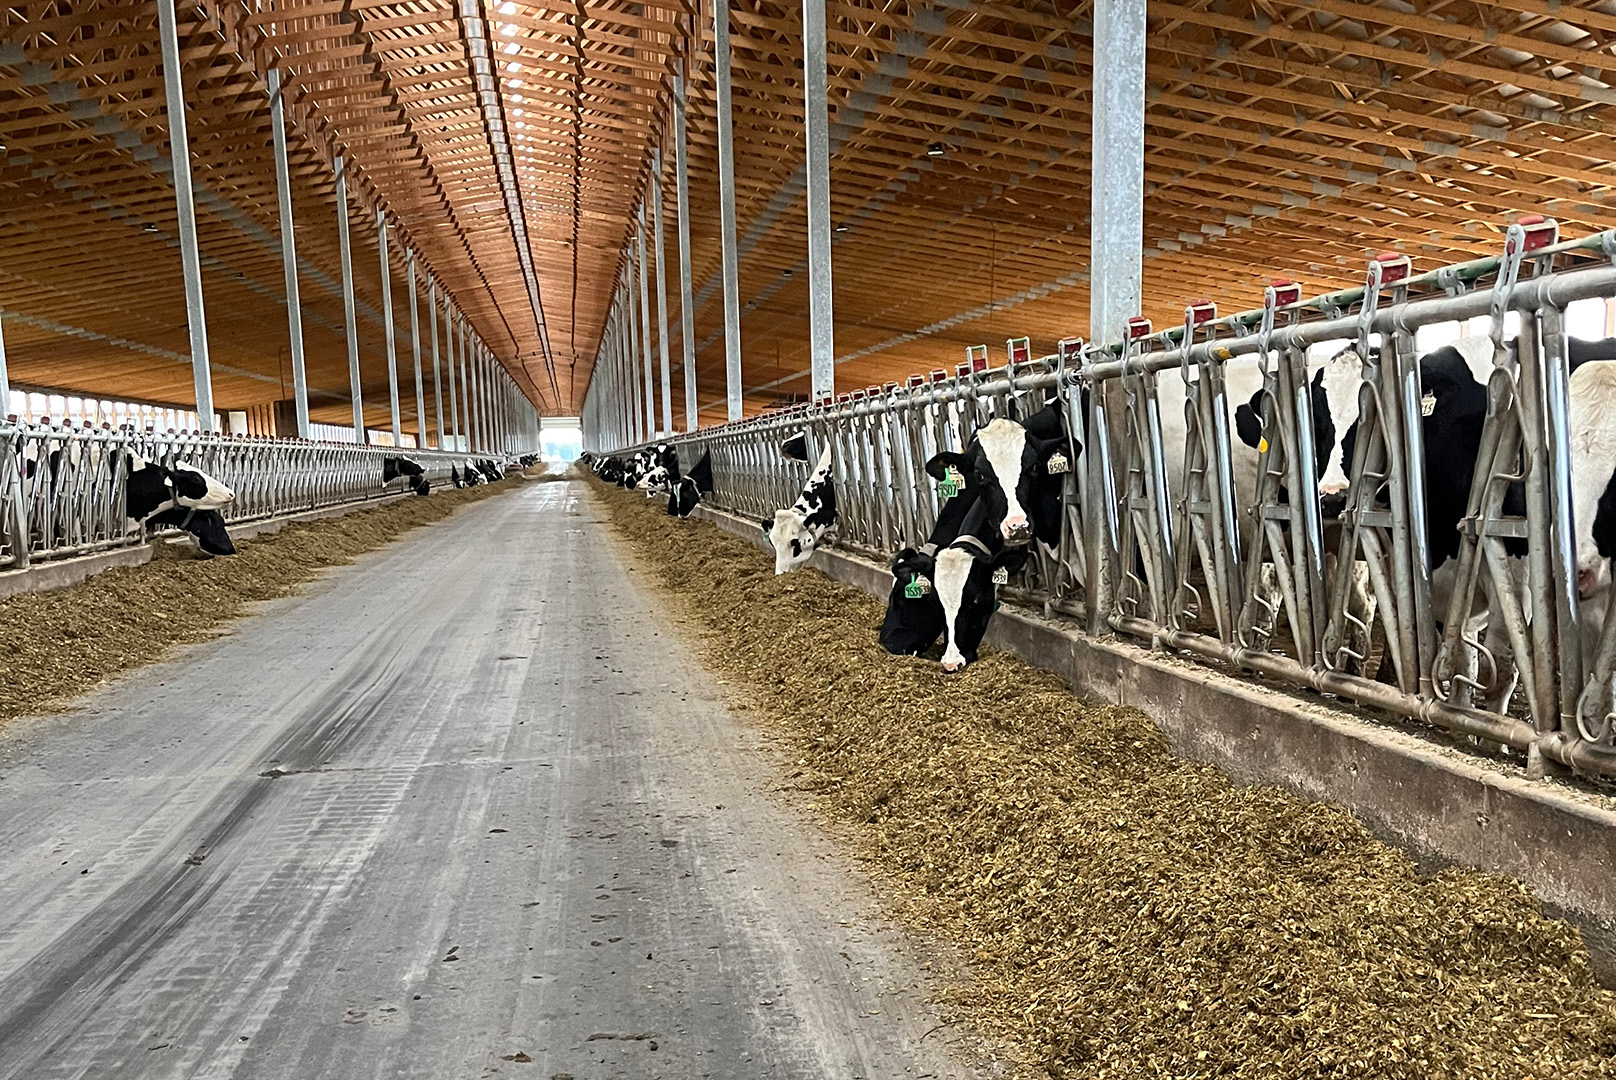
Semex offers animal semen, embryos, breeding services, and software to farmers in more than 80 countries. The company recently identified a genetic trait that farmers can now select to reduce their herds’ methane by 2 to 3% each generation, with permanent reductions of methane emissions estimated to be 20 to 30% by 2050.

The key to bringing this discovery to market wasn’t a brand-new technology—it was a new way of looking at existing industry data. Semex leveraged a national milk database managed by Lactanet, who collects data using mid-infrared (MIR) spectroscopy for milk quality and herd performance. By analyzing this data through a climate lens, researchers uncovered a striking insight: MIR datasets could also be used to predict and influence methane emissions. This existing dataset was the resource needed to unlock insights on methane production by cattle as novel and direct measurement approaches in the barn for methane are still too costly to scale.

Thanks to existing big data and collaboration, Semex was able to bring the methane efficiency trait to market.

This case study highlights a vital lesson: climate innovation doesn’t always require new tools—sometimes, it’s about looking at what we already have through a new lens. Businesses that embrace this mindset can unlock new efficiencies, market advantages, and climate solutions without reinventing the wheel.

For more on policies, people and companies driving climate action in the agriculture sector, visit the sector analysis of our flagship report here.

rbc_toc_for_mmm_action

As the world races to secure the critical minerals essential to a modern economy, Canada has a crucial decision to make: what role can it play in de-risking a critical mineral supply chain that is overwhelmingly dominated by China?

At PDAC 2025, this question is top of mind for industry leaders, policymakers, and global investors. Building on our Getting Critical on Critical Minerals briefing, we’re diving deeper into five minerals increasingly vital to the economy of the future.

Each of these minerals are vital inputs across five key focus areas: artificial intelligence, border security, healthcare, energy and defense. But supply chains are vulnerable, international competition is fierce, and Canada must navigate complex policy, investment, and processing challenges to establish itself as a global leader.

Explore the briefings:

1. Gallium: the most critical of critical minerals. Key Focus: Artificial Intelligence

Critical Minerals – Gallium

2. Germanium: vitally important to border security: Key Focus: Border Security

Critical Minerals – Germanium

3. Graphite: the Swiss Army Knife of critical minerals. Key Focus: Defense

Critical Minerals – Graphite

4. Helium: tomorrow’s critical mineral. Key Focus: Healthcare

Critical Minerals – Helium

5. Rare Earth Elements: a needed alternative to China. Key Focus: Energy

Critical Minerals – Rare Earths

It’s time to get critical on critical minerals.

rbc_toc_for_mmm_action

Every year, Toronto plays host to the world’s biggest mining conference, as the Prospectors and Developers Association of Canada brings together more than 27,000 global mining executives, investors and policy makers. And this year’s conference, running from March 2-5, is more critical than ever. Critical minerals will be centre stage, given their importance to the growing geopolitical race between the United States and China. They may not be the mainstay of mining but minerals like gallium and lithium are essential inputs in advanced technologies that span energy, defense, manufacturing and increasingly, artificial intelligence. Nations with secure access to these critical minerals will secure global economic competitiveness and national security. Here are three big questions we’ll be tracking at PDAC ‘25:

1. What’s with all the critical mineral hype?

From advanced semiconductors used in AI to the manufacturing of electric vehicles and batteries to technological advancements in defense and aerospace, critical minerals underlie the critical components of the Fourth Industrial Revolution – an era of disruptive technological forces driven by increased human-machine interaction. Today, China dominates the entire critical mineral value chain, from mining to refining/processing to end-use demand. The International Energy Agency has identified six core critical minerals (copper, lithium ,nickel, cobalt, graphite and rare earth elements) — and on average, China accounts for two-thirds of global refining capacity for the group. In contrast, the U.S. has limited domestic reserves of critical minerals and is entirely import-reliant on supply – often times from China itself. This battle for global tech supremacy between China and the U.S. is manifesting a critical mineral resource war, a new great game for the 21st century rivaling the geopolitical significance of oil post Second World War.

2. What role can Canada play in securing critical mineral supply chains?

Canada and the U.S. have an established minerals and metals trading relationship, as each other’s largest trading partner. In 2024, Canadian non-fuel mineral imports amounted to US$40 billion, or 24% of total U.S. imports. The country is also the largest source of U.S. critical mineral imports by dollar value, but largely skewed by ‘commercial’ critical minerals imports such as aluminum, nickel and zinc. Increasingly, there is a growing cohort of less commercial yet strategically important niche critical minerals with vital importance in defense applications, border security and advanced chip making. The supply of these minerals, such as gallium, germanium, antimony and tungsten, are dominated by China and are subject to Chinese export controls. It is across this subset of minerals particularly where we believe Canada can play a vital role in in de-risking U.S. and G7 critical mineral supply chains.

3. What can we expect to hear at the conference?

This year’s PDAC conference will have a greater-than-usual policy bent, given the increased tensions around U.S. critical mineral supply – already witnessed in Ukraine peace talks but also seen in President Trump’s commentary around Greenland and Canada. Continued rhetoric from policy makers and mining executives on Canada’s potential may expand the belief that Canada has allies and economic partners. We anticipate hearing more on how Canada can enhance its competitiveness in attracting critical mineral capital. This could include a greater role for governments in providing offtake agreements, enhanced fiscal incentives such as expanded investment tax credits, securing market access and streamlining permitting. RBC Thought Leadership will publish a more detailed report on critical minerals later this coming week, along with commentary throughout PDAC. You can follow our research and insights on RBC’s Trade Hub.

rbc_toc_for_mmm_action

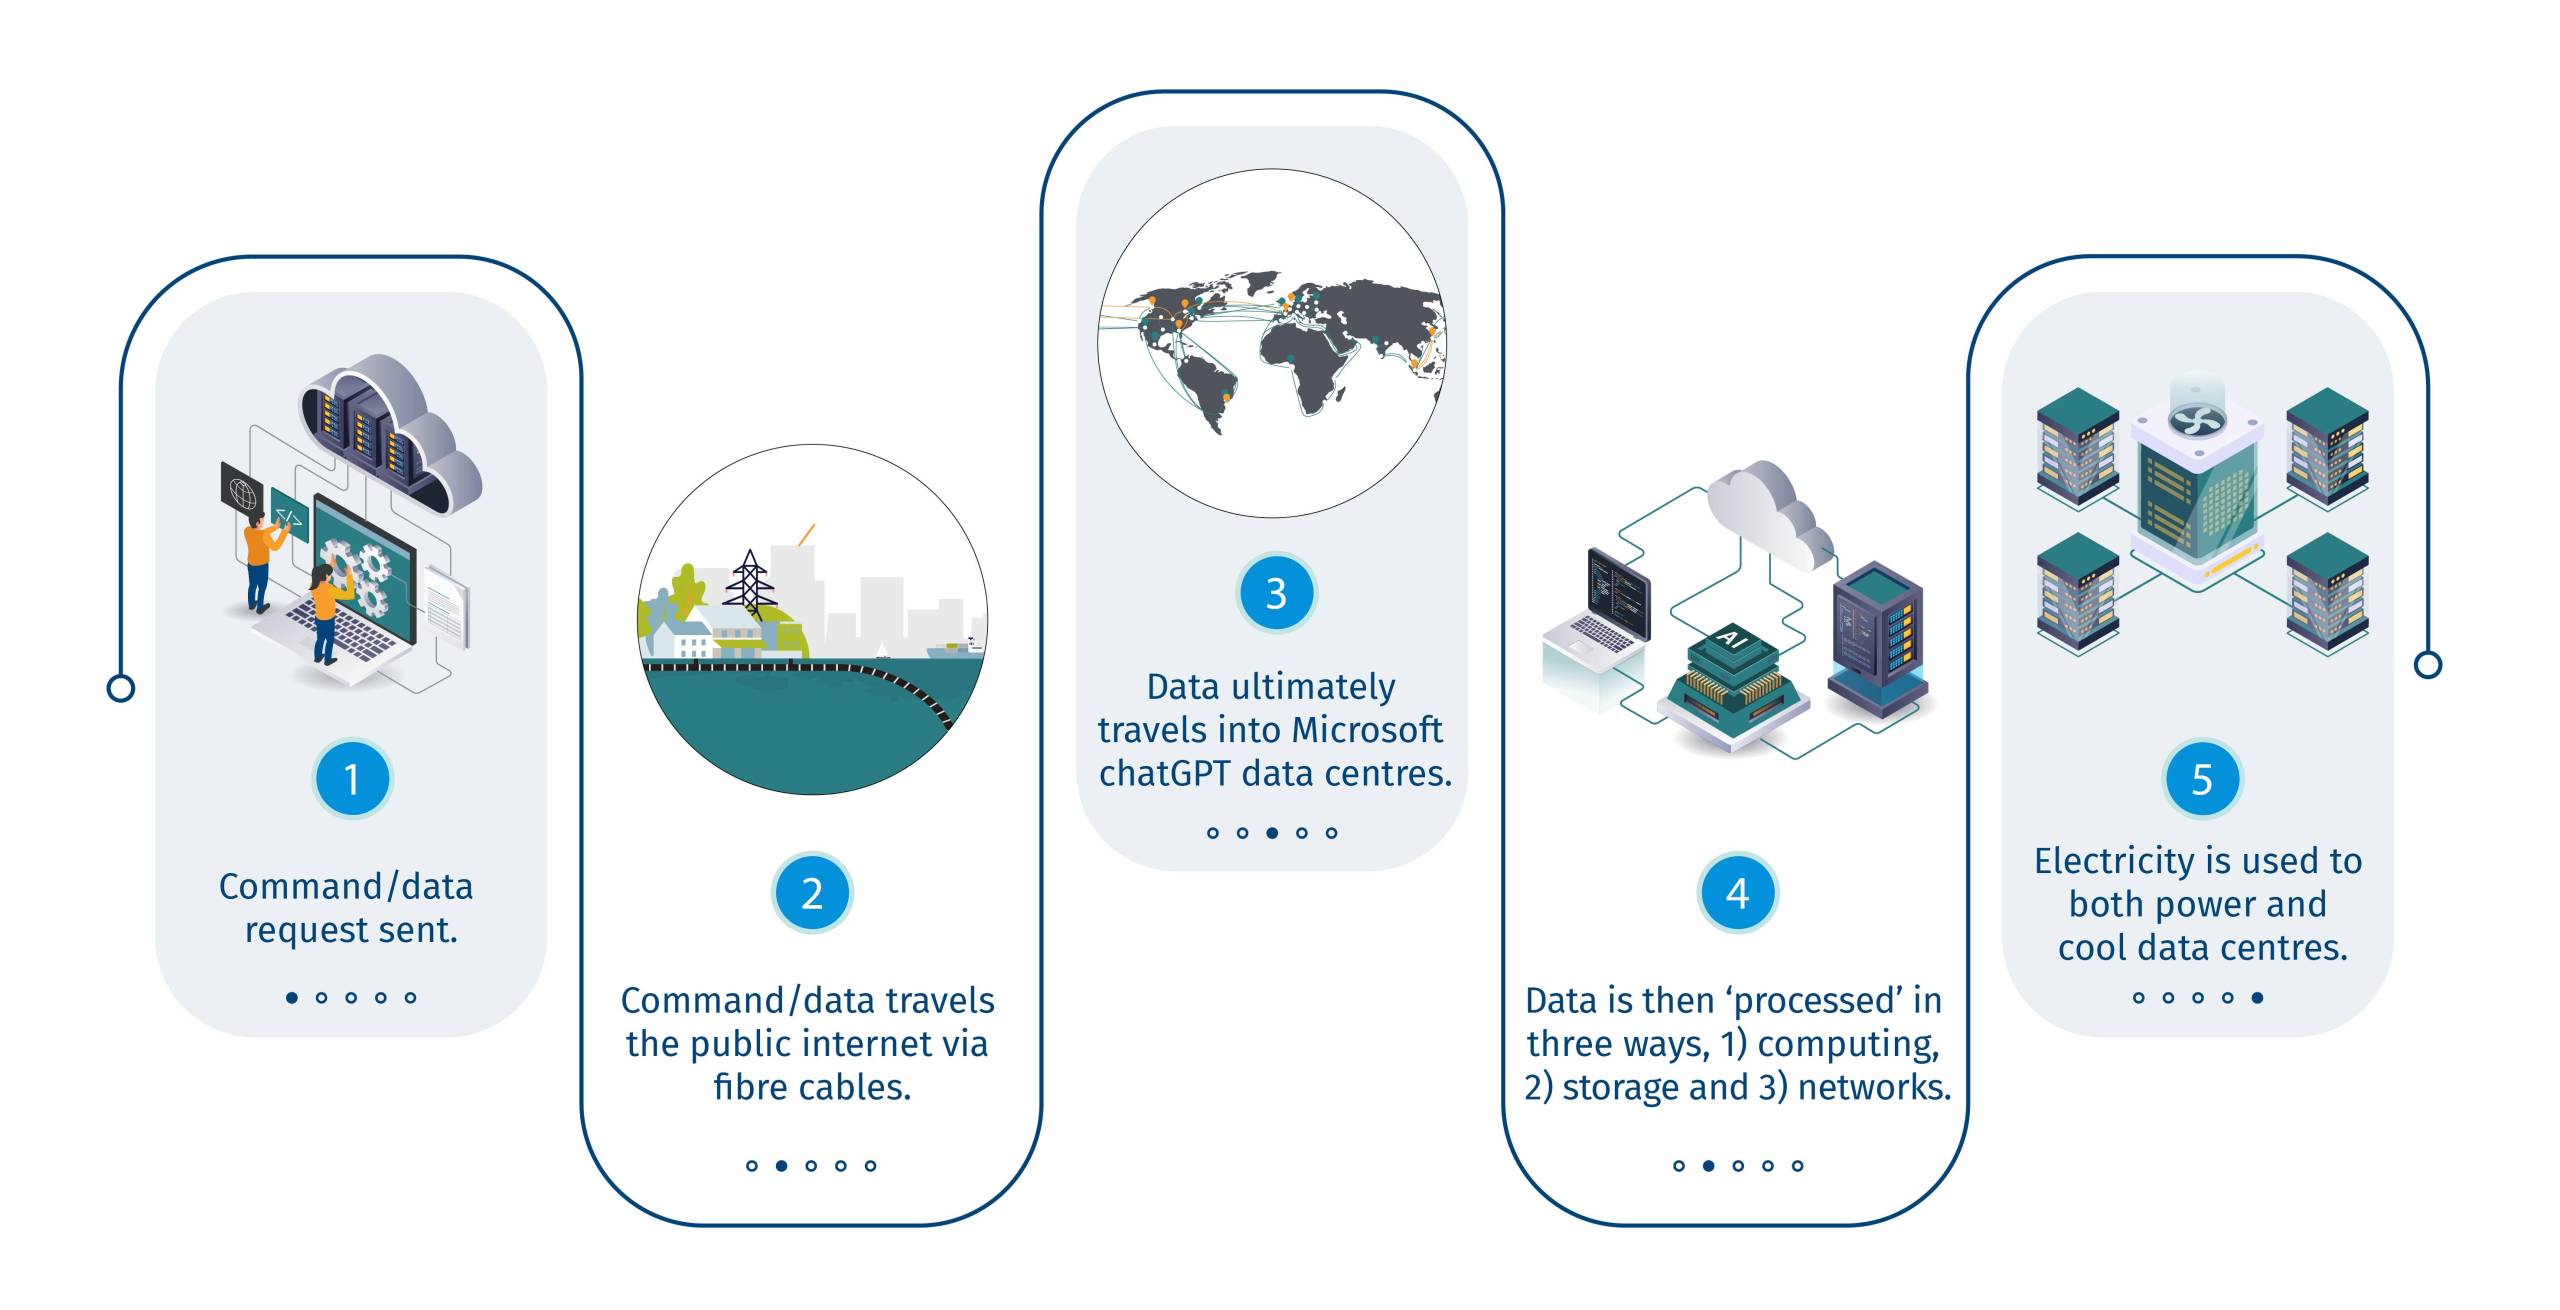
Artificial intelligence (AI) is rapidly reshaping the global economy, driven by Big Tech’s breakthrough apps such as OpenAI’s ChatGPT. Businesses are eyeing ways to transform their operations through AI, which has serious implications—transformative and disruptive—for the wider economy. At the heart of this AI-driven transformation are data centres, the crucial infrastructure powering applications, from simple queries to complex generative tasks.

Every AI prompt requires significant computing power. A single ChatGPT query consumes 10 times more energy than a standard Google search. More advanced AI operations such as generating text or images, exponentially spike power consumption. Canadian data centres’ rising energy demands make them a major driver of electricity demand growth. If all the data centre projects currently being reviewed by regulators proceed, they would account for 14% of Canada’s total power needs by 20301, similar to 12-15% by 2030 in the U.S.2

The development of these data centres, likely between 20 to 30, would result in $100 billion in capital expenditures related to the construction and build of accompanying IT infrastructure3. However, AI’s energy-intensive nature raises concerns about power availability, grid reliability and its implication on emissions.

The power behind ChatGPT: How data centres process search queries


Key Findings

  • Canadian regulators are reviewing data centre applications with an estimated combined capacity of 15 gigawatts—enough to power seven out of 10 homes nationwide.
  • AI is the primary driver of this surge, with data centres offering a $100 billion economic opportunity for the construction and build out of data centres and accompanying data infrastructure.
  • Canada’s clean energy resources offer a strategic advantage for AI-driven growth. However, natural gas remains a critical part of the mix due to its reliability. Nuclear power is also an option but with a considerably longer lead time.
  • Canada’s annual emissions could rise 3%, if natural gas powers six additional gigawatts of data centres. However, carbon capture and storage (CCS) could throttle the rise of emissions.
  • Local data centres strengthen Canada’s position in AI by securing data sovereignty and enhancing cybersecurity.
  • Streamlining AI governance across Canada and the U.S. is a key next step in securing North American leadership. A review of CUSMA in 2026 would likely see refinements to the digital trade chapter.
  • Targeted efforts to increase AI adoption among Canadian SMEs—which account for half of Canadian GDP—could help reverse Canada’s lagging productivity.

A new trading chip

Canada faces a strategic moment as it captures the AI opportunity. Beyond the economic incentives, local data centres are essential for ensuring data privacy, national security, and resilience against cyber threats.

We can leverage our prodigious hydro, natural gas and nuclear power to emerge as a low-cost data centre hub. We can also build on this advantage further by harnessing AI’s power to boost Canadian productivity, enhance our competitiveness, and deepen our digital talent pool.

The AI opportunity also has trade and geopolitical implications, especially as Canada needs ever more chips to bargain with a transactional U.S. administration-in-waiting. With Washington increasingly focused on China, data sovereignty could become a key focus over the next few years. This provides Canada plenty of opportunities—but also some risks.

We could be a valuable partner for the U.S. and create a digital North American fortress, securely warehousing critical data at low cost. But that would require a realignment on data sovereignty between the two countries, which would most likely occur at the next round of Canada-United States-Mexico Agreement (CUSMA) in 2026.

A modernized digital trade chapter—Chapter 19—was a factor that drove Washington to seek a revised trade agreement during U.S. President Donald Trump’s first term. The next iteration of Chapter 19 could increase the focus on compatibility of North American data, both in terms of cross-border transfers and AI governance.


Powering up data centres

Substantial demand from “hyperscalers”—data centres with large compute capabilities—could strain Canada’s grid and drive up power bills, putting governments and regulators in a bind, as recently evidenced with the U.S. federal energy regulator’s refusal to allow Amazon Inc. to purchase more power from a Pennsylvania nuclear facility on the grounds it would raise customer rates and threaten grid reliability.

It also comes at a time many Canadian provinces are already facing sizeable power demands from population growth and electrified transport, as well as ambitions to decarbonize heavy industries. All told, Canada’s power demand was already set to double by 2050, potentially even triple4. And that was before AI became a compelling need for the global economy.

Canada has several energy sources it can draw on to power data centres, but each comes with its own challenges and considerations:

  • Wind and solar: growing sources of power but in the absence of storage, their intermittency makes them unsuitable for data centres that demand consistent baseload power.
  • Nuclear: The emerging energy of choice for Big Tech in the U.S. It’s an option in Ontario, too, but would require long lead times stretching out to a decade, if not more. Nuclear remains a viable long-term solution.
  • Hydro: Several provinces such as Quebec and British Columbia already rely heavily on the power source, and, like nuclear, would require a long time to boost capacity.
  • Natural gas: Alberta’s preferred option, and a key part of Ontario’s transition until 2040. But powering AI through natural gas comes with an emissions cost that provinces will need to weigh.

Provincial Imperatives: Honing regional approaches to AI

Provinces will ultimately drive Canada’s AI ambition.

Alberta, with ample natural gas and lower grid pressures, prefers data centres operate off-grid, minimizing the strain on public grids. The “bring your own power” (BYOP) model allows for faster deployment and supports local natural gas prices, driving economic benefits for the province. It is also aligned with the proposed Canadian Electricity Regulations, given the facilities would not be net exporters to the grid. However, BYOP is not necessarily a viable model for all Canadian jurisdictions.

Quebec, with its rigorous environmental standards and cap-and-trade system, prioritizes low-emission solutions. The province’s hydro power provides clean energy but its capacity to meaningfully expand hydro in the short term is limited. British Columbia faces similar constraints, with a preference for hydroelectric power and tight regulations on carbon-intensive energy sources.

Ontario’s more flexible energy policy allows for a mix of solutions. Its population density and industrial base create competing demands for grid capacity—from electric vehicle and battery supply chain to greenhouses. The province’s primary challenge will be to strike a balance between these competing needs.


Decisions about where and how to build data centres will involve a complex matrix of economic, environmental, and social factors. Our research shows that data centres rank higher in GDP impact compared to, say, manufacturing and transport, but contribute fewer jobs compared to those industries.

That’s where federal and provincial alignment will be critical to Canada’s AI strategy. Policymakers will need to create frameworks that allow provinces to develop bespoke policies that balance growth, sustainability and the demands of the new economy. This includes targeted support for AI adoption among SMEs and ensuring that data centres contribute to productivity gains across sectors. For example, as part of a greater commitment to invest $25 billion in Canadian data centres, Amazon Web Services (AWS) apportioned dedicated compute capacity to the University of Alberta in 2023, sourced from a recently completed $4-billion cloud computing data centre in Calgary.

Power Supply: Capturing the ‘hyperscaler’ opportunity

Data centres require vast amounts of electricity, ranging from 200 megawatts to 500 megawatts. Canada’s low-cost, clean energy gives it a significant advantage. Hydroelectric and nuclear power in cities like Montreal, Vancouver, and Toronto offers some of the cheapest and cleanest electricity in North America. Comparatively, U.S. industrial power prices in key data centre states such as Arizona, Illinois, and Texas are on average 30-40% more expensive, and that excludes their warm climates adding an extra 20-40% power for cooling purposes.

Global hyperscalers are seizing on the Canadian opportunity. We estimate various provinces are reviewing applications for 15 GW of new data centre capacity—a 20-fold increase from current levels5 and enough to power 70% of Canadian households today. In addition, the “expressed interest” in data centres is likely far greater. Alberta alone is being pitched proposals for 50 projects with a combined capacity of 20 GW6.

The mass electrification of the economy is already expected to place unprecedented demand on Canada’s grids. Canada’s power generation is expected to reach 750 GWh7 over the next ten years, compared to an estimated demand of 875 GWh8, implying a shortfall of about 15%. It underscores the need for careful resource management.


Emissions: Leveraging carbon capture

AI’s energy footprint raises concerns about Canada’s climate goals. With provinces being asked to provide power for important industries such as heavy industry, liquefied natural gas electrification and greenhouses, most provinces will have to determine where data centres fit with their economic priority and emissions-cutting ambitions.

Data centres depend on consistent baseload power, which wind and solar cannot reliably provide due to their intermittent nature. New renewable projects are also facing opposition in certain jurisdictions. Natural gas, with its reliability as baseload power and quick scalability, can fill the gap.

However, using gas for data centres raises emissions concerns. If natural gas powers six additional gigawatts of data centres, annual emissions could rise by 16 million tonnes of CO2e—a 3% increase9 in Canada’s total emissions.

Carbon capture and storage (CCS) could throttle the rise of emissions. In Alberta, companies are already in discussions to incorporate carbon capture into gas-fired power plants for data centres. That would alleviate environmental concerns, leverage existing energy infrastructure and drive further investments in natural gas production and the development of CCS.

Big Tech companies, that are investing heavily in nuclear power in the U.S. to feed their AI operations, could replicate that playbook with abated natural gas in Canada.

However, the high costs and technical complexities of CCS mean it’s not an all-of-Canada solution. While the CCS technology is readily transferable, only Alberta and Saskatchewan have the required geology and infrastructure in Canada to store carbon.


Economy: Unlocking a $100-billion opportunity

The digital economy is expanding rapidly, from cloud computing to AI applications, and transforming every aspect of the economy.

Current estimates suggest the digital economy accounts for 6.3% of Canada’s GDP, but broader estimates place it at 15%—and it’s growing 2.5 times faster than conventional economic sectors10. Data centres are critical to this digital ecosystem, hosting and processing the vast volumes of data generated by AI and other advanced technologies. Development of the proposed data centres alone could spark a $100-billion construction and IT infrastructure boom, in addition to its positive impact on the wider economy.

But there’s an even greater prize for Canadian businesses: an AI ecosystem that helps them gain a competitive edge in areas as diverse as healthcare, autos, manufacturing and clean-tech. That could be in the form of AI revolutionizing biotech research, accurately detecting weather patterns, or improving navigation in autonomous vehicles.

Canada’s AI adoption, however, lags its peers. Only 35% of Canadian firms use AI, compared to 72% in the U.S.11 The discrepancy is partially due to the high percentage of small and medium-sized enterprises (SMEs) in Canada, which employ 65% of the private workforce12. SMEs often lack the capital and talent to invest in cutting-edge technology. Addressing this gap is essential to boosting Canadian productivity, which has been in decline for more than 30 years13. With its R&D spending at 1.7% of GDP14—less than half of U.S. levels—Canada faces an urgent need to increase investment in AI and technological innovation.

The federal government has taken steps to close the productivity gap, launching initiatives such as the $2-billion AI Compute Access Fund to boost Canadian businesses’ technological capabilities. The fund aims to deliver computational power needed to drive innovation in both large companies and SMEs.

Bridging the AI adoption gap is critical not only for immediate economic gains, but also for positioning Canada as a global leader in the technology. This includes deepening the country’s AI-ready workforce, with training programs and partnerships with academic institutions key to fostering a new generation of AI professionals.

Data Security: Safeguarding sovereignty and privacy

Data sovereignty is also crucial. Canada’s strict data privacy laws mandate that sensitive information remains within its borders, ensuring compliance and protecting citizens’ privacy. As digital data grows, so do cyber risks. IBM reports 27,000 data breaches in Canada annually, with potential economic losses in the billions.

But keeping data within borders has two inherent tradeoffs: on power and trade. Data centres’ impact on the grid, to date, has been marginal given that in Canada they are used largely for hosting purposes. The proliferation of AI and resulting power draw from hyperscalers, however, accentuates this tradeoff. Most likely, segments of demand will still likely require to be hosted locally, i.e., for economically sensitive areas such as government, healthcare, banking and insurance, and research and development where latency can impact effectiveness.
For other pockets of demand, such as e-commerce, an integrated North American data corridor, as envisioned by OpenAI CEO Sam Altman, could result in comparative advantages for less constrained jurisdictions to power North America’s AI economy. But that would require greater collaboration between Canada and the United States.

Data centres can also help Canada build on its AI expertise. The country has been a leader in AI research since the 1980s, thanks to renowned academics including Geoffrey Hinton and Yoshua Bengio. Yet, the country’s lack of domestic AI infrastructure threatens its leadership. To remain competitive, Canada must likely prioritize dedicated data resources for public sectors such as healthcare, education, and defence. These resources are essential for fostering innovation and maintaining Canada’s technological edge.

Conclusion

There’s an opportunity for Canada to build on its AI leadership beyond economic considerations and productivity. An AI ecosystem can infuse the wider economy with tools that crunch big data and algorithms to boost domestic companies’ competitiveness in areas as diverse as healthcare, clean-tech, manufacturing and services and transportation and logistics.

A flexible approach, combined with federal collaboration, would ensure Canada’s AI infrastructure powers the digital economy in a way that aligns with the country’s broader sustainability, security, and economic goals.

Contributors:

Shaz Merwat, Energy Policy Lead, RBC Climate Action Institute

Yadullah Hussain, Managing Editor, RBC Climate Action Institute

Caprice Biasoni, Graphic Design Specialist

Shiplu Talukder, Digital Publishing Specialist

  1. The data centre power estimate is based on the current set of data centre projects believed to be in application with provincial electricity regulators. Total estimated power consumption for Canada by 2030 is taken from the Canada Electricity Advisory Council.
  2. As estimated by S&P Global, BCG and McKinsey.
  3. Estimate is based on total data centre build costs, including land costs, construction costs, and accompanying data processing and networking, and power and cooling expenses.
  4. Electricity Advisory Council of Canada
  5. S&P Global Market Intelligence
  6. Calgary Herald
  7. S&P Global
  8. Electricity Advisory Council of Canada
  9. Carbon emission estimate of 16 million tonnes of CO2e is based on an assumption of 360 kg/MWh at 6 GW of capacity
  10. Statistics Canada
  11. KPMG
  12. Innovation, Science and Economic Development Canada
  13. Statistics Canada
  14. Statistics Canada

Related Reading

For more, go to rbc.com/climate.

Download the Report

Download

rbc_toc_for_mmm_action

The energy transition presents a chance for Canada’s small, open economy to reset and recharge its global competitiveness.

The race is already on: As countries fuse their economic, environmental and geopolitical objectives, there is a growing imperative to link trade and climate policies. That pressure may grow as advanced economies turn to protectionism, including ways to reduce access for products made in countries with lower emissions standards. In the new trading paradigm, Canada has the opportunity to compete in the exports of low-carbon goods, while also navigating market disruptions caused by emerging clean tech innovations.

Luckily, Canada already has a head start in this low-carbon competition, with industrial carbon markets that can serve as building blocks of innovation, low-carbon economic growth and investment. By fine-tuning and crafting policy that delivers emissions reductions domestically without compromising our competitiveness, Canada can gain an advantage in the new low-carbon economy.

Indeed, industrial carbon markets can become central to Canada’s efforts to address new imperatives brought on by the energy transition. They can help us compete in low-carbon economies, build competitive advantages in international export markets, and decarbonize heavy industries—and get Canada closer to its Net Zero goals.

Yet Canada’s current system remains a patchwork, with nine industrial carbon markets—also known as Large-Emitter Trading Systems (LETS)—that price carbon for heavy industrial facilities. Each LETS has its own subtly different design elements and market conditions that operate within their provincial silos.

The fragmentation of these markets is undermining their potential, and hampering Canada’s ability to build low-carbon industries. Creating room for provinces to tailor their systems to regional priorities and politics makes sense—up to a point. But the current arrangement is hurting small markets with the presence of a few emitters raising transaction costs for firms operating in multiple provinces. As these companies trudge through different compliance rules, they are bogged down in an increasingly complex regulatory environment that slows investment decisions. The slowdown could lead to price volatility, limited participation, low trading volumes and a general lack of confidence in these markets.

Removing interprovincial trade barriers and integrating this patchwork of systems could offer considerable economic upside that could prove to be transformative for Canada’s energy transition.

Benefits Of Harmonization

Gaining efficiency, lowering costs
A firm producing basic chemicals with operations in Ontario and Alberta in Canada’s current system would need to employ two different approaches to calculate its emission limit, to ensure it complies with each province’s laws. That leads to duplication of systems and processes for record keeping, monitoring, reporting, and verification. It also entails greater administrative and compliance costs that will eventually be passed on to consumers. Harmonization could channel more investments in decarbonization and capital expenditures and less in the human capital required to comply with each set of regulations.

Harmonizing the governance can also make markets work better. A robust oversight regime including strong governance, disclosure, and enforcement of standards would contribute to market confidence. While studies examining the integrity and functioning of Canadian carbon credit markets is limited, studies of financial markets suggests that carbon credit markets with these characteristics would improve outcomes for market participants in the form of reduced transaction costs.

A deeper investment pool
Linking markets together is another key component of harmonization, enabling the development of larger markets with a greater number of buyers and sellers that can connect quickly, reducing transacting time and search costs. Robust linkages would also create a larger market for carbon credits that are fungible across different LETS, increasing the pool of potential buyers.

Corporate Canada’s Competitive Advantage

It’s hard to evaluate short-term, sector-level (let alone firm-level) implications of industrial carbon pricing. An industry’s competitiveness will heavily depend on its structure, including costs and profitability, long-term demand for its products, and the existence of cost competitive, low-carbon substitutes. It also depends on whether key trading partners have policies in place that give preferential tariff treatment to goods produced in jurisdictions with carbon pricing schemes. And this is without accounting for other forms of policy support.

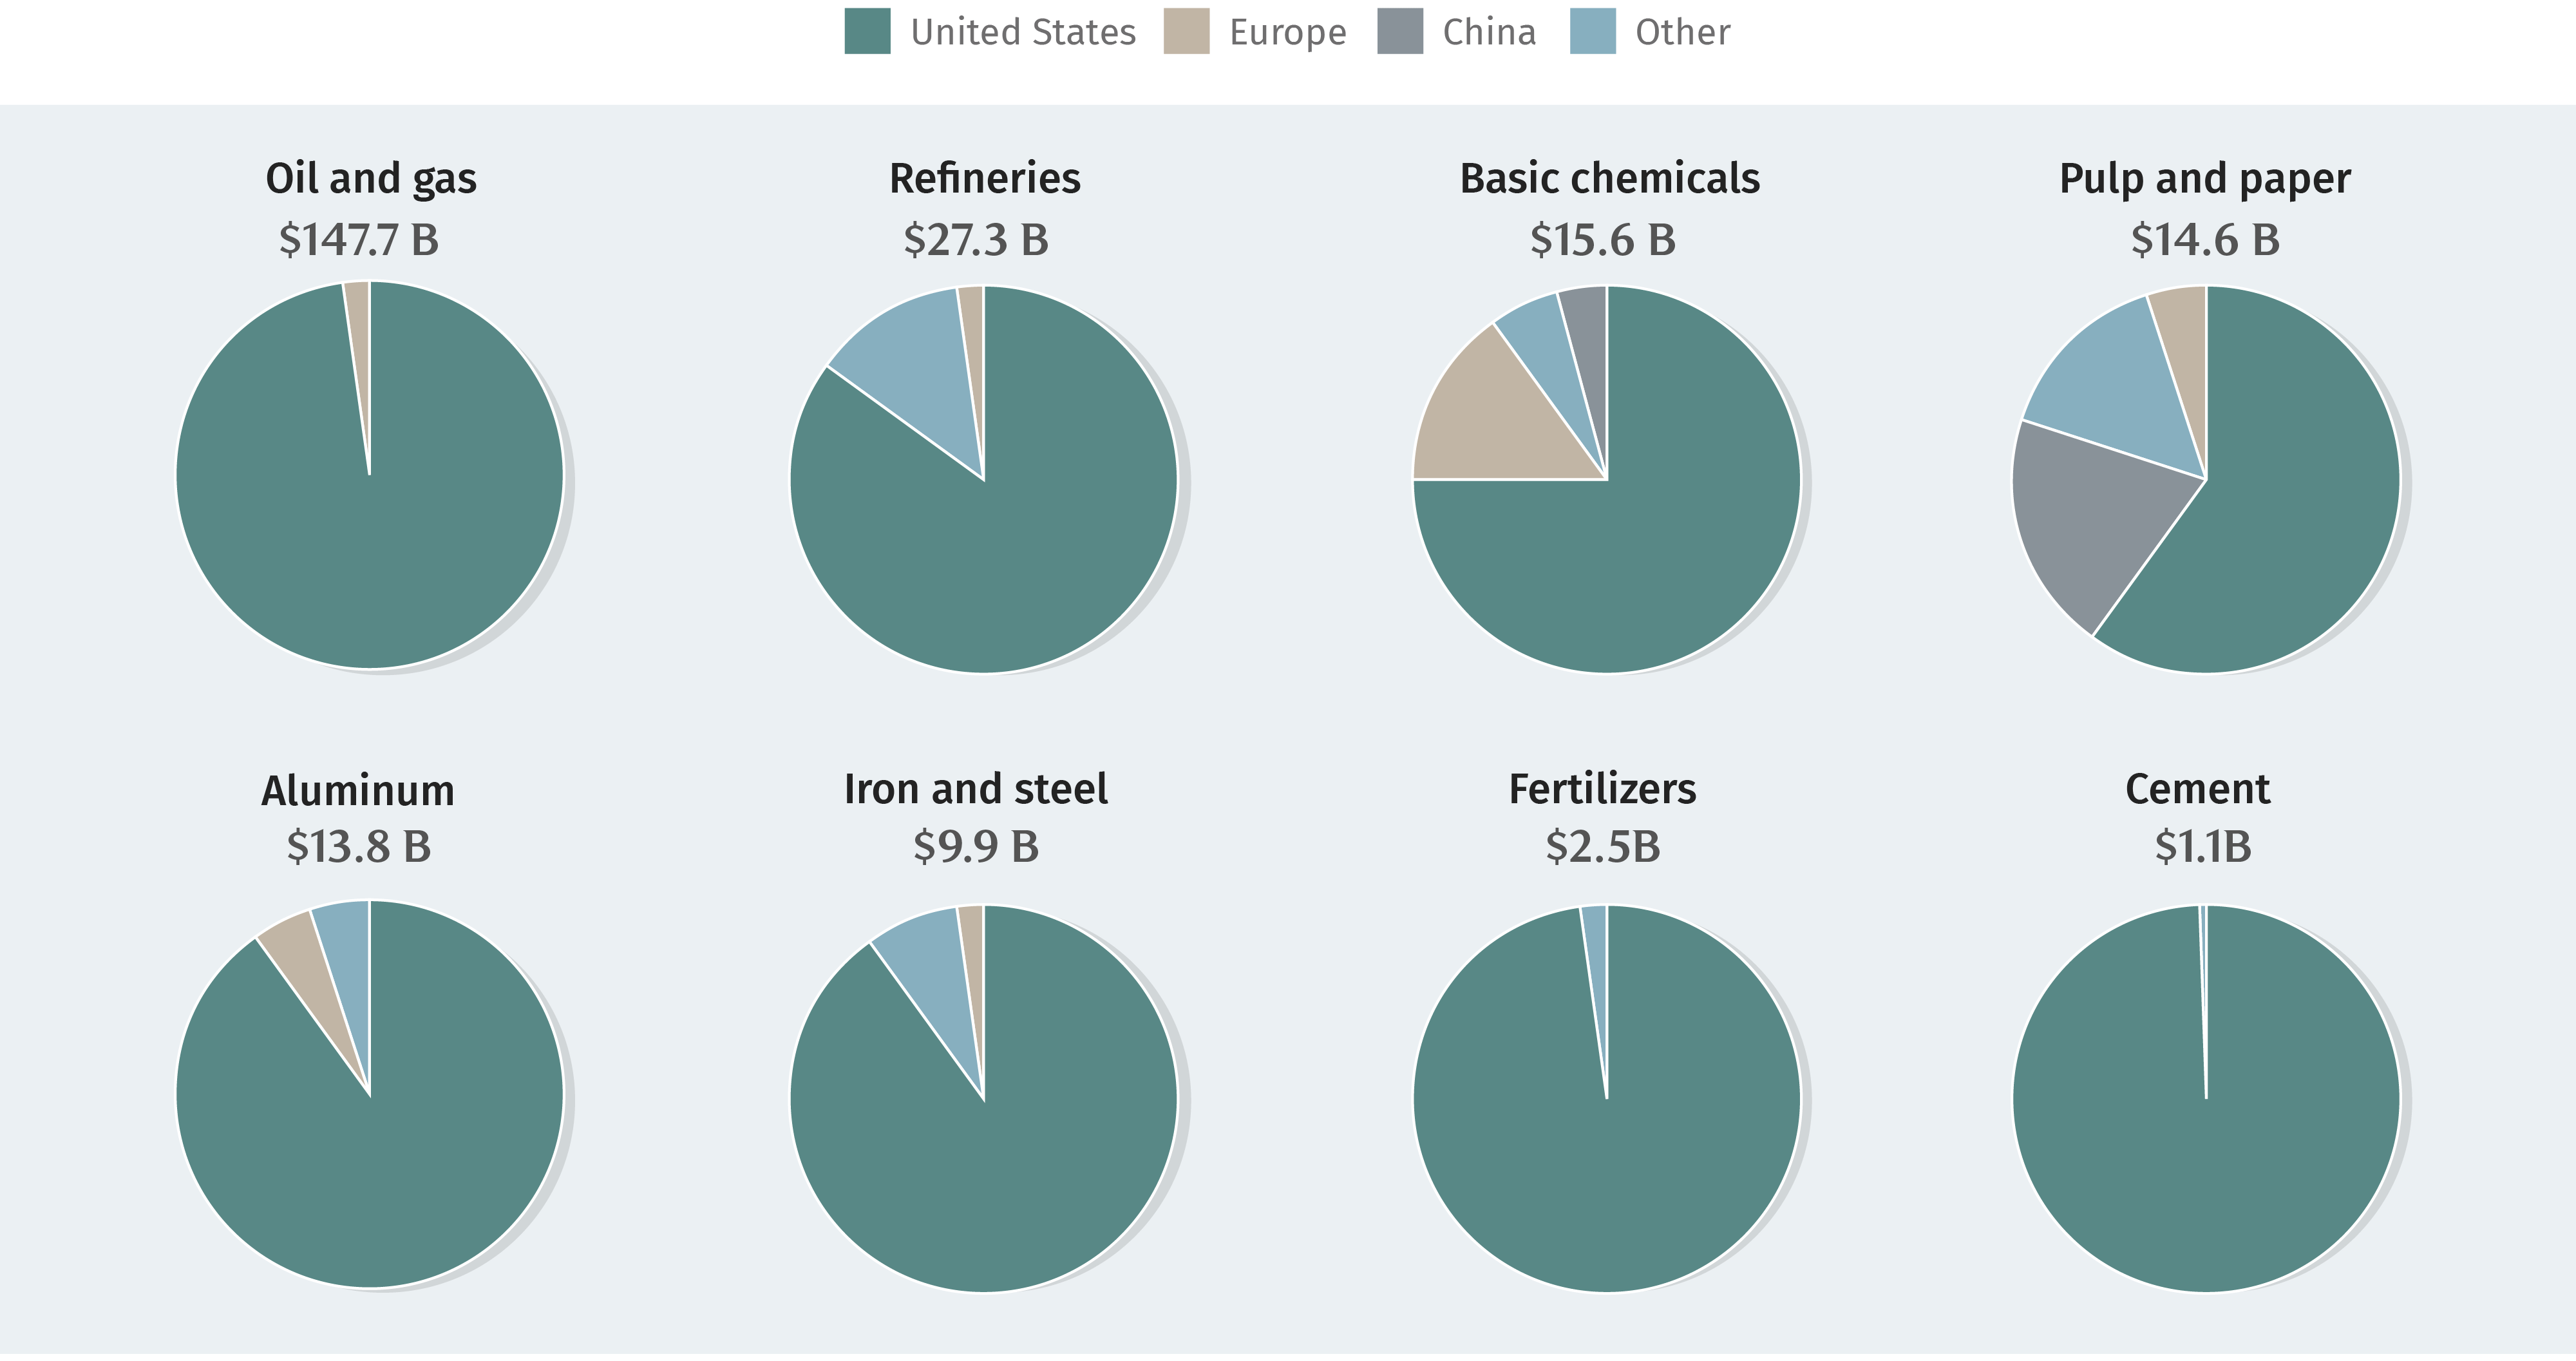
Canada’s carbon pricing scheme covers eight key Emissions Intensive Trade Exposed (EITE) industries. The goods produced by these industries, which last year contributed $232 billion to the Canadian economy, are exported to three key trading partners–the U.S., which is Canada’s largest trade partner, the EU, and China.

Canada’s Biggest Carbon-Intensive Exports

Canada’s top export destinations for its carbon-intensive products

Source: RBC Climate Action Institute analysis of Statistics Canada data

Competing with Trade Partners
The EITE industries expected to benefit from carbon pricing are those with significant trading activity with the EU and China—both have LETS of their own, with vastly different dynamics.

Canadian goods are anticipated to be cost competitive with those produced in the EU, given similar industry cost structures and stringency of the EU’s carbon pricing regime. The EU’s Carbon Border Adjustment Mechanism (CBAM), set to come into effect in 2026, is a tariff scheme that gives preferential treatment to goods produced in countries with carbon pricing will have limited impact in eroding the cost competitiveness of iron, steel and aluminum produced in Canada.

Exports destined for China will have a harder time competing on price, given China’s substantially lower cost structures compared to Canada. It’s an advantage that is supported by China’s extensive use of subsidies in key industries and an abundant supply of low-cost labour. China’s relatively lower carbon price of $19 per tonne of CO2e, compared to Canada’s $80 per tonne CO2e, would have limited impact on eroding the cost competitiveness of Chinese goods compared to Canadian goods.

At face value, industries exporting to the U.S. are also at a cost disadvantage since there is no federal carbon pricing regime stateside. Canadian goods with embedded carbon costs would have to compete with U.S. goods without this cost.

Part of this cost disadvantage for key industrial sectors can be offset through system design, as well as the revenues that firms can generate from carbon credits. Recent research from Clean Prosperity and the Transition Accelerator found that revenue generated by carbon credits is the largest policy incentive available to most sectors within heavy industry. They remain Canada’s lowest-cost policy option to attract low-carbon investment into the country. In the long-run, these investment flows can position Canada to be globally competitive in new low-carbon industries.

Beyond Industry Bottom lines
Cost competitiveness, however, should not be equated with profitability and the long-term viability of an industry. Profitability ebbs and flows with economic cycles.

The viability of any industry depends on long-term demand. Canadian exports to the U.S. are concentrated in three industries, with oil, natural gas and refined petroleum products, such as gasoline, accounting for 79% of all EITE exports. Greater electrification, including the shift from gas-powered to electric-powered cars, less reliance on natural gas for space heating and electricity generation, and energy efficiency improvements is changing the U.S. energy mix, and shrinking the long-term demand for oil and natural gas.

Falling demand and market size at the industry level does not necessarily lead to broader economic stagnation. A study of B.C.’s carbon market found that, in the aggregate, carbon pricing does not have an adverse impact on its economy or employment, with employment shifting from emission intensive industries to cleaner ones. A study of the French carbon market also found similar greening of employment—evidence that carbon markets are operating as predicted by economic theory.

Similarly, Germany, the European Union’s largest economy and heaviest emitter within the EU carbon market, was able to leverage carbon pricing to cut the emissions intensity of industries, by reducing consumption of natural gas and petroleum and improving the energy efficiency of industrial processes, according to a study. This was achieved without lowering employment, GDP growth or exports.

There are limited data and studies providing insights on how Canadian provinces have adjusted their economic development strategy to safeguard their EITE industries. Some jurisdictions such as Alberta have addressed this policy challenge by building regulatory compliance flexibility into its carbon pricing regime.

Such policies also aim to ensure industries are not fiscally penalized, in the short run, as they invest in low-carbon technology, which are costly long-term investments. Under Alberta’s Technology Innovation and Emissions Reduction Regulation (TIER) system, firms can seek regulatory relief if compliance costs exceed 3% of sales or 10% of profits. In these situations, firms can use a greater number of carbon credits to reduce their compliance obligations and/or seek a greater “free” emission allowance.

Businesses repeatedly cite regulatory uncertainty as an impediment to moving forward with investment decisions. Harmonization can provide investors and markets with the certainty they need to invest in the country’s energy transition.

Navigating politics
Despite the many economic and trade benefits, and industry’s appetite for less regulatory complexity, harmonization has not been pursued for two key reasons. For some provinces, there’s a perception that harmonization could lead to an erosion of provincial autonomy to make decisions that protect their key industries. Harmonization introduces the need for greater coordination and consensus building. Processes that some provinces fear could limit their regulatory responsiveness to changing global market and regulatory conditions, and which is required to keep the industries located within their borders competitive. Many of these concerns can be addressed through governance frameworks when harmonizing the country’s LETS.

How To Harmonize LETS

LETS in Canada are already harmonized in some rudimentary ways, primarily through the headline price of carbon, which currently stands at $80 per tonne. But most of the finer details of both market design and market function vary from province to province—most notably the rules around who can hold and trade credits.

Harmonizing LETS and removing these interprovincial trade barriers will require reconciling details across systems that are at different stages in their development and maturity.

Except for Quebec, which shares a cap-and-trade system with California, all provincial and territorial use LETS known as output-based pricing systems. These systems regulate facilities based on their emissions intensity, rather than on their total emissions as with cap-and-trade. We limit this analysis to harmonizing output-based LETS across Canada. Integrating cap-and-trade and output-based markets beyond the headline price would be a far more complex, long-term challenge.

On both the substance and process of harmonizing LETS, federal and provincial governments can lean on their experiences with domestic trade deals in the pursuit of harmonization.

We outline two broad approaches.

All Parties Model
Harmonization through the All Parties Model requires strong central leadership with common standards across all provincial LETS. The Canada Free Trade Agreement (CFTA) offers a useful analogy for this more “top-down” approach to removing trade barriers. In the CFTA, the federal government and all provinces and territories have agreed to a shared set of provisions, definitions, rules, exceptions, institutional arrangements (e.g. dispute resolution), and exceptions, with a stated objective to “reduce and eliminate, to the extent possible, barriers to the free movement of persons, goods, services, and investments within Canada and to establish an open, efficient, and stable domestic market”.

Canada’s current approach to LETS, under the umbrella of the federal Greenhouse Gas Pollution Pricing Act (GGPPA), is but one possible version of the All Parties Model. Under the GGPPA, provinces are encouraged to establish and administer their own LETS.

On a rolling five-year basis, Environment and Climate Change Canada (ECCC) evaluates the performance of provincial LETS and negotiates with the provinces regarding the “equivalency” of their performance to federal standards. ECCC assesses equivalency every five years, with the next review coming in 2026. This will be the first review for some of Canada’s youngest LETS, most notably British Columbia, Saskatchewan, and Ontario.

Willing Partners Model
The Willing Partners Model offers a roadmap for any two (or more) provincial governments to harmonize their carbon markets. An analogous, “bottom-up” approach to removing trade barriers is the New West Partnership Trade Agreement (NWPTA). Through this effort, signatory provinces—British Columbia, Alberta, Saskatchewan and Manitoba—engage in a mutual effort to “liberalize trade, investment and labour mobility”. The provinces continue to amend, expand and update the agreement, most recently in 2022.

The Willing Partners Model is fundamentally an opt-in model. In the NWPTA, provinces agree to six shared criteria: definitions, obligations, rules, provisions, dispute resolution mechanisms, and exceptions to the agreement. Establishing shared criteria would be a starting point for any iteration of the Willing Partners Model for LETS. Fewer negotiating parties with a model that is voluntary can lead to an agreement with stronger shared criteria with a clearer value proposition for participating provinces.

A Willing Partners Model can also coexist alongside an All Parties Model. Just as any province can exceed the federal standards for LETS set out in the GGPPA, the NWPTA also defers to the Canada Free Trade Agreement (CFTA), where the provisions of the latter are “more conducive” to liberalization of interprovincial trade.

Degrees of harmonization
Beyond broad design details like the headline carbon price, there are many program elements of LETS that are not harmonized. Integrating these systems does not have to happen all at once. This gradual, step-by-step harmonization is also known as degrees of harmonization.

Two Components Of Harmonization

There are two core components to market harmonization. Governments can pursue each subcomponent individually or as part of a larger effort toward full harmonization.

Harmonizing market design
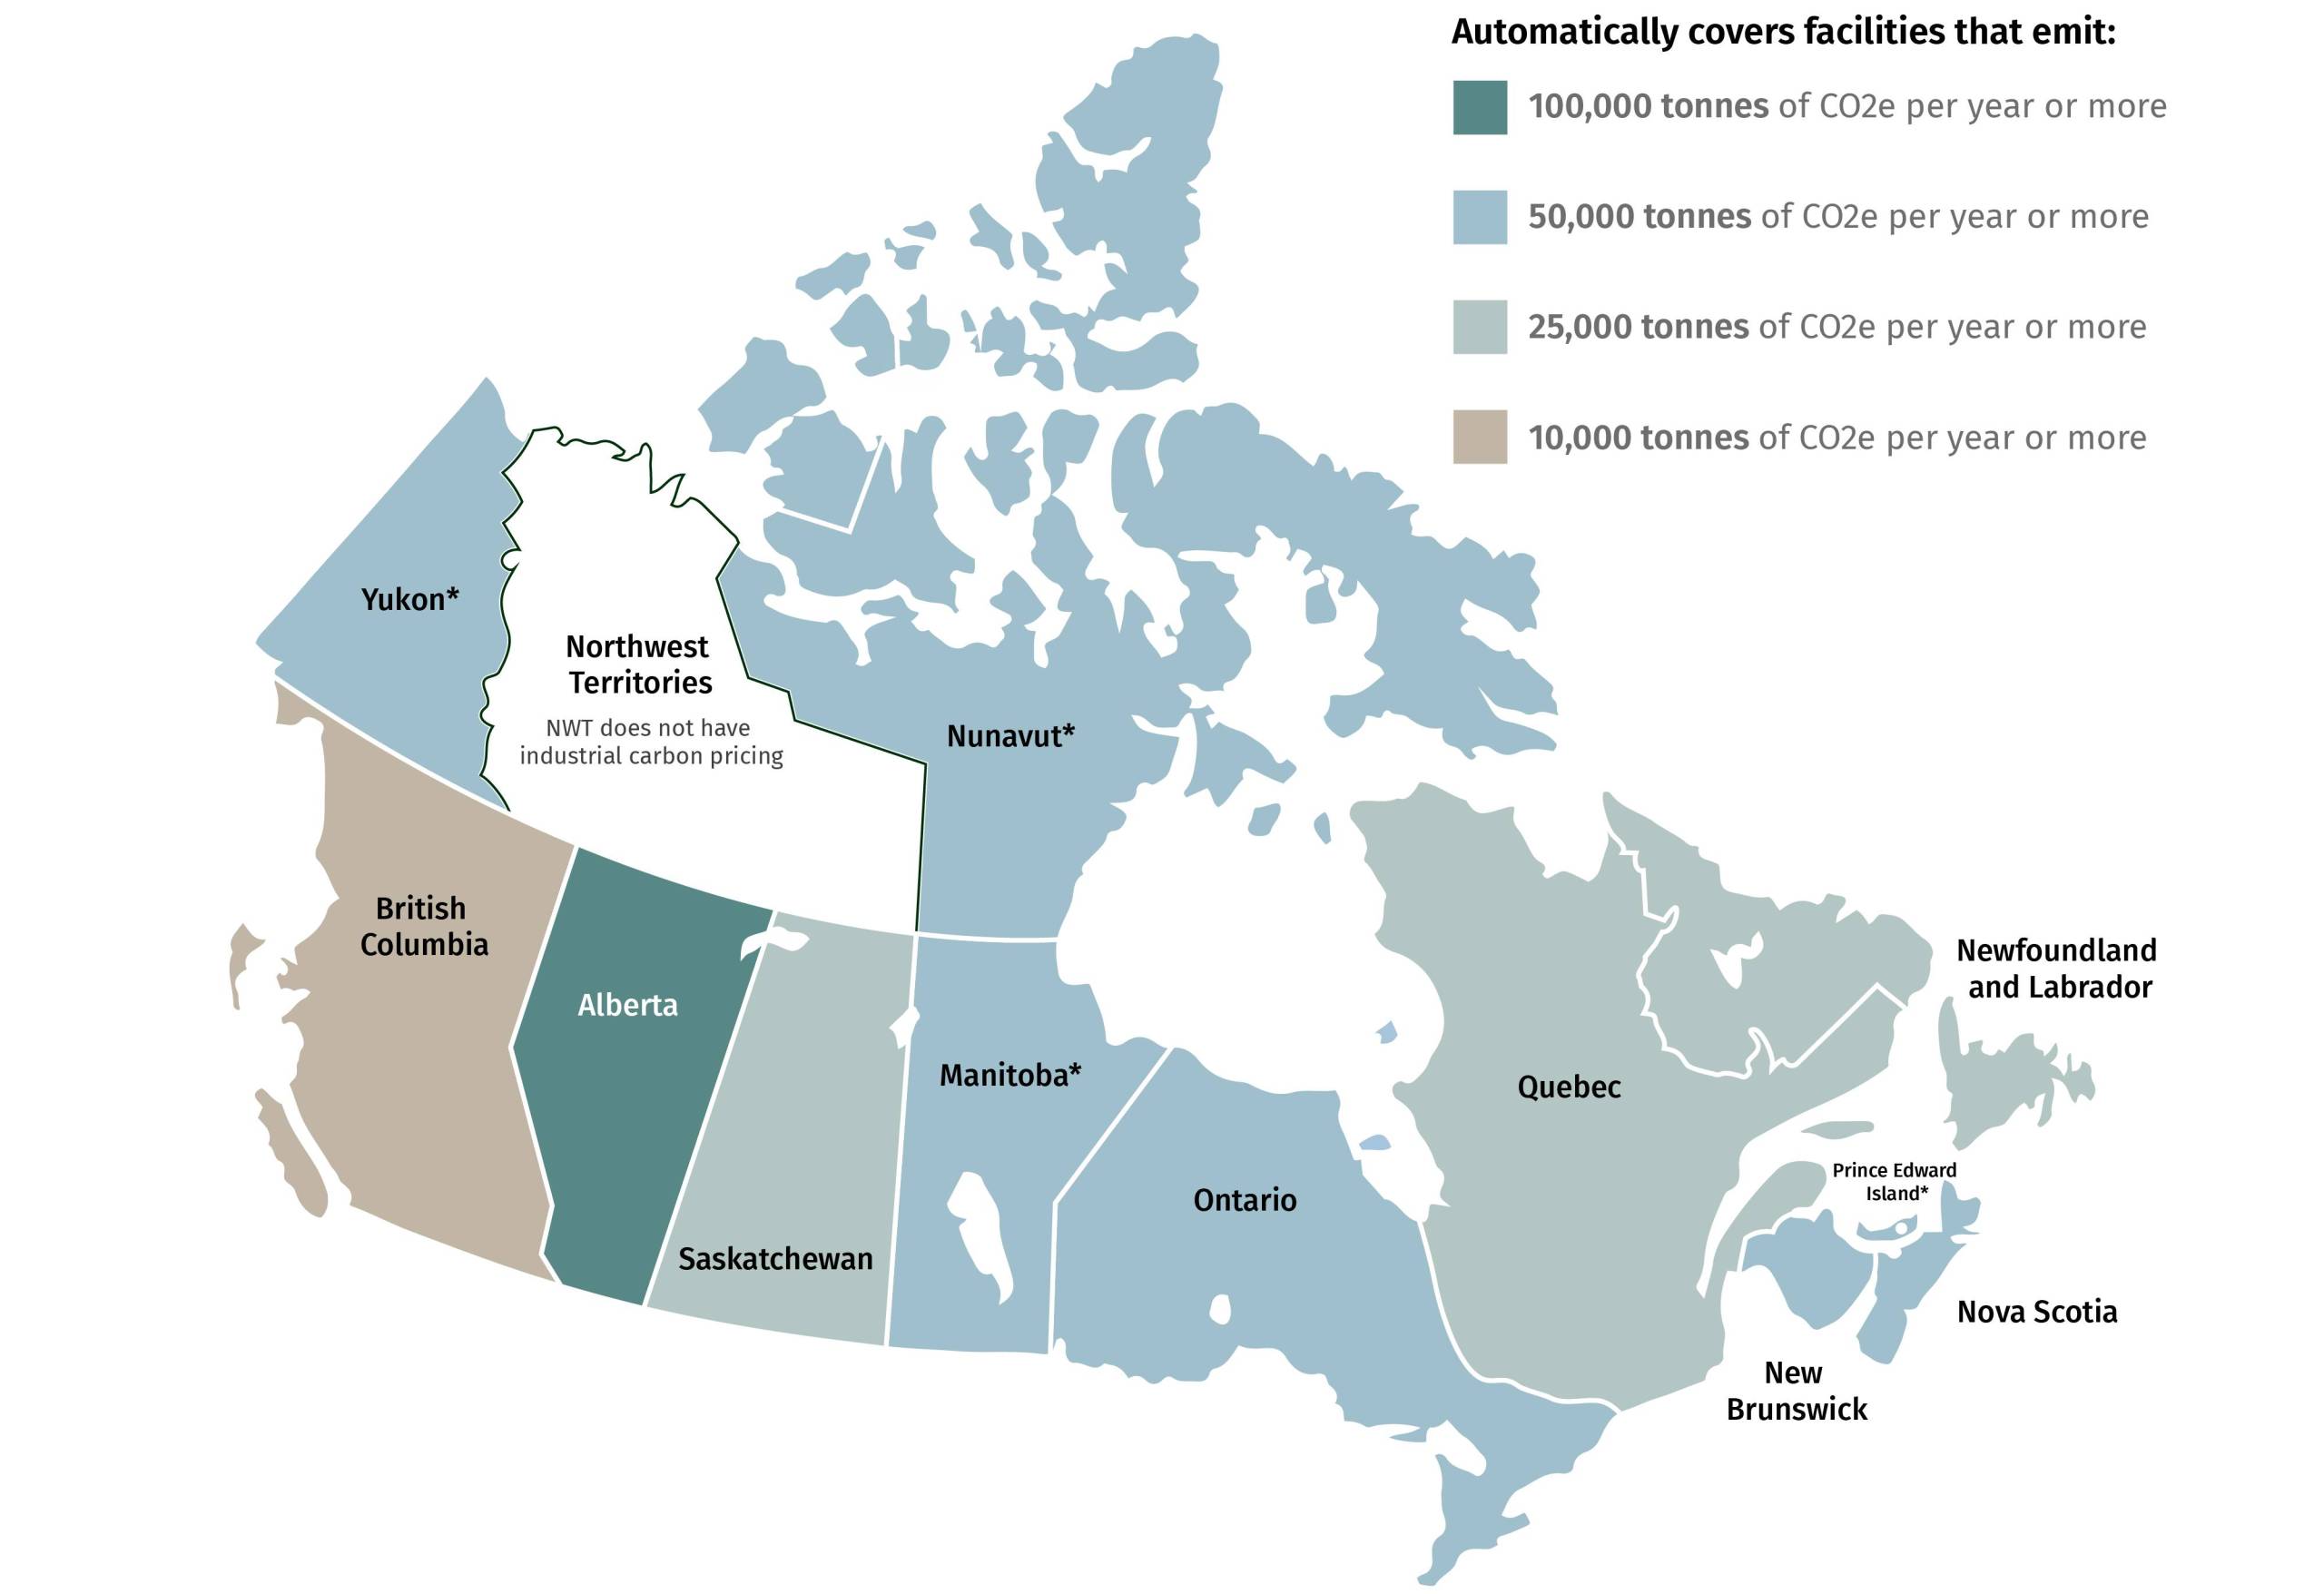
LETS market design involves decisions around how the carbon market will legally operate. This include what sectors will be covered by the program, the price of carbon and how exposed emitters will be to that price, who can hold carbon credits and under what conditions, and rules around monitoring, reporting and verification (MRV), including enforcement and non-compliance penalties. To take just one example, facilities that emit above a certain amount are automatically covered by LETS, but this coverage standard varies widely from province to province. Most LETS also allow smaller facilities to opt into and benefit from the program, but this standard also varies from province to province.

A Patchwork Of Carbon Coverage Standards

Canadian jurisdictions have different coverage threshold for large emitters

*Covered under federal framework

Source: RBC Climate Action Institute

Bringing markets in synchronicity
Full harmonization of market function includes full removal of interprovincial trade barriers, with fungible credits that are tradeable across provincial borders.

There are several elements of market design that need to be harmonized before this can occur. Some LETS have many different types of credits with unique properties. Alberta’s TIER system, by far the largest and most mature provincial carbon market, makes use of many different types of carbon credits to facilitate growth in different sectors. For instance, Alberta has two types of carbon credits with features that are specifically designed to encourage adoption of carbon capture technologies. Most other systems have a single credit type, and are more restrictive on who can hold carbon credits and participate in the market. These rules would need to be relaxed to facilitate harmonization of market function.

Beyond the mechanics of credit trading, true fungibility would also require harmonizing decisions around governance and review, including shared processes for evaluating the efficacy of different markets and the competitiveness performance of the firms participating in these markets.

Different provinces have very different industrial profiles and therefore face different competitiveness challenges. There is an urgent need for research detailing the opportunities and risks facing Canadian heavy industry as it seeks competitive advantages in a carbon-constrained world.

Canada’s current governance model for LETS—reviews in five-year increments—is sluggish. Provinces have the discretion to review and adjust benchmarks as needed, but have not done so to date even with looming risks of credit oversupply. Harmonized markets would need to make greater use of proactive strategies that can stabilize expectations around credit prices, respond to rapid or disruptive change in global markets, and reduce regulatory uncertainty for investors and operators. These strategies could include but should not be limited to policy tools such as carbon contracts and adaptive benchmark tightening.

Lastly, a shared commitment to measuring the outcomes of harmonization and the effects on provincial economies could help ensure data-driven decision-making around LETS moving forward. Provinces could also share digital infrastructure, registries, and programs that allow for credit tracking across participating provinces to maximize transparency to the broader public.

A Chance For Policy Alignment

Securing Canada’s economic future requires seizing every competitive advantage available. Many provinces have spent the better part of a decade (or more) standing up their LETS as a central plank of their decarbonization and low-carbon economic strategies. But the country’s fragmented approach to LETS presents significant opportunities for improvement. Taking stock of global market dynamics and trends towards protectionism, nearshoring and decarbonization, it may be time for a dialogue about what the next decade should look like for LETS in Canada. Harmonization, as part of a broader vision of economic competitiveness, should top the list for discussion.

Harmonization could help ensure that LETS play an outsized role in advancing Canada’s economic, environmental and geopolitical objectives. Global economic competitiveness, investments in technology and innovation, reduced regulatory red tape and costs: These and other benefits arising from harmonizing LETS are too numerous to ignore.

As policymakers shift their attention to the back half of the 2020s, and a more fragmented world, a fresh approach to our carbon markets could strengthen both trade and climate policies, and foster a new cycle of lower-emissions growth.

Contributors:

Myha Truong-Regan, Head of Climate Research, RBC Climate Action Institute

Brendan Frank, Director of Policy and Strategy, Clean Prosperity

Dale Beugin, Executive Vice-President, Canadian Climate Institute

Yadullah Hussain, Managing Editor, RBC Climate Action Institute

Caprice Biasoni, Graphic Design Specialist

Related Reading

Owning the climate podium:

10 ways Canada can accelerate investment in decarbonization

High Rise, Low Carbon:

Canada’s $40 billion Net Zero building challenge

Power Shift:

How Ontario Can Cut Its $450-Billion Electricity Bill

For more, go to rbc.com/climate.

Download the PDF

Download

rbc_toc_for_mmm_action

There is a buzz around hydrogen. It comes in many iterations—geological, low-carbon, and conventional, and everything in between—and has seen billions of dollars of investment across the world. Depending on how hydrogen is made, it is labelled green when manufactured using renewable power, and blue when using natural gas and capturing the emissions, although several other ways of producing hydrogen exist. Its properties as an energy carrier and a chemical feedstock promise to make significant contributions to decarbonizing the world. Canada can play a role here to meet continental, perhaps even global, demand. For now, the country’s hydrogen production remains modest: we produce about 3,500 tonnes of low-carbon hydrogen, several orders of magnitude less than the three million tonnes of fossil-based, carbon-emitting hydrogen it consumes to service its oil and gas, petrochemical, and fertilizer sectors. Scaling up low-carbon hydrogen production to replace this would help Canada achieve its Net Zero goals, but it has a long way to go—in technology, regulations and application—before it can emerge as a formidable alternative to conventional hydrogen and fossil fuels. The good news is that progress is already underway. Since the federal government published its hydrogen strategy in 2020, 80 low-carbon hydrogen projects valued at over $100 billion in investment have been announced or are under consideration or development. Provincial strategies are taking shape and pilot projects, across applications from steel to space heating, are demonstrating hydrogen’s potential to replace fossil fuels and lower emissions in areas where it has not traditionally been applied. And with at least 13 known partnerships between hydrogen proponents and Indigenous communities already established, a hydrogen-fueled future in Canada could be built on a strong foundation of Indigenous engagement. Hydrogen could be one of the pillars of a decarbonized Canada. Canada’s 2020 hydrogen strategy projected production trebling to 21 Mt per year by 2050, accounting for a third of Canada’s final energy consumption—an ambitious growth trajectory. In theory, hydrogen could flow through natural gas distribution lines, fuel heavy-duty trucks that are the backbone of inter-regional trade, and burn in power plants to keep the lights on in homes, all while lowering emissions if produced cleanly. It could also form part of a new export industry, transporting energy from the East Coast’s best-in-class wind resources to Europe and support the continent’s energy independence from natural gas. But as the federal government’s May 2024 strategy update shows, a lot hinges on which applications see uptake of hydrogen in favour of other solutions. Demand could vary significantly, from 3 to 20Mt/year—that’s a 17Mt/y spread, suggesting uncertainty around hydrogen’s potential. This uncertainty stems from hydrogen’s innate complexities and the competition it faces from other clean technologies. Here are some hurdles the industry must overcome:

1. A question of logistics

Hydrogen is inefficient to make and difficult to transport. Converting renewable power into hydrogen results in 30% to 40% less energy than if the electricity was used directly, such as through a heat pump for space heating. And once manufactured, moving hydrogen to its destination is challenging because of high energy requirements for compression, limited hydrogen pipelines in the country, and the inability of natural gas pipelines to channel high concentrations of hydrogen without risking damage.

2. Footing clean hydrogen’s energy bill

Canada’s rich hydroelectric and nuclear generation resources and strong methane regulations are an advantage, but will only take us so far in an age of increasing energy demand and rising costs. Hydrogen’s efficiency challenges mean that Canada will need a lot more renewable energy generation to make green hydrogen, and strong carbon capture, utilization and storage (CCUS) infrastructure to lower the CO2 emitted from making blue hydrogen. Blue hydrogen manufacturing will also need Canada to step up methane leak monitoring and mitigation. These measures will allow Canada to manufacture the hydrogen it needs without straining electricity grids or increasing overall emissions because of methane leaks.

3. Competing with the IRA

Lowering hydrogen manufacturing costs will also be key while maintaining an investment environment that’s attractive to global hydrogen companies. The biggest competition comes from the United States, where tax credits under the Inflation Reduction Act (IRA) give hydrogen developers a revenue premium over Canadian incentives. Canada’s Clean Hydrogen Investment Tax Credit (ITC) could offset 15% to 40% of hydrogen costs and help close the gap with the U.S., especially as new, restrictive guidance on IRA credit eligibility makes incentives down south more uncertain. For costs to go down, Canada’s hydrogen ITC must progress through legislation quickly and demand for clean hydrogen must scale. Hydrogen’s potential applications are as numerous as its varied colours. But prioritizing high-impact early projects will help calibrate the demand hydrogen needs to match supply-side incentives. Canada needs to be tactical in the near term to ensure that existing hydrogen supply is decarbonized quickly, and that the most promising pilot projects and economic sectors receive the support they need to deploy hydrogen at scale. Vivan Sorab is RBC Climate Action Institute’s Senior Manager, Clean Technology.

rbc_toc_for_mmm_action

Canada has urgent and challenging energy choices to make. We will need to rapidly scale power generation to service the needs of a growing economy, while simultaneously reducing net-carbon emissions to zero by 2050 to meet our climate targets. Given the current technological outlook, there is no single energy source that can meet those competing demands. But one thing is clear: nuclear power can be a key part of that lower-emissions future — and an increasingly promising option is to commercialize small modular reactors (SMRs). SMRs are more adaptable versions of today’s large-scale reactors and could solve many of the issues facing the nuclear industry. While most SMRs are still on the drawing board, they promise to reduce the costs of construction and operations, expand the range of applications across the economy, and potentially improve safety factors. If commercialized successfully, SMRs could bring new, non-emitting sources of electricity to big cities and remote communities, while providing flexibility to key Canadian industries that now power production processes with fossil fuels.
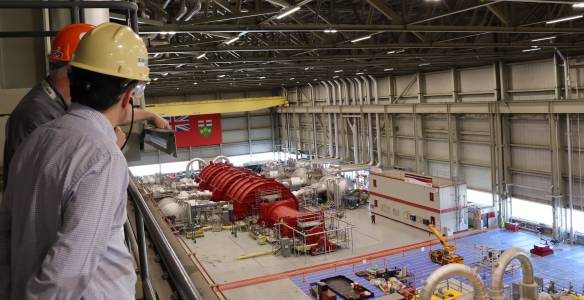
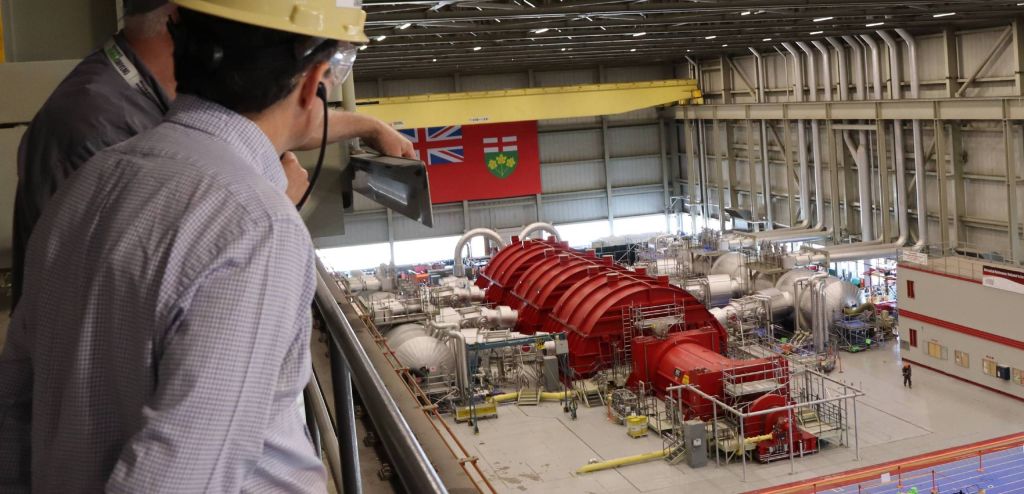
Darlington Nuclear Generating Station
Darlington Nuclear Generating Station Vivan Sorab, Senior Manager, Clean Technology RBC (Left), John Stackhouse, SVP, Office of the CEO RBC (Middle), Chuck Lamers, Senior Communications Advisor (Right)
The repercussions of SMRs could be far-reaching, with the global SMR market projected to reach $150 billion to $300 billion annually by 20401. Given the country’s seven decades of success in nuclear energy, Canada starts from a position of strength. SMRs could revitalize Canada’s nuclear industry, allowing us to export our talent and proven expertise to a world that is committed to triple nuclear power by 20502. Several countries including the U.S. and Britain have announced major public-private partnerships to capture those opportunities. Canada has already taken an early lead in deploying a new generation of SMRs. One such reactor—GE-Hitachi BWRX-300—is close to the start of construction at the Darlington Nuclear Generating Station east of Toronto. That single SMR, the first of four that will be built at Darlington, could eventually provide electricity for 300,000 homes3. Other SMRs in various stages of licensing across the country could eventually power industrial facilities and remote mines and replace diesel in isolated communities.
  • Types of SMRs SMRs vary in size, design and components, electrical and thermal outputs, and intended applications. Early SMRs will be used to generate electricity for cities, but the technology’s versatility could mean that scaled-down, or micro-SMRs, could eventually be used by industries, small, off-grid communities, and mines. Like large nuclear reactors, SMRs are broadly classified based on how they are cooled and the way their fission reactions are controlled.
    Light and heavy water reactors The most established technology, use water to cool the reactor core and slow down neutrons – subatomic particles that help sustain nuclear fission reactions.
    High-temperature gas-cooled reactors Uses gases like helium to cool the reactor core and have faster neutron speeds, allowing higher temperatures to be produced.
    Molten salt reactors Use salts to cool the reactor core. They can operate at high temperatures and can use a range of fuel types.
    Fast neutron reactors As their name suggests, fast neutron reactors use fast neutrons to trigger and sustain fission reactions, making reactors more fuel-efficient and increasing power production.

Source: US Department of Energy

To optimize the drive to net zero, Canada has formulated a national plan to develop and commercialize SMRs. In 2018, Ottawa created a coalition drawn from various levels of government, Indigenous communities, academia, power utilities and other industries to draw up a coordinated Small Modular Reactor Roadmap4. This was followed by an SMR Action Plan in 20205. To remain at the forefront of a potential SMR revolution, Canada must seek further ways to finance and regulate the development and commercialization of reactors. No one expects that will be straightforward. But an effective rollout of a nationwide plan to deploy SMRs promises an adaptable new energy source for the country, and a powerful catalyst for Canada’s transition to a greener economy.

Key findings

  • Canada will need to build a projected 85 SMRs at a cost of $102 billion to $226 billion to reach our net-zero emissions target by 2050.
  • SMRs could help power electrical grids, while their size and flexibility would allow them to replace fossil fuels in specific industrial processes and other off-grid settings.
  • To ensure the country has the expertise to support the growth of an SMR industry, Canada will need more than 5000 full-time, skilled workers on average between 2025 and 2040.
  • Indigenous partnerships and expertise will be a critical for the development of Canada’s SMR industry and its supply chains, from uranium mining to component manufacturing and eventually to new projects in areas on or near traditional Indigenous lands.
  • With no uranium-enrichment facilities of its own, Canada will need to work with allied nations such as the U.S. and France to secure stable supplies of enriched nuclear fuel to deploy its SMR fleet.

What is an SMR?

Nuclear energy has been used to produce carbon-free electricity since the 1950s, providing stability and diversity to national power grids. In addition to large-scale plants, small, bespoke nuclear reactors have been used to power submarines, aircraft carriers and planetary spacecraft. Some small reactors have been installed inconspicuously for research in national laboratories or university campuses, like McMaster University in Hamilton6 and the Royal Military College of Canada in Kingston7.
SMRs were conceived to address conventional nuclear’s long construction timelines and escalating costs by leveraging some key attributes of small reactors. SMRs are like conventional nuclear fission reactors, but are designed to be built in factories, and assembled on-site to exploit economies of scale through multiple units to reduce costs. They could also include enhanced safety systems, digitalization, and streamlined operations. They are typically defined as reactors that have at most 300 megawatts of capacity, which would make them about a third the size of a conventional nuclear plant, and can be as small as 5MW8. Not all SMRs meet the 300MW criterion — and not all reactors smaller than 300MW are SMRs. Companies in Britain, for instance, are developing SMRs rated at 470MW capacity9, and India’s nuclear reactor fleet includes several reactors rated at 220MW that are not considered SMRs10. Climate change has renewed interest in the nuclear industry, particularly SMRs. While there are an estimated 98 SMR designs around the world in various stages of development, only Russia and China are currently operating commercial SMRs. The majority of SMRs remain in the design phase. The U.S. has the most SMR designs under development, followed by Russia, China, Japan and Canada. Denmark, with no native nuclear power, is also pursuing the technology with a floating SMR design11.

SMR designs are being advanced by companies worldwide

Count of SMR designs in development

Source: World Nuclear Association, RBC Climate Action Institute

Although a handful of private players are working to commercialize SMRs, government support is key for the technology to scale. In the U.S., the Department of Energy and private companies have jointly invested over $1 billion in SMR development12. The Tennessee Valley Authority (TVA), the largest U.S. public utility, has thrown its weight behind SMR technology. As early as 2019, it obtained federal approval for SMRs at its Clinch River Nuclear site13. In November 2020, Britain announced a £215 million spending package to be matched by private investment14. In 2022, Canada announced $29.6 million for research and supply chain frameworks, $70 million for research on minimizing SMR waste, and $51 million for the Canadian Nuclear Safety Commission to build regulatory capacity for SMRs15,16. In the same year, the Canada Infrastructure Bank provided $970 million in funding for the Darlington SMR17. New Brunswick invested $10 million in 2018 to establish a research cluster for SMRs18, and another $80 million in total in two advanced SMR companies19. Saskatchewan invested $80 million in a micro-SMR project in 202320. To remain in the forefront of the potential SMR revolution, Canada will need to continue to refine the ways it finances and regulates the development and commercialization of the reactors.

A strategic moment for Canada

SMRs could be a significant part of Canada’s future energy mix. How big a share depends in part on how quickly SMRs can be developed and deployed. Given the current technological outlook at least, SMRs have several advantages compared to the other main energy sources.
Darlington Nuclear Generating Station
Hydroelectric projects have been a mainstay of the Canadian energy landscape, but big projects are not possible or viable in many parts of the country, their massive expense, land impact, and the lack of new, quality resources make the case for new dams challenging. Prolonged droughts may challenge their reliability. Renewables such as wind and solar provide relatively inexpensive electricity compared to nuclear options. But that power is intermittent, dependent on when the sun shines and the wind blows, which means renewables generally need to be backstopped by expensive batteries or emissions-intensive natural gas. Natural gas plants retrofitted or built with carbon capture and sequestration (CCS) could provide relatively clean and reliable power. But on the drive to net zero, they will largely be limited to geographies where emissions can be captured and stored underground (mostly Western Canada), in a process that often comes with a hefty price tag and uncertainties in economics and commercialization potential. Nuclear energy, to reach its potential, must overcome a track record that has included cost overruns, long project timelines, and low social acceptance in parts of the country such as British Columbia and Nova Scotia. There also continue to be concerns around nuclear safety and waste management. Nuclear is the world’s second-highest source of zero-emissions power after hydroelectric dams but its share of global electricity production has dropped from 17% in the 1990s to 9% today (with natural gas, coal and renewables filling the gap21.)

SMRs will be the 5th largest source of power in a net-zero Canada

Installed capacity, MW

Source: Canada Energy Regulator, RBC Climate Action Institute

SMRs, if commercialized, could accelerate nuclear project timelines, lower costs, and bring nuclear to geographies with grids too small to accommodate large power plants. Under a net-zero scenario from the federal Canada Energy Regulator, the country will need 25 gigawatts of SMR capacity—equivalent to about 85 grid-scale SMRs—by 2050, which would provide 7% of Canada’s power capacity. Under that scenario, onshore wind would account for 30% of the total, hydro 26%, utility-scale solar 10%, abated natural gas 7% and large nuclear 3%22. By leveraging SMRs as a source of non-emitting power, Canada could save 41 megatons of emissions, on average, annually between 2030 and 2050 relative to unabated natural gas generation23.

SMR applications

Grid-scale power generation Canada’s electricity supply is one of the world’s greenest, with 81% of its generation fed by hydro, nuclear, and wind and solar power24. But there is no easy solution that would decarbonize the 19% of Canada’s grid that still relies on fossil fuels.
Successful deployment of SMRs would unlock a new source of carbon-free power for Canada’s electrical grids. SMRs scalability make them suitable for grids of varying sizes and location. And with technological, social, and commercialization issues currently limiting growth of other energy options in Canada, SMRs are expected to be competitive with other sources of power on a cost-of-generation basis25.
Industrial processes Reducing the 75 megatons of CO2 equivalent emitted annually from Canada’s industrial sector26 is a net-zero imperative. SMRs can help Canadian industries decarbonize by providing uninterrupted, non-emitting electricity and heat to commodity producers. In the longer term, SMRs could be used to produce low-emissions hydrogen and synthetic fuels that may aid in the carbon-intensive steel, cement and petrochemical industries.
The SMRs could be used at individual sites for specific applications — like the chemicals and pulp and paper sectors to create steam currently produced by burning natural gas. These applications would provide a competitive edge to Canadian companies whose customers need lower-carbon materials. But deploying SMRs will be difficult in certain industrial processes given existing technologies. Steelmaking in blast furnaces and cement manufacturing require temperatures at or above 1,000 Celsius, which current SMR designs would not be able to produce27.
Mining The mining sector produces 2% of national emissions28, but has made steady progress on decarbonization. For instance, nickel miners are converting their mine vehicle fleets to electric29 and pursuing projects that use tailings to capture CO2 30.
SMRs may be able to push many other mining operations closer to zero emissions—particularly if the sites are beyond the reach of electricity transmission infrastructure—by displacing diesel generators and providing electric power for mine vehicles. But complexity varies and some mines will be more challenging to decarbonize. Canada’s largest and heaviest carbon-emitting mines are the massive iron ore operations in Newfoundland and Labrador, Quebec and Nunavut. These operations will continue to rely on fossil fuels in the near-term because there are no alternatives at present that can produce the high temperatures (at least 1,300 C) they need to process ore31.
Oil sands Decarbonizing this carbon-intensive sector is arguably Canada’s greatest climate challenge. Oil sands extraction is responsible for 12% of national emissions32, and consumes 30% of the Canada’s natural gas output33, which it burns in boilers to produce steam for in-situ production techniques.
If SMRs can be commercialized, they will be a strong contender to lower emissions in the oil patch. By producing high quality, high temperature steam, SMRs can replace natural gas boilers at in-situ oil sands facilities, cutting off emissions at their source. Unlike carbon-capture technologies, SMRs would not require further infrastructure such as CO2 pipelines and underground storage downstream. By deploying a large SMR to the highest emitting facilities, oil sands producers could theoretically displace natural gas emissions at a capital cost of $1.6 billion to $2.6 billion. For smaller facilities, six or seven micro-SMRs may be able to abate emissions at a capital cost of $300 million to $700 million34.

The path ahead: What Canada needs to go big on SMRs

Large nuclear power plants have a track record of going over budget during construction. Capital costs for large-scale nuclear plants in the U.S., France, Canada and Germany have escalated 60% to 200% since the 1970s35, and some recent projects exceeded their budgets by billions of dollars.36

SMRs could eventually reverse that trend—at least on paper. Lower design complexity, better safety features that may streamline regulation, and potential modular manufacturing and on-site assembly are all features that advocates say will help them overcome the industry’s cost problems. If SMRs can be built on time and on budget, they may be cost competitive with other sources of low- or non-emitting energy.

The SMR record is still nascent, and therefore difficult for capital markets to assess. There are only two SMRs operating commercially, one in Russia, the other in China; both saw cost escalations and project timeline delays37. An SMR in Argentina has been under construction since 2014. With only a handful of projects in advanced development around the world, it is unclear whether SMRs will achieve economies of scale and lower their costs in the near-term.

Building the 85 SMRs that Canada needs to reach our net-zero climate targets will cost a projected $102 billion to $226 billion38. Because of nuclear’s long lead times, that spending will have to begin soon. Under one net zero forward trajectory, Canada’s power sector will need 93% of Canada’s SMR capacity to be built before 204039. Capital spending to support that rapid growth in the 2030s will need to reach an average of $9 billion to $20 billion annually40.

Canada already has one advantage in place. The federal clean technology investment tax credit could offset 30% of the capital costs for SMRs. Based on current projections, the credits would lower the cost of electricity from SMRs by 24% while boosting their competitiveness41.

Ways forward: Federal and provincial governments can draw in private capital with their current and proposed suite of fiscal incentives to de-risk project finance. The Canada Infrastructure Bank could also help spur early, grid-scale SMR deployment.

In building a new fleet of SMRs to generate clean power, Canada can plan the newest phase of its energy transition in concert with Indigenous communities at all stages of the SMR value chain from uranium mining through to project development and operation, and eventually spent fuel management.

Early signs have been encouraging. Indigenous groups are already seeking opportunities in Canada’s SMR buildout, and government funding has helped establish bodies such as the Indigenous Advisory Council to provide a unified national voice for Indigenous communities around SMRs42. In New Brunswick, the North Shore Mi’kmaq Tribal Council and its seven First Nation member communities signed equity agreements last year with Moltex Energy Canada and ARC Clean Technology Canada to develop and deploy advanced SMR technology. In Saskatchewan, three Indigenous-owned companies partnered in 2021 to jointly invest and build businesses to service SMR markets44.

Ways forward: The sector can maintain early momentum with Indigenous community engagement and capacity-building. As micro-SMR technologies advance, technology vendors, project developers and end-users can further prioritize engagement and knowledge-building in remote areas, where micro-SMRs may best be deployed.

Building out a successful national SMR industry could create a substantial export opportunity for a new generation of Canadian nuclear. Key areas of opportunity include licensing the GE-Hitachi BWRX-300 design, scheduled to be built at the Darlington nuclear plant. Provincial crown corporation Ontario Power Generation, the Tennessee Valley Authority electric utility and the Polish company Synthos Green Energy invested $400 million to bring the BWRX-300 design to completion45. Should this design scale, OPG would share technology licensing revenues from future BWRX-300 projects.

Canadian project management expertise will also be in demand. The emergence of a successful SMR industry could create a $3 billion to $10 billion annual opportunity for Canadian expertise by 2040 in pre-construction (e.g., land acquisition, environmental studies, permitting), and indirect services (e.g., engineering, project management, quality assurance, testing, and commissioning)46.

Export opportunities could extend to other parts of the SMR industry, such as uranium supply and conversion. Canada is the world’s second-largest uranium miner, after Kazakhstan—producing 15% of global uranium supply47. A tripling of global nuclear capacity by 2050, as projected at the COP28 UN Climate Change Conference in Dubai, would create significant opportunities for Canada’s uranium mining industry.

Uranium conversion—the processes that transform raw uranium ore to fuel- or enrichment-ready products—is another area of opportunity. Canada controls 28% of the world’s operating uranium conversion capacity, which is less than Russia (38%), but ahead of China (25%) and France (8%)48.

Ways forward: Canada can add to existing strengths by streamlining permitting for new uranium mines and expanding cooperation with allied countries to supply uranium conversion services. It can also build early relationships with foreign partners, especially countries with limited nuclear experience, by sharing expertise in community engagement, technology, and building societal acceptance for nuclear.

To streamline the introduction of SMRs, the private sector and the federal and provincial governments will have to overcome negative perceptions about nuclear energy. They will also face government restrictions in certain provinces: B.C. has a long-standing ban on nuclear power generation49, and Nova Scotia has only recently reopened the possibility of nuclear power generation in the province50.

Polls indicate Canadian societal attitudes to nuclear power are changing. Between 2012 and 2023, Canadian public support for nuclear power increased from 37% to 55%, with 62% now viewing it as essential to Canada’s net-zero strategy. A majority of the public in Ontario, Saskatchewan, and Alberta supports nuclear power, as do pluralities in Manitoba and the Atlantic provinces.

Public opinion polls indicate Canadians who may oppose a nuclear project deemed beneficial if it was built close to where they live are increasingly in the minority. Surveys that attempt to capture public concerns about the selection of new plants and nuclear waste management sites have indicated local opposition to new projects—including nuclear—peaked in 2011 and have been in decline ever since.

Other challenges persist. In 2022, 60% of Canadians said they had never heard of SMRs and another 25% said they were only vaguely aware of them. Skeptics were not convinced by the information about SMRs’ smaller footprint, affordability and enhanced safety, but were open to learning more51.

Canada will need a rapid revitalization of its nuclear workforce to support growth of the SMR industry in the coming decades. At least a third of the country’s nuclear professionals were approaching a retirement age in 2019. Ensuring that the country has the nuclear-critical skills it needs will be key, as 4,000 professionals across all trades are set to retire by 2025.

Canada needs a new workforce to build and operate its SMR fleet

Number of Workers

Source: Conference Board of Canada, NB Power, RBC Climate Action Institute

Building and operating the near-term SMR fleet in Ontario, Saskatchewan and New Brunswick, and Alberta will require an average of 5,300 workers between now and 2040, and about 2,400 to operate and maintain the fleet thereafter. To service domestic and international demand, associated sectors like uranium mining and processing will need to grow their workforces as well.

Ways forward: Canada could follow the example of Britain, which in partnership with several industry players has committed £763 million to revitalize the country’s defense and civil nuclear sector, aiming to fill over 40,000 new jobs expected by the end of this decade, and augment apprenticeship programs and advanced studies52.

Because its CANDU reactor fleet runs on natural uranium, and an international treaty prevents the country from enriching uranium at home, Canada has not developed domestic uranium enrichment capacity53. Canada will need to look beyond its borders for enriched uranium to run a future nuclear fleet that will almost certainly need the fuel. The amount it requires will depend on what designs get developed, both in terms of SMRs and large nuclear power plants.

All but one of the SMR designs being commercialized in Canada today require uranium to be enriched to different degrees. Canada’s earliest SMRs will be fueled by Low Enriched Uranium (LEU), which will initially be sourced from France and the U.S54. More advanced designs will need High-Assay Low Enriched Uranium (HALEU).

Uranium enrichment is geographically concentrated. As of 2022, Russia controlled 40% of the world’s enrichment capacity55, and it is the only commercial producer of HALEU. Issues over accessing HALEU have already disrupted SMR projects in the U.S. As nuclear’s resurgence stagnant enrichment capacity, following years of oversupply and underinvestment, enriched uranium could become bottlenecked in the future. Addressing that bottleneck could become critical.

Ways forward: Canada will need to advance cooperation with allies to strengthen global enriched uranium supply chains and secure supplies of LEU and HALEU. Canada can turn to its partnership with other nations in the newly formed “Sapporo 5” (Japan, the U.S., Britain. and France) to invest in an international uranium enrichment centre and strategic enriched uranium stockpile.

Spent nuclear fuel in Canada currently comes from the country’s CANDU reactor fleet and has been safely managed since the first commercial reactors began operating about five decades ago. As Canada commercializes SMR designs, new types of spent nuclear fuel will require long-term management. The physical properties, quantities and management protocols around spent fuel will vary significantly between different SMR designs. In some cases, spent fuel will be of a kind that is well understood and for which management protocols exist internationally. For others, new waste-management protocols will need to be developed.

Ways forward: SMR vendors will need to continue to invest in research and development on advanced fuels, and closely coordinate their work with the Nuclear Waste Management Organization, to advance designs for managing fuel. That will include specific engineering solutions for managing SMR fuel and its eventual containment and isolation in a Deep Geological Repository, to contain spent fuel in perpetuity. Canada is progressing towards selecting a site for a DGR.

SMRs could help decarbonize and expand electricity grids servicing large and small population centers and provide energy to beachhead industrial markets. But as electricity demand grows, traditional large nuclear power plants must continue to play a role. Proven conventional nuclear technologies, such as Canada’s home-grown CANDU reactor and potential alternative technologies from abroad, are well placed to provide additional non-emitting capacity.

With the exception of the Point Lepreau reactor in New Brunswick, Canada’s nuclear fleet is concentrated in Ontario. With the successful refurbishments of two units in Darlington almost half a year ahead of schedule, and commitments for additional refurbishments at the Pickering Nuclear Generating Station, Canada is set to keep the fleet running for at least another 30 years56. But translating this experience into new nuclear capacity will be essential if we are to reach its climate goals while maintaining secure energy supplies.
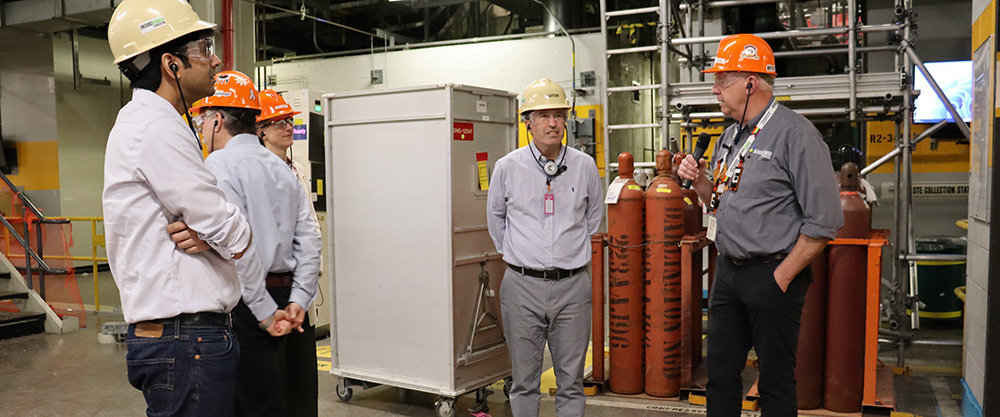
Ways forward: Utilities can begin long lead-time activities like the identification and assessment of potential sites for new large nuclear power plants and initiate early discussions around community engagement, permitting, and transmission planning, especially for areas that are not currently licensed for new nuclear buildout.

Preparing for the age of small

Canada has been a global leader in the peaceful use of nuclear energy for over 75 years. Early research at labs in Montreal and Chalk River helped lead to breakthroughs in the industry and development of the safe and versatile CANDU reactor technology, which has been used across eastern Canada and exported to six other countries. The Pickering, Bruce and Darlington nuclear generating stations have been strategic drivers through the 1990s, producing important supply chains in Ontario and employing tens of thousands of skilled workers. While fiscal tightening and global nuclear-safety fears arrested the industry’s growth in the 1980s and 1990s, decisions to reinvest in Bruce and Darlington have since brought the sector new life. The promise of SMRs now presents Canada with new choices about our nuclear future. If SMRs can be developed and commercialized quickly and cost-effectively, they can help Canada meet growing demand for electricity and its commitment to reach Net Zero by 2050. But we will need to move faster. For Canada to achieve Net Zero emissions by 2050, 93% of SMR capacity must come online in the 2030s, more than twice as fast as Canada achieved its conventional nuclear capacity buildout between the 1970s and 1990s57. The good news is that Canada is taking an early lead in deploying SMRs. The GE-Hitachi BWRX-300 prototype is nearing construction at Darlington, while other SMRs are in various stages of licensing. Success could unlock a new source of energy for non-emitting baseload power for Canada’s grids, and off-grid power for remote locations. Success will also position Canada to be an important exporter of SMR components and expertise. Canada will need to be nimble. Nuclear power is by far our most complicated source of electricity. And the commercialization of advanced approaches to nuclear, through SMRs, will require a diverse mix of capital, skills, fuel supplies and public policy. That, in turn, will require a coordinated national approach to make this potentially transformative technology a key part of our energy future.

Related Reading

Canada’s Energy Transformation:

An Outlook of Supply and Demand In the 2030s

SMRs:

World’s new Net Zero darling

Power Shift:

How Ontario Can Cut Its $450-Billion Electricity Bill

For more, go to rbc.com/climate.

Download the Report

Download

Contributors:

Lead author: Vivan Sorab, Senior Manager, Clean Technology

Steven Frank, Contributing editor

Caprice Biasoni, Graphic Design Specialist

  • Ben Alex, Hatch
  • David Dal Bello, RBC Capital Markets
  • Philip Chaffee, Energy Intelligence
  • George Christidis, Canadian Nuclear Association
  • Lance Clarke, ARC Clean Technology
  • Chris Deschenes, Ontario Power Generation
  • Sara Dolatshahi, Nuclear Waste Management Organization
  • John Gorman, Canadian Nuclear Association
  • Frances Hilderman, Hatch
  • Daniel Jurijew, Capital Power
  • Dr. Chris Keefer, Canadians for Nuclear Energy
  • Neal Kelly, Ontario Power Generation
  • Chuck Lamers, Ontario Power Generation
  • Kim Lauritsen, Ontario Power Generation
  • Carlos Leipner-Gomes, LGE Strategic Advisors (Leipner Global Enterprises LLC)
  • Michelle Leslie, Deloitte
  • Matthew Mairinger, North American Young Generation in Nuclear
  • Jon-Michael Murray, Terra Praxis
  • Matthew Naraine, Canadian Nuclear Safety Commission
  • Chad Richards, Nuclear Innovation Institute
  • Adam Schatzker, Canada Nickel Company
  • Brad Sigurdsson, Saskatchewan Mining Association
  • Mathias Trojer, Prodigy Clean Energy
  • James Wolf, ARC Clean Technology
  • Andrew Wong, RBC Capital Markets

  1. Natural Resources Canada: Canada Outlines Next Steps for Progress on Small Modular Reactor Technology
  2. Natural Resources Canada: COP28: Declaration to Triple Nuclear Energy (2023
  3. Ontario Power Generation: OPG working to deploy SMR fleet to help power Ontario’s clean energy future
  4. Natural Resources Canada: Canadian SMR Roadmap
  5. Canada’s Small Modular Reactor (SMR) Action Plan
  6. McMaster University: McMaster Nuclear Reactor
  7. Nuclear facility – Royal Military College of Canada SLOWPOKE-2 research reactor
  8. World Nuclear Association: Small Nuclear Power Reactors
  9. Rolls-Royce Small Modular Reactors
  10. Chemical and Engineering News: Can small modular reactors at chemical plants save nuclear energy?
  11. The NEA Small Modular Reactor Dashboard: Second Edition
  12. World Nuclear Association: Small Nuclear Power Reactors
  13. Tennessee Valley Authority: Advanced Nuclear Solutions
  14. UK Research and Innovation: UK government invests £215 million into small nuclear reactors
  15. Natural Resources Canada: Canada Launches New Small Modular Reactor Funding Program
  16. Osler: Canada announces funding program to enable deployment of small modular reactors
  17. Canada Infrastructure Bank: CIB commits $970 million towards Canada’s first Small Modular Reactor
  18. University of New Brunswick: UNB researchers are exploring how to power the future with small modular reactors
  19. CBC: 7 First Nations in N.B invest in small modular nuclear reactors
  20. Government of Saskatchewan Funds Microreactor Research
  21. Energy Institute: Statistical Review of World Energy 2023
  22. Canada Energy Regulator: Canada’s Energy Future
  23. RBC Climate Action Institute Analysis
  24. Canada Energy Regulator: Canada’s Energy Future
  25. RBC Climate Action Institute Analysis
  26. Canadian Climate Institute: Early Estimate Of National Emissions
  27. Nuclear Energy Agency: The NEA Small Modular Reactor Dashboard: Second Edition
  28. Canadian Climate Institute: Early Estimate Of National Emissions
  29. Electric Autonomy Canada: Vehicle orders bring Glencore’s all-electric Onaping Depth mine a step closer to fruition
  30. Canada Nickel: Canada Nickel Announces Carbon Storage Testing Results Better than Anticipated; Integrated Feasibility Study Expected in September
  31. RBC Climate Action Institute Analysis
  32. Canadian Climate Institute: Early Estimate Of National Emissions
  33. Canada Energy Regulator: Oil sands use of natural gas for production decreases considerably in early 2020
  34. RBC Climate Action Institute Analysis
  35. Lovering et al. (2016): Historical construction costs of global nuclear power reactors
  36. US Energy Information Administration: First new U.S. nuclear reactor since 2016 is now in operation
  37. POWER: A Closer Look at Two Operational Small Modular Reactor Designs
  38. RBC Climate Action Institute Analysis
  39. Canada’s Energy Future 2023: Energy Supply and Demand Projections to 2050
  40. RBC Climate Action Institute Analysis
  41. ibid
  42. Natural Resources Canada: Canada Supports Indigenous Advisory Council for SMR Action Plan
  43. CBC: 7 First Nations in N.B invest in small modular nuclear reactors
  44. First Nations Major Project Coalition: Primer on Nuclear Energy, SMRs and First Nations
  45. GE Vernova: Tennessee Valley Authority, Ontario Power Generation and Synthos Green Energy Invest in Development of GE Hitachi Small Modular Reactor Technology
  46. RBC Climate Action Institute analysis.
  47. World Nuclear Association: World Uranium Mining Production
  48. World Nuclear Association: Conversion and Deconversion
  49. BC Laws: Clean Energy Act
  50. Nova Scotia Legislature: Energy Reform (2024) Act
  51. Environics Research and Canadian Nuclear Association: Public Attitudes To Nuclear Power
  52. Reuters: Britain plans to boost nuclear workforce
  53. Fasken: A Nascent Renaissance – Part II: Confronting Nuclear Energy Fuel Supply Chain Challenges
  54. Ontario Power Generation: OPG selects suppliers for first fuel contracts for its Small Modular Reactors
  55. World Nuclear Association: Uranium Enrichment
  56. OPG celebrates green light for Pickering Refurbishment. Here’s what’s next
  57. RBC Climate Action Institute Analysis

rbc_toc_for_mmm_action

Transportation is Canada’s second-highest emitting sector, after oil and gas, and most vehicle emissions come from passenger cars. But for all the buzz and investment around electric vehicles, a significant opportunity for decarbonization can be found in medium- and heavy-duty vehicles (MHDVs). They account for only five per cent of Canada’s vehicle stock, and yet produce 37 per cent of the sector’s GHG emissions1. The opportunity to cut MHDV emissions was the central theme at a recent workshop hosted by the Pembina Institute, a Calgary-based think tank, as part of EV & Charging Expo 2024 in Toronto. Unlike other energy transition conferences, which often dwell on technology and capital needs, the focus here was on implementation and management challenges. That’s because the transition to electrification, even of heavier vehicles, is underway. The technology exists, although still evolving, with clear costs and benefits. The heavy vehicle industry is also taking action. Even drivers are leaning into the transition. One insight shared on the floor captured the mindset shift: once vehicle operators taste the EV experience, free from the noise of loud diesel engines, they prefer the switch. To accelerate the change, industry experts stressed three major themes:
  1. Collaboration: The transition cannot happen in a vacuum.
  2. Data-driven decisions: Data and insights are in the driver’s seat.
  3. Change management: Holistic planning is a necessity.
A synergy between the fleet managers and utilities is becoming crucial as they find themselves intertwined in the quest for decarbonization. Talking kilowatts is uncommon for fleet managers, who traditionally think in kilometers. They face a steep learning curve to choose the right charger and vehicle types. Utilities face a different challenge: they need to expand their infrastructure but are uncertain of the scale and challenged to adjust timelines. Utilities also find themselves trying to understand intricate details of fleet energy needs as they attempt to devise suitable electricity rate options. Effective collaboration will streamline infrastructure development, avoiding unnecessary redundancies while accommodating growing demand. Before even breaking the ground, fleet managers must confront a complex web of decisions. A switch to electric fleets requires precise planning, to avoid cost overruns and supply disruptions. Here, data becomes indispensable, which is a powerful aspect of the transition as electrification entails digitalization. Tools like telematics–vehicle tracking devices–are crucial in harvesting and analyzing data from each trip. Fleet decarbonization often happens one vehicle at a time, and success lies in knowing precisely which vehicle and trip are most suitable for a switch. Layers of considerations are added about when, where and how to charge the vehicles. While some fleet managers are pioneers, having already transitioned their fleets or commissioning pilot projects, others are still assembling a business case. Establishing data-sharing practices can accelerate industry-wide progress and also help utilities to plan ahead. Fleet electrification also blurs the traditional departmental boundaries and necessitates a holistic approach within organizations. It involves everyone from drivers, who must adapt driving habits, to engineers and IT specialists, who need to ensure day-to-day operational continuity, to logistics managers, who will have to rethink entire management systems. Effective change management is pivotal for orchestrating this grand play and ensuring engagement of internal and external stakeholders continues along the way. As shipping, trucking and transportation companies drive deeper into the energy transition, new management thinking may be as important as the engines and energy systems powering a lower-emissions future.

rbc_toc_for_mmm_action

Joanna Osawe is the Founder, President and CEO of Women in Renewable Energy (WiRE). WiRE is a not-for-profit organization whose mission is to advance the role and recognition of women and other under-represented groups working in the energy sector. Inclusive of all renewable energy and clean energy technologies, their programming includes national and international chapters, student chapters, capacity-building field trips, networking meet-ups, awards recognition programs, student bursaries, speed mentoring, speed interviewing, spotlights, conferences, workshops, and more.

RBC Climate Action 2024