

 EN


For the week of November 9nd
Canada’s manufacturing and wholesale sales reports for September next Friday should add to evidence that the economy grew less than expected in Q3.
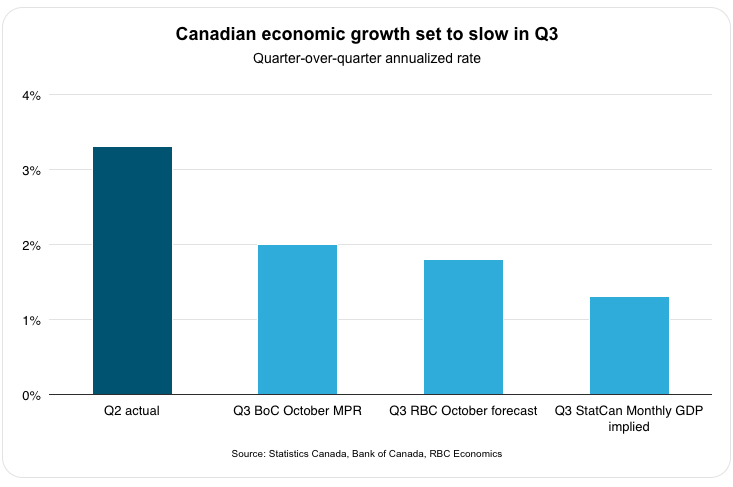
Gross domestic product growth has already flatlined in July and August, and likely contracted by 0.1% in September, according to Statistics Canada’s preliminary estimate. Preliminary GDP estimates have been highly prone to revision and need to be taken with a large grain of salt. Taking the September estimate as is would put annualized GDP growth in Q3 at around 1.3%.
The pace of growth is weaker than both our 1.8% base case forecast and the Bank of Canada’s estimate of 2% in its October Monetary Policy Report. It’s also significantly slower than the 3.3% expansion in Q2, although the slowdown was expected given that part of the Q2 strength reflected a one-time rebound in auto production and exports that won’t be repeated.
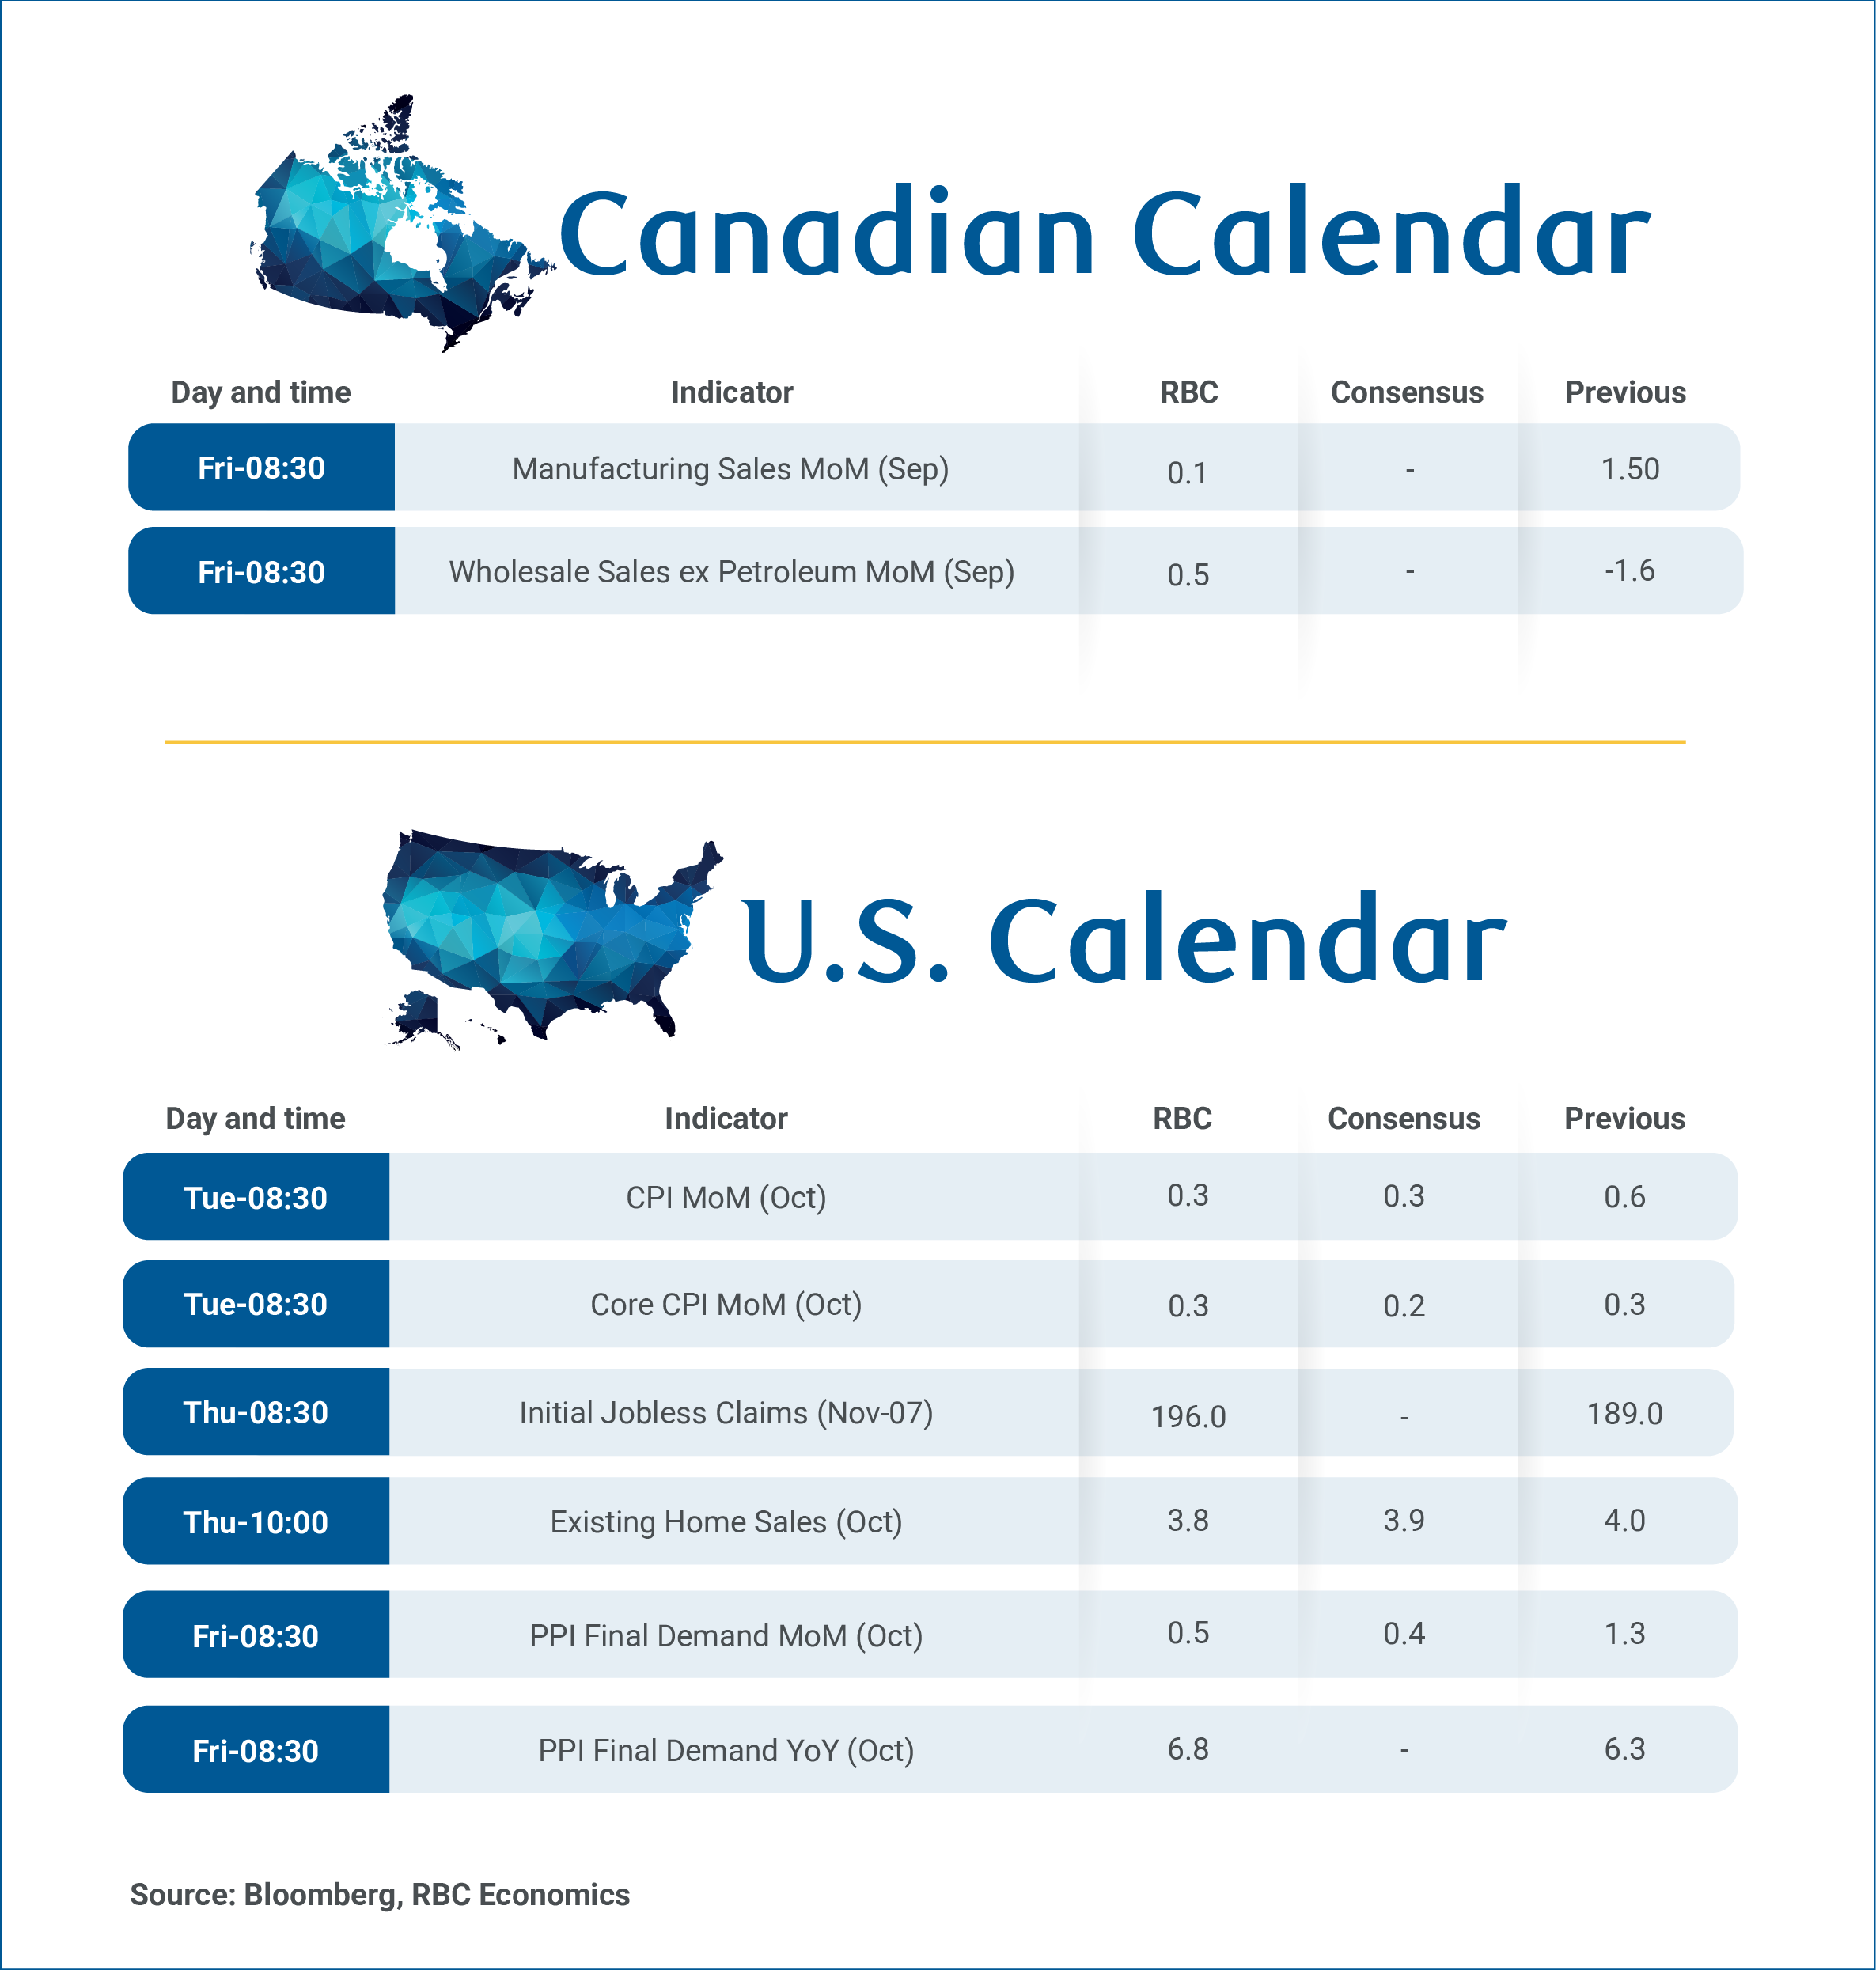
We expect the September manufacturing and wholesale reports will align with a mild contraction in real GDP. The advance estimate suggests nominal manufacturing sales rose 0.1%, which translates to 2% decline in volume once a 2.2% month-over-month increase in manufacturing producer prices is factored in (driven by a 16% increase in petroleum refinery prices).
Part of the pullback may also be related to unplanned production stoppages at U.S. auto plants that led to a sharp decline in cross-border auto trade in September.
Offsetting some of that weakness is an expected 0.5% increase in September’s wholesale sales (advance estimate ex-petroleum), reflecting strength in machinery, equipment, and supplies consistent with stronger imports in recent months.
-
Headline U.S. Consumer Price Index likely rose 0.3% in October from September, supported by another increase in core ex-food and energy components that extends the hotter readings seen in August and September. Gasoline prices changed little in the month but remain well above year-ago levels. Overall, persistent underlying inflation and broadening price pressures support our base case that expects another rate hike from the Fed at their December meeting, following a hike in September and a pause in October.
About the authors:
Claire Fan is a Senior Economist at RBC. She focuses on macroeconomic analysis and is responsible for projecting key indicators including GDP, employment and inflation for Canada and the US.
Annie Zheng is an economist at RBC. She is a member of the macroeconomic analysis group, focusing on macroeconomic modeling.
Explore the latest from RBC Economics:
Canadian Budget 2026: Windfall fuels spending, not savings
Canadian trade surplus widens on prices as new U.S. tariffs set in
The economic pressures shaping the 2026 midterms in five maps
Full steam ahead: US GDP growth accelerates in Q3
Bank of Canada applies preventative medicine: Hikes rates as inflation risks grow
FOMC recap: This is not a 1980s’ hiking cycle
Caribbean Outlook Monitor: Uncertainty is the only certainty
Canadian federal Budget 2026: Looking for disciplined execution
Share these insights with your network:
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

