

 EN


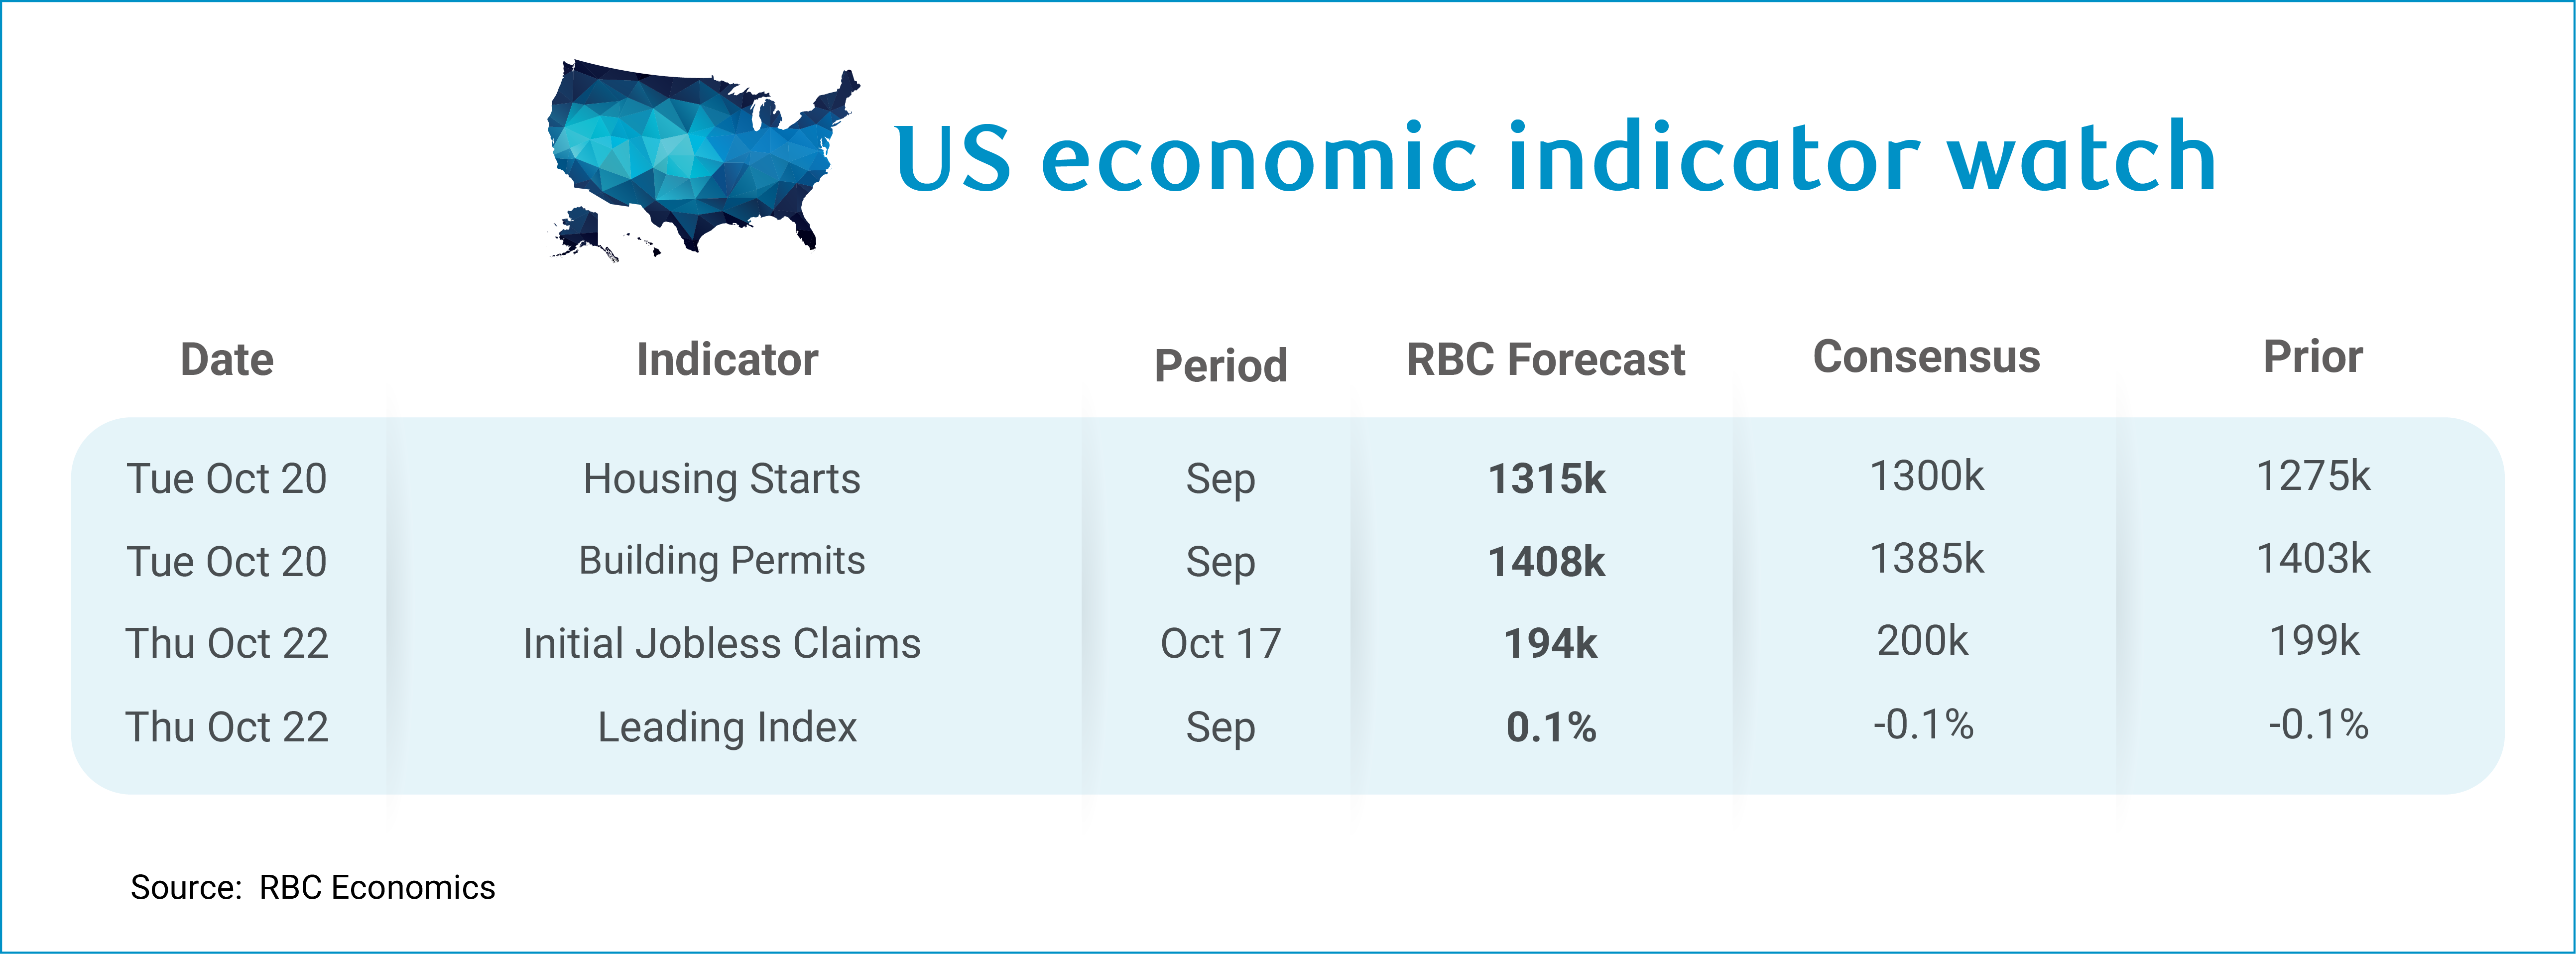
Next week will be quiet on the data front but should give us time to digest the deluge of concerning inflation data that landed this past week. We get housing data on Tuesday, and both building permits and starts are expected to remain weak in the face of high interest rates and elevated input costs. Building permits are expected to move largely sideways at 1408k, and housing starts are set to tick up slightly to 1315k.
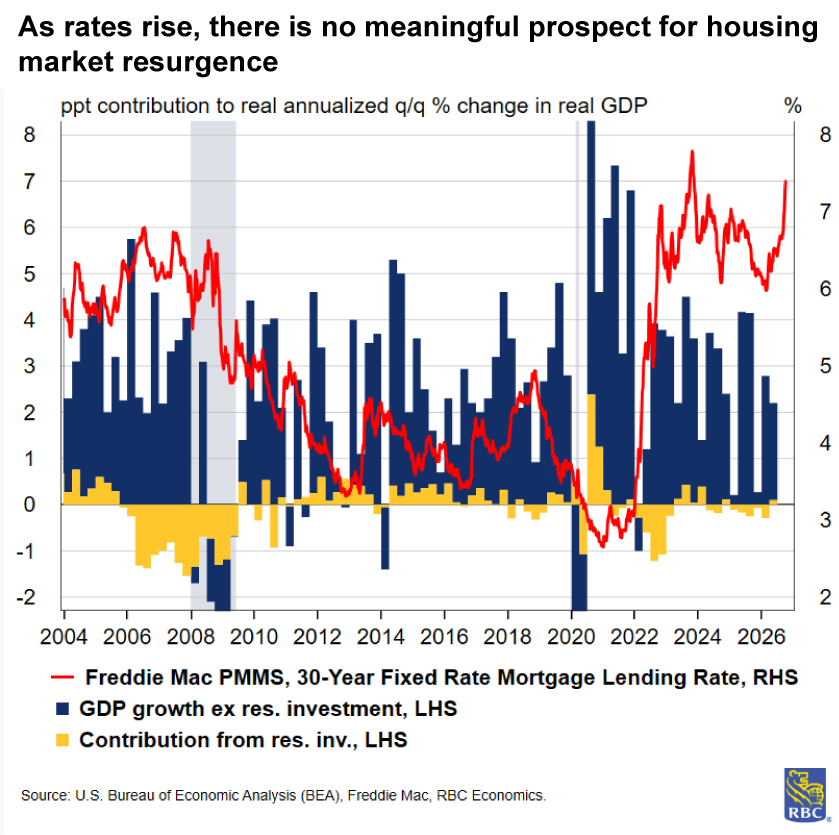
What matters most for the US housing market is affordability and the current rate backdrop is derailing any prospect for improvement. The sector has been stuck in a rut, mostly subtracting from growth since mid-2024, and we continue to expect that drag to persist. US bond yields remain elevated, with 5s and 10s at their highest level since the Financial Crisis and 30-year yields at their highest since 2004. The upside surprise in September CPI points to early signs of an energy-price spillover, and the concern is that the report did not fully capture the risks stemming from both tariffs and higher energy prices. We saw this emerge in the PPI data, which posted the single highest month-over-month increase in four years. More importantly, freight prices — exceedingly elevated — illustrate that more pressure is coming in the pipeline to CPI.
On top of the immediate inflation risks coming from energy and tariffs, we expect limited building activity and higher financing costs to disincentivize builders, weighing on the supply of new homes. Problematically, a supply-constrained housing market can filter back through inflation. Housing is currently contributing 1.1 percentage points (nearly half) to the year-over-year pace of core CPI– and despite higher mortgage rates, home prices have continued to rise – which is not typical. With supply this tight, prices are unlikely to decline, a mechanism that has intuitively worked in the past, meaning we expect sticky housing prices for CPI over the next two years.
About the authors:
Mike Reid is Head of US Economics at RBC. He is responsible for generating RBC’s US economic outlook, providing commentary on macro indicators, and producing written analysis around the economic backdrop.
Carrie Freestone is a Senior US Economist at RBC. She is responsible for generating RBC’s US economic forecasts across GDP, employment, and inflation, and providing macro commentary through publications, presentations, and the media.
Imri Haggin is an US Economist at RBC, where he focuses on thematic research. His prior work has centered on consumer credit dynamics and treasury modeling, with an emphasis on leveraging data to understand behavior.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

