

 EN


Next week, the focus will be on retail sales, which have remained strong despite headwinds from high gas prices. We forecast headline retail sales grew 0.1% m/m in October, reflecting a slowing following the strong September print.
We expect the biggest drag will come from a slowdown in auto sales, which have fallen on a volume basis the past two months. And while gas prices provided some relief in the back half of the month, they remain elevated, keeping stress on low- and middle-income consumers. Resultingly, we have seen some sectors lag inflation since the start of the year, reflecting a volume pullback (recall that retail sales is nominal), including groceries, building and garden supplies, and general merchandise. But many sectors continue to outperform, including health and personal care, restaurants, and nonstore sales, all of which have risen more than double the pace of inflation since January 2026. We view this is evidence of the growing K-shape consumer trends, with the upper K supported by retirees who tend to spend a larger share of their incomes on restaurants and health care.
Stripping out the impact of auto and gas sales and importantly for the control group (a direct input into the GDP estimate for Q4), we forecast stronger growth of 0.3% m/m. This strength reflects the start of the holiday shopping season, which we anticipate will be most obvious in the continued rise of online shopping. Nonstore sales comprise nearly 20% of total retail sales, nearly double the share from just a decade ago. Part of shift is the convenience factor, and the trend was accelerated by the Covid shutdowns in 2020. Still, we remain concerned regarding the transport margins there – online sales require deliveries, which may not fully capture the uptick in gas prices this year. With freight prices continuing to climb for businesses, we suspect this will impact consumer deliveries as well – either directly through increased delivery fees or an increase to annual membership fees in 2027. Either way, it represents another way in which consumers will pay the price for higher gas prices.
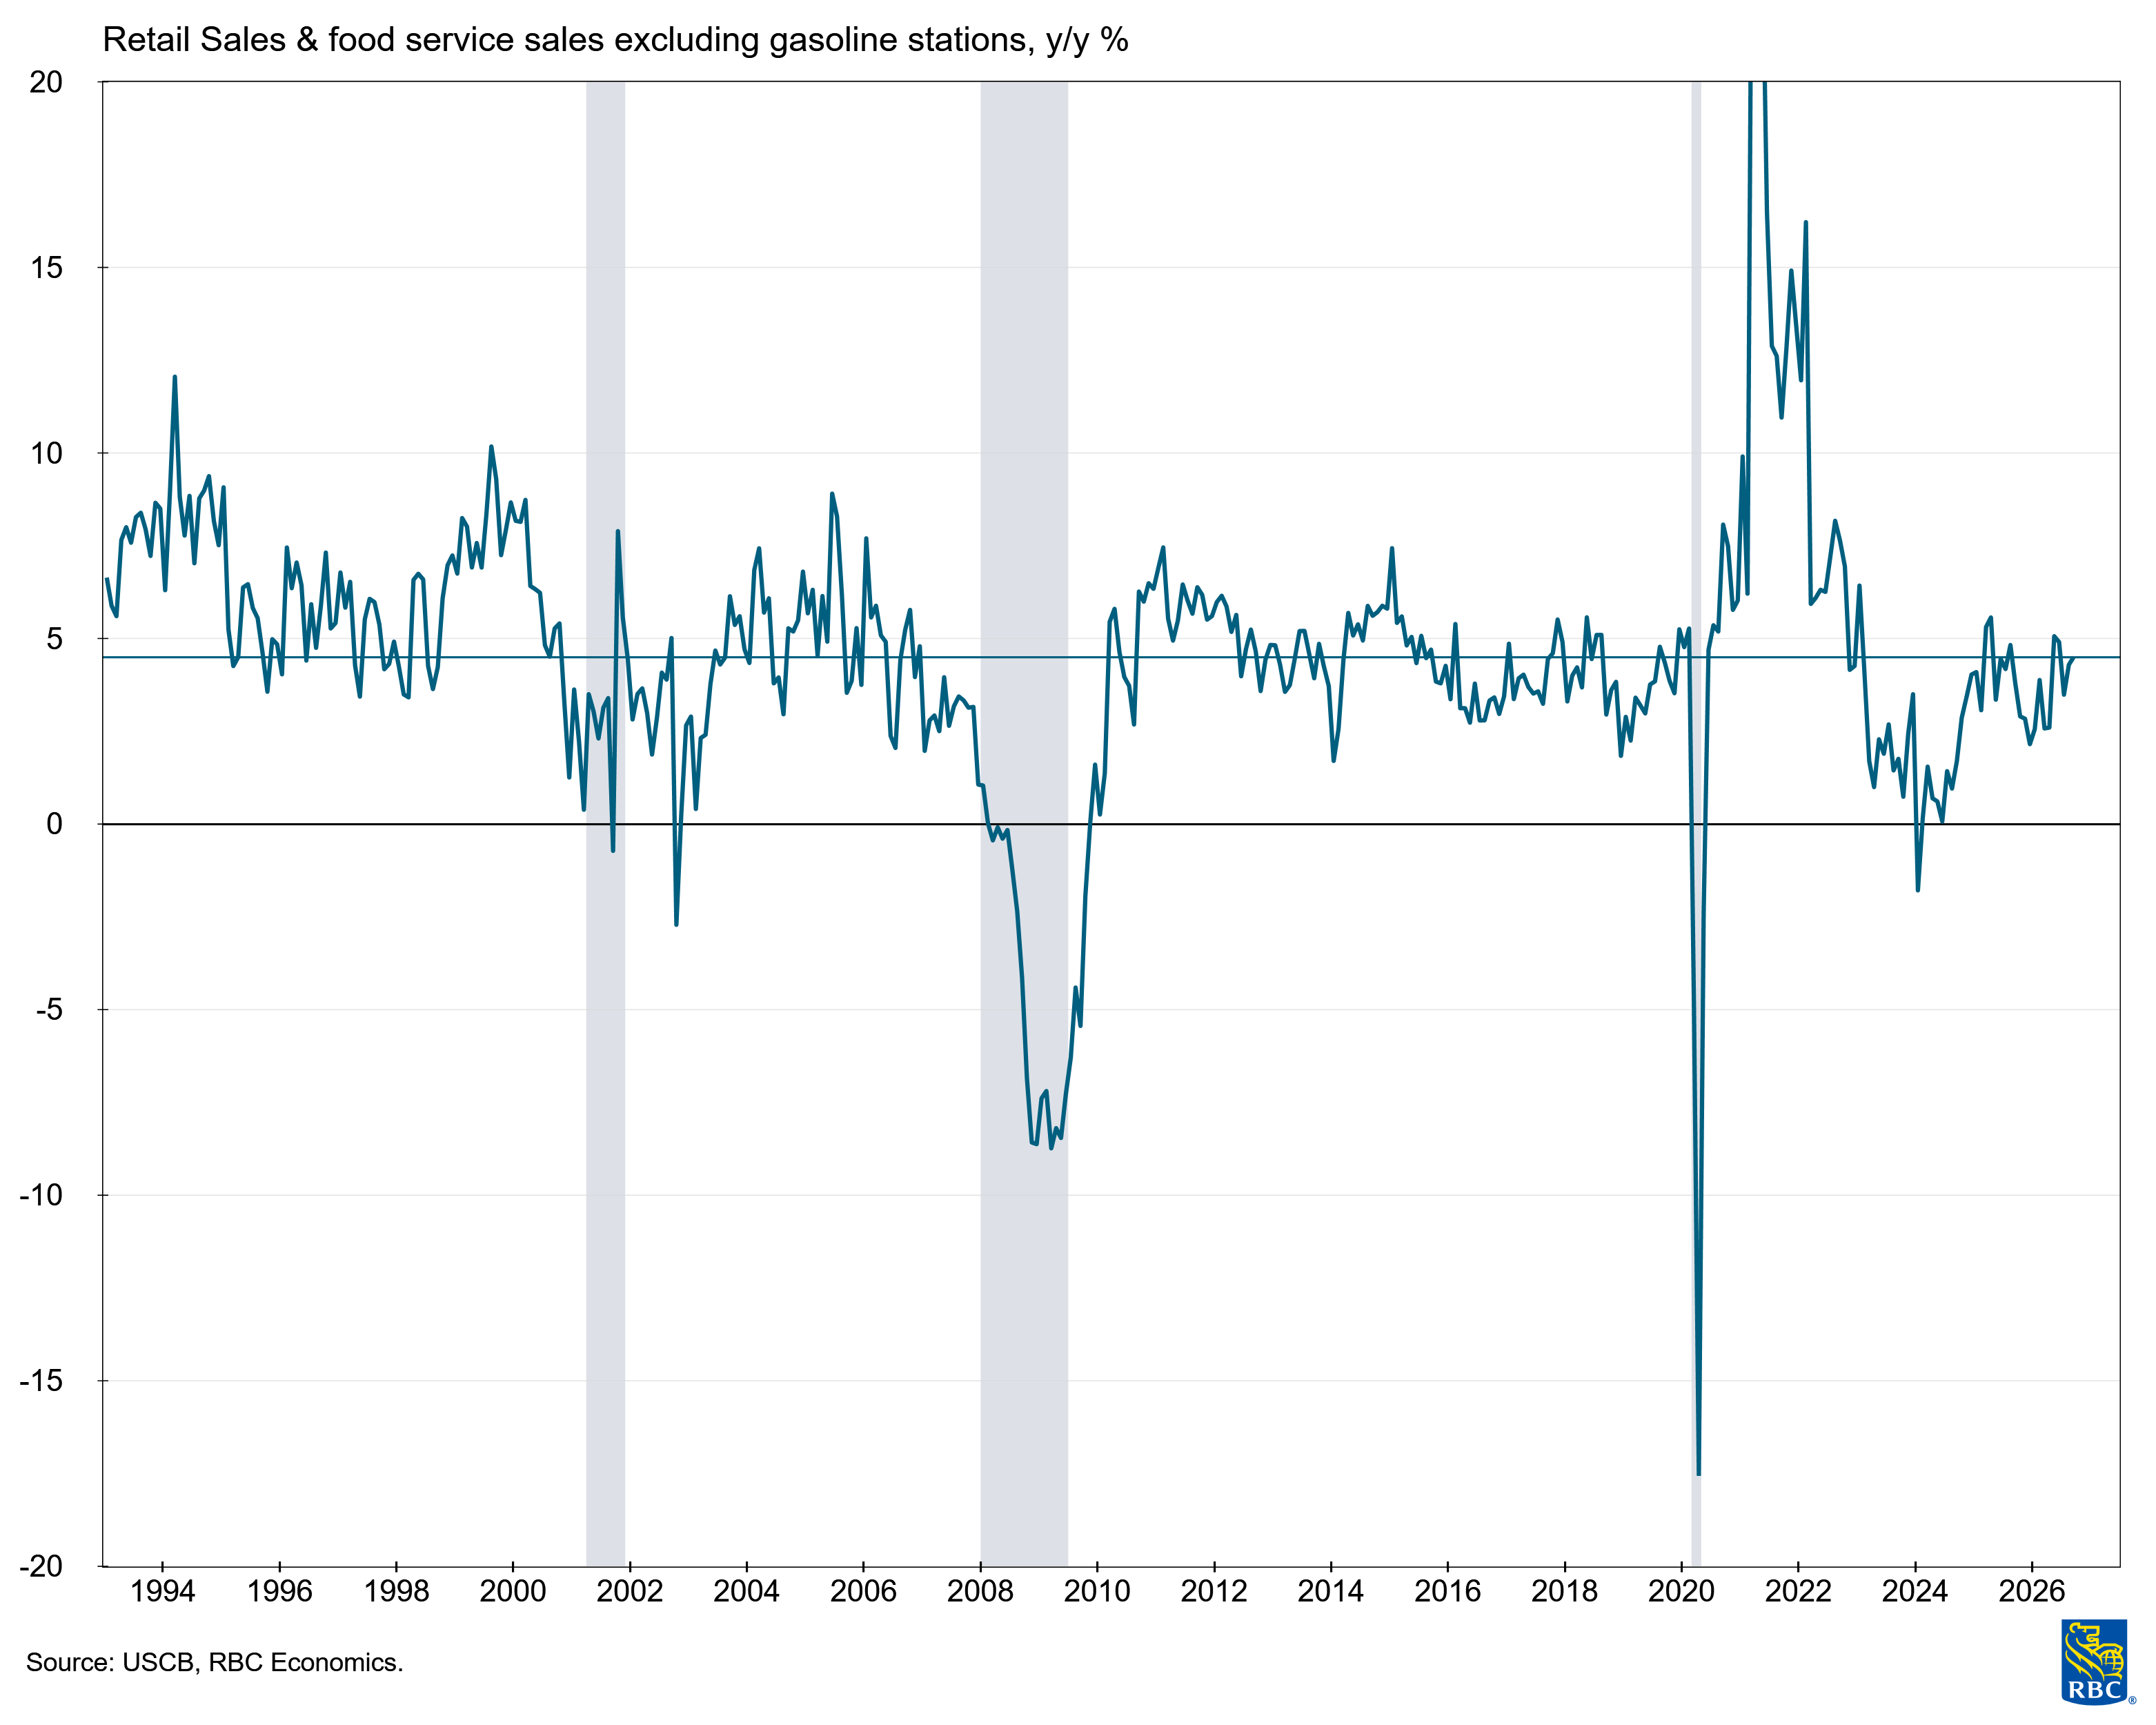
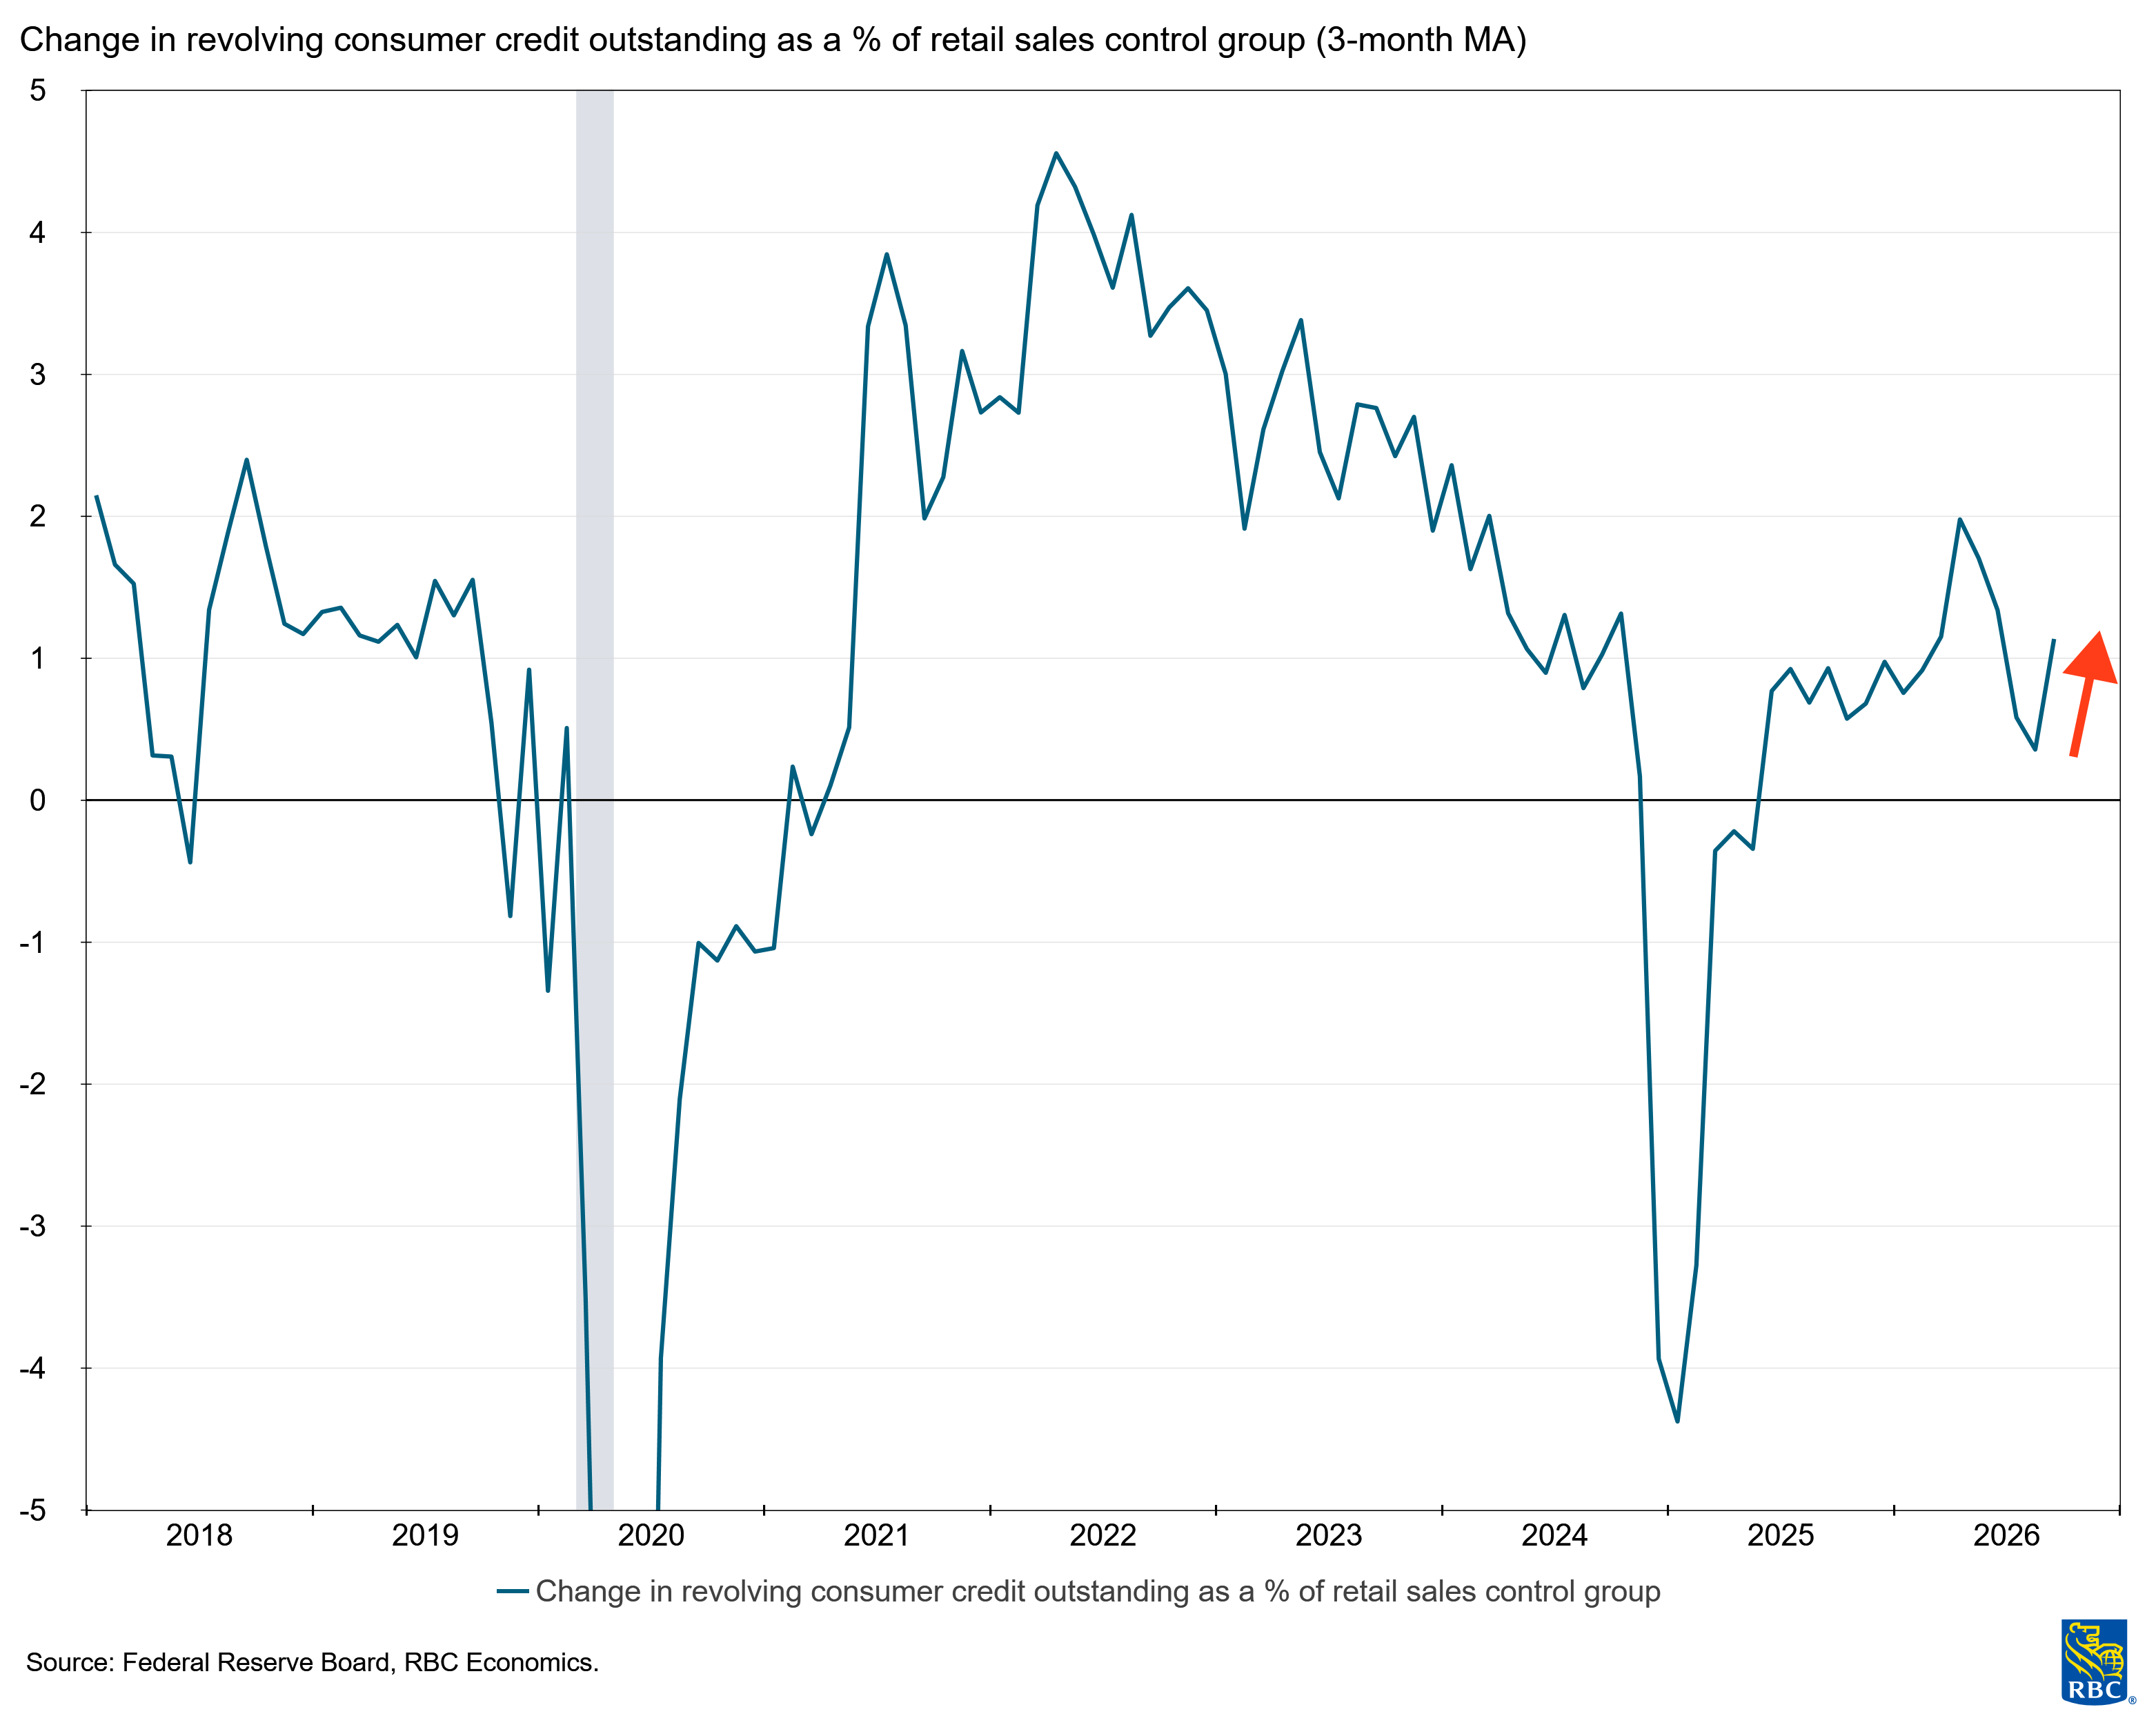
The silver lining is that despite higher gas prices, the current growth rate of retail sales ex-gasoline (4.5A% y/y) is trending near the median seen over the past 30 years. Put another way consumers are maintaining consumption for now, but are at increasing risk of interest rate hikes, as their reliance on credit is on the rise. If the Fed moves towards an every meeting pace of rate hikes, we would expect the lower-K consumers to pull back meaningfully in Q1.
Retail sales ex-gas growing at a health pace
Consumer credit is increasingly supporting retail spending
About the authors:
Mike Reid is Head of US Economics at RBC. He is responsible for generating RBC’s US economic outlook, providing commentary on macro indicators, and producing written analysis around the economic backdrop.
Carrie Freestone is a Senior US Economist at RBC. She is responsible for generating RBC’s US economic forecasts across GDP, employment, and inflation, and providing macro commentary through publications, presentations, and the media.
Imri Haggin is an US Economist at RBC, where he focuses on thematic research. His prior work has centered on consumer credit dynamics and treasury modeling, with an emphasis on leveraging data to understand behavior.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

