RBC Thought Leadership Archives for lavanyakaleeswaran

Disclaimer

rbc_tl_disclaimer

After hosting some of the world’s largest institutional investors in Toronto, Prime Minister Mark Carney jetted off to address the European Parliament, part of his broader effort to build stronger ties outside the U.S. 

  • Since CETA came into force, trade with the EU has boomed, with the total value of trade reaching more $134 billion in 2025. Canada’s exports to the EU grew 23% annually in 2025 to $43 billion, but the country still has a trade deficit with Europe of around $49 billion. 

  • Canada’s top export to the EU is crude oil, followed by gold, vehicles, other petroleum oils and natural gas.  

  • Within the EU, the Netherlands is the top destination for Canadian merchandise goods, with 22% of trade heading to the Dutch, followed by Germany (21%), France (12%), Italy (9%) and Belgium (9%). All other EU countries represented the remaining 26% of trade.  

  • Quebec is the largest exporter to the EU among Canadian provinces and territories, representing a 32% share of the total, followed by Ontario (27%), the Atlantic provinces (17%), Saskatchewan (9%) and Alberta and B.C. (5%).  

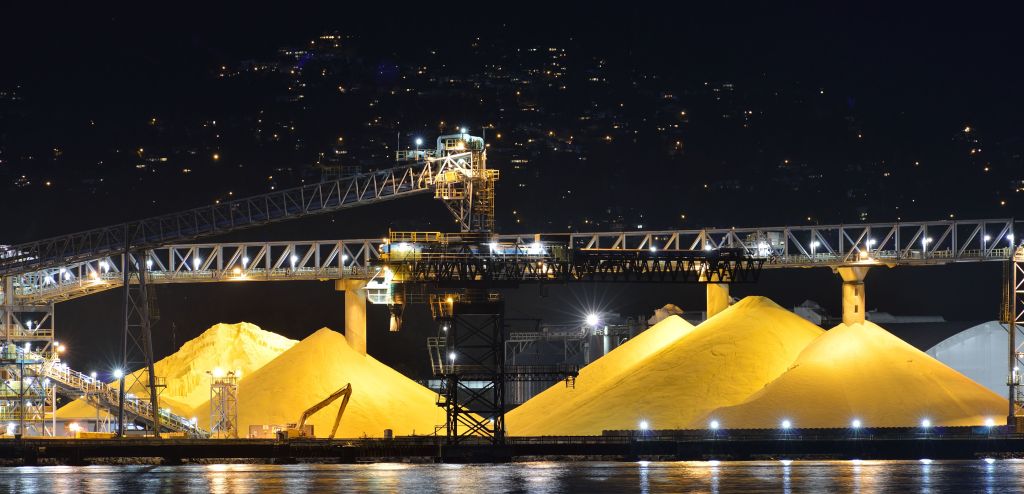
Sulphur prices skyrocketed to record levels in 2026 and remain far above historical norms, putting pressure on fertilizer and crop sectors that need as much as four tonnes of sulphur to make 10 tonnes of finished phosphates, a key fertilizer. 

GMC Trading Group estimates sulphur prices were $874 per metric tonne in June this year, six times the levels seen in 2024.  

Like many commodities, sulphur is being squeezed by shipping disruptions in the Middle East, with alternatives hard to source, supply cannot easily be ramped up to meet demand. Sulphur is largely a byproduct of the oil and gas industry, with Gulf states supplying 50% of globally marine-traded sulphur.  

To shore up its domestic sulphur stocks, China banned exports of sulphuric acid in May, with Russia following suit same on Monday, restricting global supply further.

The squeeze has forced phosphate producers in several regions to curtail production in fertilizer plants, as current sulphur spot prices make operations unprofitable1. If elevated prices continue there could be significantly reduced availability for the key crop nutrient in 2027. 

Canada is a top global sulphur supplier, primarily from oil and gas rich Alberta. Canada exported more than four million tonnes2 in 2025 to over a dozen countries, worth $1.4 billion, up 261% from the previous year3.  

Canada also boasts among the largest sulphur inventories in the world, sitting at around 11 million tonnes. The commodity can be stored cheaply in massive, solid blocks, but moving it requires re-melting and converting to pellets, and transporting long distances with specialized equipment and terminal infrastructure. Exporting costs could add up to more than $150 per tonne, according to Argus4. Capitalizing on the soaring sulphur prices by drawing down on the inventory has therefore been limited, with Alberta’s inventory blocks only changing from 11.4 MT in January to 11.1 MT by the end of July.5 

However, higher prices improve the economics of recovering and removing sulphur that couldn’t be justified before, encouraging more investment. 

— Wilson Fink, Agriculture Policy Lead

Trump and Sheinbaum spoke amid trade talks  

  • U.S. President Donald Trump and Mexican President Claudia Sheinbaum discussed a trade deal that remains in the works. A fourth round of formal discussions related to the U.S.-Mexico-Canada Agreement review will take place at the end of the month.   

Canada’s international trade minister went to Asia  

  • Minister Maninder Sidhu travelled to India and the Philippines, where he was set to meet officials and advance trade deal negotiations.  

EU took aim at its trade deficit with China   

  • European Commission President Ursula von der Leyen said the EU “will use all the tools” to rebalance its relationship with China. Europe had a goods trade deficit of €1 billion a day last year.  

U.K. wants in on Brussels’ “Made in Europe” policy  

  • U.K. Chancellor John Healey urged EU finance ministers to design the bloc’s “Made in Europe” industrial policy to include Britain. The two sides have previously clashed over the policies, intended to shield the bloc’s manufacturers from Chinese competition.  

Disclaimer

rbc_tl_disclaimer

Listen on Apple Podcasts, Spotify or Simplecast

With questions swirling around AI sovereignty, safety and regulation, we bring you an important conversation this week.

Recorded at the Milken Institute Global Dialogues in Toronto, Cohere co-founder Aidan Gomez, RBC President and CEO Dave McKay, and Evan Solomon, Canada’s Minister of Artificial Intelligence and Digital Innovation, discuss who should write the rules for frontier AI, why access to the most advanced tools is uneven, and whether Canada can support a global champion.

Aidan Gomez is co-founder and CEO of Cohere, a Toronto-headquartered enterprise AI company founded in 2019 with Nick Frosst and Ivan Zhang. He was one of eight authors of the 2017 paper “Attention Is All You Need,” which introduced the transformer architecture used in modern large language models. He holds a degree from the University of Toronto and a PhD from Oxford.

Cohere is a Canadian AI company building large language models and AI products for regulated industries including finance, healthcare, energy and the public sector, along with government. It is headquartered in Toronto with offices internationally.

Whether Canada can convert its role in inventing modern AI into lasting economic and strategic advantage, and who should be setting the rules for frontier AI systems.

The panel argues Canada has the research base, the talent and a frontier-model company, but has been slower to capitalize on deployment. The question raised is whether capital, access to advanced tooling and policy can align before the window closes.

McKay describes product development cycles compressing sharply, with work that previously took years now measured in months. He argues the effect on work is reallocation and retraining rather than straightforward elimination.

Disclaimer

rbc_tl_disclaimer

Canada’s nation-building strategy runs through First Nations territory.

As the country embarks on a new development wave, spanning hydroelectricity grids, copper mines, and liquefied natural gas projects, Indigenous groups are front and centre in several roles: as communities, investors, and the labour force. They are also likely to be most deeply impacted by the developments.

As it seeks reconciliation, Canada has a generational opportunity to leverage Indigenous expertise, include them in the fruits of new capital injection, and make some headway in redressing long-standing issues of exclusion.

There is no nation building without First Nations, Inuit, and Métis communities being involved.

Our Nations Building report, published earlier this year, examined why the capital architecture set up to facilitate Indigenous participation in Canada’s development does not match the impending project wave. This briefing measures the mismatch.

Key Pillar: Building Canada with Indigenous participation

Prize of development$ billion
Construction cost of Major Projects Inventory developments690
Operating + sustaining costs of projects (20-year timeframe)1,053
Price of development
Equity required in MPI projects314
Indigenous equity required51
Indigenous Loan Guarantees17
Indigenous loan guarantees already deployed3

Sources: RBC Thought Leadership, Natural Resources Canada’s Major Projects Inventory, Indigenous Energy Monitor

  • New infrastructure is vital for Canada to meet its new trade goals. Ottawa’s target of $300 billion in additional non-U.S. trade over the next decade1 depends largely on expanding its energy base, scaling its minerals riches, and developing the infrastructure that moves them to overseas markets.

  • Indigenous territorial borders intersect nearly every major economic development plan in Canada. More than 70% of the Major Projects Inventory sits within 20 kilometres of an Indigenous community.2

  • Starting projects with the right stakeholders would speed up development. Similarly, more than 70% of the $126 billion fast-tracked by the Major Projects Office—launched by the Mark Carney government to fast-track nation-building projects—runs through Indigenous territories. Creating pathways for Indigenous participation could be decisive in ensuring Canada can restore its reputation as a builder of large-scale projects.

  • The financing opportunity is immense. The inventory lists 475 active projects worth ~$690 billion, requiring an estimated $314 billion in equity financing3. That would require foreign and domestic capital, interlaced with blended finance, loan guarantees and other support to bridge the gap.

  • There are more opportunities beyond the new build. The new proposed projects are only a portion of a broader opportunity. Another major untapped area are operating assets—pipelines, transmission, terminals—where the largest Indigenous equity transactions to date have occurred.

  • Nation building projects would lift the economy. Together the projects could generate $1.45 trillion in GDP, $665 billion in labour income, 310,000 jobs annually, and $170 billion in government revenue.4 This accrues to the country rather than to any community specifically.

  • Trade pressures highlight the need for speed—and financing challenges. U.S. tariffs imposed in 2025 exempted energy, potash and critical minerals—exports with the fewest substitutes, and the sectors most represented in this pipeline. Trade uncertainty raises the weight of domestic capital financing it.

  • Hydro One offers First Nations up to 50% equity in every new large transmission project. The standing policy was adopted after the Wataynikaneyap Power project, in which 24 First Nations hold 51% of a $1.9 billion system connecting 17 remote communities, demonstrated majority Indigenous ownership at scale.

  • The Haisla Nation has a 50.1% stake in the $6-billion Cedar LNG project on the West Coast. It’s a majority Indigenous ownership, financed without a loan guarantee.

  • Suncor directed 20% of its total supply-chain spend to Indigenous businesses in 2022, up from 8% in 2019—a 2.5x increase in three years.

  • Trans Mountain delivered 25% of contract value to Indigenous businesses and roughly 11% Indigenous workforce participation during construction.

  • BC Hydro and SaskPower have set minimum First Nations equity ownership requirements in power procurement, 25% and 10%, respectively, as conditions of bidding, at no fiscal cost.

Full Indigenous equity participation would require around $51 billion. That’s a 16% weighted share of the $314 billion equity requirement, and would return roughly $75 billion, net of the capital invested, over a 20-year horizon, according to our research.

While $51 billion is not a requirement for projects to proceed, it creates room for Indigenous groups to become stakeholders and play a meaningful role in the development of Canadian resources and the wider economy.

The existing architecture is not set up to match the requirements. Federal and provincial Indigenous loan guarantee programs hold more than $17 billion in combined authority. As much as $2.5 billion had been deployed across 27 transactions5 from 2009 to June 2026. The requirement is roughly three times the federal and provincial authorities that exist to support it.

Ownership does not require entry at the outset. Stakes can be acquired at financial close or in assets already operating, which is how the largest Indigenous transactions to date have been structured: an Indigenous partnership acquiring an interest in an operating pipeline system, a post-completion equity option, a federal asset signalled for divestment. Roughly one-eighth of the requirement modelled here sits in projects essentially already built and generating cash flow.

The opportunity for Indigenous groups extends beyond new projects. Corporate resource projects—oil and gas, mining, LNG—hold roughly 60% of the pipeline’s capital and carry the highest expected returns. Contracted and regulated assets, including transmission and community-scale power, return less but are more predictable. Assumed participation in this analysis varies accordingly, with capital intensity and technological maturity: highest in smaller, contracted, mature assets, lowest in the largest resource projects. A portion of the requirement also sits in Crown-owned assets, where participation would require a policy decision to open equity to outside partners—a decision with precedent, in Ontario’s transmission and Darlington nuclear projects.

Value from these projects can reach communities through four channels that can be blended or priced independently.

  • Channel 1—Ownership. Equity of $51 billion returns approximately $75 billion, net of capital, over 20 years. Even this is conservative, as transmission assets operate for roughly 70 years, hydro assets even longer, and nuclear refurbishments extend station life toward 80. The model counts no more than 20 years of distributions from any project regardless of its actual life. The economics of these assets extend well beyond the window in which this report accounts for them.

  • Channel 2—Agreements. Impact benefit agreements are negotiated payments from proponents to Indigenous governments, typically struck on a project’s revenue or production rather than its capital cost. According to the Indigenous Energy Monitor, Disclosed payments reached $847 million in 2025 and $4.2 billion cumulatively since 2017, across 231 reporting companies and 287 Indigenous government recipients. Because only mandatory disclosure is captured, these are floors. Notably, they concentrate in projects where equity participation is least common, with mining at highest risk. This study does not model agreement payments across the inventory: the dataset is built on capital cost, and no defensible bridge exists to revenue-based payment structures.

  • Channel 3—Work. Indigenous workers earn wages and Indigenous businesses win contracts on these projects irrespective of ownership. Applying capture rates grounded in disclosed outcomes—4% to 12% of labour income, and 10% to 30% of the Tier-1 domestic contract pool—yields an estimated $27 billion to $80 billion in wages and $59 billion to $177 billion in procurement over the 20-year window. The base of each range assumes nothing more than demographic parity in hiring and a procurement share below levels several major operators already report. This channel requires no capital commitment from any Nation.

  • Channel 4—The build. The aggregate is $1.45 trillion in GDP, $665 billion in labour income, 310,000 jobs annually, and $170 billion in government revenue6. This accrues to the country rather than to any community specifically, and is the reason participation question matters beyond the parties directly involved. Ownership distributions and wage flows are components of this total, not additions to it.

  • Two concerns shape real decisions and deserve direct treatment. First, taking equity might displace an existing agreement. It does not: the channels draw on different pools and pay different recipients. The national payment data confirms the separation, as disclosed agreement tracking explicitly excludes contractor and supplier payments. Second, own-source revenue from an equity stake can, over time, reduce federal transfers that fund basic services. That concern is real.

  • Look beyond equity for Indigenous participation. A project that does not suit equity by a Nation need not exclude them. Much of the mining pipeline carries commodity and construction risk that a community dependent on stable distributions may rationally decline, a judgement any institutional investor would exercise. But there are other ways Nations can participate, such as the $85 billion of estimated value through wages and procurement alone that these projects generate nationwide. That would require no capital at all from Indigenous groups, but help lift the community’s economic prospects.

  • As the world’s second-largest country by area, Canada requires infrastructure at continental scale to move energy and minerals to market. Most resource endowments, and therefore most major projects, sit outside urban Canada, on or near the traditional territories of more than 630 First Nations as well as Inuit and Métis communities.

  • Section 35 of the Constitution Act, 1982 recognizes and affirms the rights of Indigenous peoples. It is constitutional law, not policy. From it flows the Crown’s duty to consult and, where impacts are serious, to accommodate, before projects proceed. Canada has also legislated alignment with the UN Declaration on the Rights of Indigenous Peoples, whose standard of free, prior and informed consent shapes project processes. Equity participation is a financial structure; it is not a substitute for consent.

  • The legal landscape varies by region. Most of British Columbia is not covered by historic treaties, which makes title and consultation dynamics materially different from Alberta and the Prairies.

  • Federal and provincial loan guarantee programs spanning $17 billion have existed to backstop Indigenous borrowing for equity stakes in these projects. Indigenous ownership is well established with majority stakes in operating LNG, transmission and midstream assets. The federal government has also signalled selling assets to Indigenous buyers.

Download the Report

All data sourced from Indigenous Energy Monitor (IEM) unless otherwise mentioned. Indigenous Energy Monitor data is sourced from IEM’s Indigenous Energy Ownership Tracker (IEOT) module and Indigenous Resource Payment Tracker.

Disclaimer

rbc_tl_disclaimer

The world is changing, and so is Canada.

The 2020s have already presented several waves of disruption, from geopolitical shocks and wars to extraordinary advances and discoveries in space technology, life sciences and artificial intelligence. In the midst of these waves of change, we’re seeing a shift in trade and investment flows. Canada is at the nexus of those changes.

The world’s largest investors are in Toronto this September to explore and discover that changing Canadian prospectus. Beyond the deals, you will find a country with abundant resources, a resilient rule of law, and one of the world’s most educated and globally-minded populations. This is the opportunity and the moment. This is Canada now.

Manufacturing is Canada’s largest goods-producing industry, and the country’s deepest link to the U.S. economy. Factories mostly located in Ontario and Quebec generated around $850 billion in sales last year, employing 1-in-12 Canadians, with about half of the output exported around the world.

Canada’s Windsor-to-Montreal corridor is home to auto assembly plants, aerospace firms, Tier-1 parts suppliers, machinery and equipment makers, robotics firms and tech companies. The corridor also features skilled labour and globally competitive universities, producing the skilled trades, R&D, and IP needed to support the sector.

$850B

Manufacturing sales in 2025

#1

Foreign supplier of steel and aluminum to the U.S.

5th

Largest exporter of
aerospace products

9th

Largest auto exporter

Four advanced industries anchor the sector, drawing on a base of primary and fabricated metals, chemicals and plastics that together account for nearly $60 billion in annual GDP.

A competitive auto hub

Canada is home to five OEMs—Toyota, Honda, and the Detroit Big Three—and 700 suppliers that ship more than $100 billion in vehicles and parts each year.

While vehicle assembly volumes have fallen since 2010, parts output has grown 10% in the same period, with value migrating to powertrains, electronics, battery systems and software, where Canadian firms like Magna, Linamar and BlackBerry QNX compete.

Canada’s levelized cost for EV assembly is at parity with the U.S., with cleaner and cheaper power in Ontario and Quebec.

A high-flying sector

Canada’s aerospace industry contributed $33 billion to GDP and employs nearly 220,000 people.

Defence aerospace revenue reached $6 billion in 2024, close to 15% of industry revenue, with the $40 billion NORAD modernization creating sustained demand. Demand is expected to increase domestically and globally, partly driven by higher expenditures from NATO countries.

Canada ranks in the top five globally in civil flight simulators, engines and aircraft.

A robust heavy-industry pipeline

Machinery is a $20 billion industry well positioned to supply LNG terminals, mines, grid expansion with $290 billion in defence-related capital projects in Canada’s pipeline.

Manufacturers’ unfilled orders rose 7% to $115 billion at the end of 2025, driven by shipbuilding and aerospace.

A range of value-add industries

Canada is the world’s fourth-largest aluminum producer, with capacity of roughly 3.3 million tonnes.

Chemical manufacturing adds $22 billion to GDP, while pharmaceuticals contributed $8 billion.

Canada is the birthplace of deep learning. The chief scientific advisors of all three national AI institutes: Amii (Edmonton), Mila (Montréal) and the Vector Institute (Toronto) are Turing Award laureates. Canada was the first nation in the world to adopt a national AI strategy, in 2017. And its one of very few countries outside the U.S. and China with a frontier model company. Cohere, founded in Toronto in 2019, builds language models for enterprise and government, and is differentiated by its ability to handle sensitive data in secure and onpremise environments. Talent density is another durable advantage. Toronto ranks third globally for tech talent, behind only the San Francisco Bay Area and Seattle.

3,500

AI firms

10%

Share of top AI researchers

$14.5B

Total VC funding across
2,468 deals (2014-2025)

3

Of the world’s top 10 AI
talents pools (Toronto,
Montréal and Vancouver)

Canada’s AI economy spans five layers: foundation models, the language systems underpinning most applications; physical AI, robotics and autonomous systems that act in the world; applied AI embedded in health, agriculture, finance and resources; compute and data centres; and research and safety institutions. Strength is concentrated at the top and bottom of that stack. The middle is where capital is most needed, and where returns are least crowded.

Compute infrastructure: the closest near-term opportunity

Canada has roughly 337 megawatts of AI data-centre capacity today and requires an estimated 5.5 gigawatts by 2030 to serve domestic commercial players.

Ottawa is targeting 850 megawatts of sovereign capacity by 2030, scaling toward 2.3 gigawatts, supported by more than $2 billion in federal commitments and expected to draw tens of billions of dollars in private capital.

The export opportunity, serving allied markets from Canadian soil, is estimated at a further 1.7 to 6.7 gigawatts.

Sovereign AI as an export product

Canada’s frontier model capability, clean power and democratic rule of law makes it a credible supplier to nations seeking alternatives to American or Chinese platforms.

Closing the scale-up gap

Nearly 70% of Canadian-founded startups end up headquartered abroad, a long-standing leakage Ottawa is now addressing through a $500 million Canadian Tech Growth Fund, direct equity stakes in national champions, and a newly established sovereign wealth fund.

For foreign capital, this is the arbitrage: world-class research and companies priced below U.S. comparables, with government as a co-investor.

The adoption gap in a high-value economy

Only about 12% of Canadian businesses have integrated AI, against a national target of 60% by 2034.

The five priority sectors–health and life sciences, energy and critical minerals, transportation, agriculture, and manufacturing and robotics are areas where Canada holds globally significant physical assets and proprietary data.

Canada co-invented quantum cryptography. BB84 protocol, the first practical method for securing communication through the laws of physics rather than mathematical difficulty, was co-developed in 1984 by Gilles Brassard at the Université de Montréal with IBM’s Charles Bennett. The two received the 2025 ACM Turing Award in March 2026. Canada also launched the world’s first commercial quantum-computing computer, and Toronto-based 1Qbit was recognized by the World Economic Forum in 2015 as the first company dedicated to commercial applications for quantum computers.

Canada’s quantum sector has attracted more than $2.8 billion in combined public and private funding. Between 2018 and 2022, sector revenue rose 93%, the number of companies expanded 41%, and employment grew 111%. The industry is on track to add $7.7 billion to the economy and unlock more than 157,000 jobs by 2045.

4

Quantum companies in
Canada valued above
US$1 billion, a
concentration no
country outside the
United States has
matched

300

Quantum researchers in
Waterloo, Ont., home to
20 quantum companies
and institutions

3

Number of Canadian
companies—Xanadu,
Photonic and Nord
Quantique—of the 11 that
advanced to Stage B of
DARPA’s flagship Quantum
Benchmarking Initiative
that validates commercial
claims

$695M

Total federal
commitment under the
Defence Industrial
Strategy and the 2023
National Quantum
Strategy

McKinsey’s 2026 Quantum Technology Monitor projects the global market for quantum technology will be US$60–100 billion by 2035, with computing accounting for US$43–71 billion, and estimates up to US$2.7 trillion in broader economic value by 2035.

Quantum-safe cryptography, the nearest-term revenue opportunity

The Canadian Centre for Cyber Security’s roadmap required federal departments to produce migration plans by April 2026, with high-priority systems transitioned by 2031 and all remaining systems by 2035. The Global Risk Institute’s 2026 Quantum Threat Timeline, produced with Waterloobased evolutionQ, assesses a cryptographically relevant quantum computer as “quite possible within 10 years and “likely” within 15. Because adversaries can capture encrypted data now for later decryption, migration demand exists independent of when the hardware arrives.

Quantum sensing applied to the resource base

Sensing has direct application to mineral exploration, subsurface imaging, and navigation in GPS-denied environments including the Arctic, areas where Canada has both commercial need and sovereign interest. The global quantum sensor market is projected at approximately US$550 million in 2026.

Co-investment at reduced risk

Canadian quantum firms now carry matched federal, provincial and U.S. defence funding. Nord Quantique reached unicorn valuation on less than US$60 million raised, indicating capital efficiency uncommon in the sector.

Home of the oilsands, Canada boasts the world’s third largest crude oil reserves, mostly in Alberta. Canada is the U.S.’s largest source of imported crude, with both countries benefitting from a continental and integrated energy market. Canada’s ambition to expand its market access to Asia helps oil-importing countries diversify their sources of oil supply. Its offshore East Coast reserves of three-billion barrels has also attracted attention from global oil majors.

The world’s fifth largest producer of natural gas also has ambitions to leverage its abundant conventional and shale reserves, with several multibillion- dollar gas export projects planned and underway on the West Coast.

10.3%

Canada’s share of the
world’s proven oil reserves

72,000

Oil and gas sector jobs
needed by 2035

4th

Canada’s rank among the
world’s top oil producers

$151B

value of new projects in
planning stages

Canada set a new production record of 5.35 million barrels of oil per day (bpd) in 2025, with the key oil producing regions of Alberta, Saskatchewan, British Columbia and Newfoundland and Labrador, registering growth. Canada exported crude oil, refined petroleum products, natural gas products valued at $157.5 billion in 2025 to the U.S.—a fifth of its total goods exported globally. More than 90% of Canadian oil and gas is shipped to the U.S.

New pipeline projects

The start of the 890,000-bpd Transmountain Expansion Project in 2024 helped Canada expand its exports to Asiaand find new markets beyond the U.S.

A new comprehensive partnership between Alberta and the federal government could spur a new wave of development. It includes a one million bpd Alberta-to-British Columbia pipeline proposal that would encourage more production.

There are proposals to revive the Keystone XL oil pipeline connecting Alberta to the Gulf Coast, expanding the 450,000 kilometres of oil and gas conduits connecting the two nations.

Building on its carbon capture lead

To mitigate emissions, five major oilsands companies are collaborating with the federal government and Alberta to develop the $16.5 billion Pathways Carbon Capture project with six million tonnes per year of captured CO2 capacity by the mid-2030s.

A burgeoning LNG Industry

Seven liquefied natural gas (LNG) export projects and one infrastructure project are at development stages. Together, they represent a capital investment of ~$109 billion and potential production capacity of 50.3 million tonnes per annum of LNG.

Growth beyond Alberta

The Montney formation located in the Prairies can potentially produce around 450 trillion cubic feet of natural gas—making it one of North America’s largest gas resources.

Five offshore fields off Newfoundland and Labrador have boosted production and now account for 4.5% of Canadian production. Exxon Mobil and Equinor are among global investors operating in the province.

Canada’s abundant water resources and technological innovation have transformed it into a hydro and nuclear powerhouse. Hydro accounts for 60% of Canada’s power generation, playing a key role in Quebec, British Columbia, Ontario, Labrador and Manitoba grids. Canada is also a nuclear technology pioneer with the home-grown CANDU reactors operational in six countries, while the G7’s first small modular reactor
is under construction.

Solar, wind power, and battery storage are also emerging as vital pieces of a vast network of grids and connections that power 10 provinces and three territories. Several provinces also provide power to U.S. states such as New York, Vermont, Maine, Massachusetts, and Michigan.

4th

Canada’s global rank as
hydropower producer

14%

Nuclear’s share of power
generation

28,000

Clean electricity jobs
openings expected by
2028

56%

Growth in wind, solar
and storage installation
(2020-2025)

Despite a relatively small population of around 41 million, Canada is the world’s 7th largest producer of electricity. Clean power is attracting new industries—from electric vehicles to data centres—keen to reduce their carbon footprints.

A $1-trillion blueprint

A new National Electricity Strategy aims to double the national grid by 2050, to ensure clean, reliable, and affordable electricity will continue to power the country for decades to come.

The plan would require multi-billion-dollar investments in generation, transmission, distribution, storage, grid modernization, and connecting Canada’s fragmented East-West-North grids through expanded transmissions lines.

North America’s largest clean energy investment proposal

Quebec and Newfoundland and Labrador are leveraging Canada’s formidable hydro resources to develop a series of landmark projects valued at $70 billion the largest of its kind in the continent.

The projects would include upgrades to Churchill Falls, construction of a new 2,700MW hydroelectricity facility, new transmissions lines, and onshore wind projects that will boost the region’s critical minerals and infrastructure corridor.

Ontario’s all-of-the-above strategy

The country’s largest provincial economy will see power demand rise 65%. It intends to meet this demand with hydroelectric and nuclear facilities, and natural gas, but also wind and solar, with an estimated investment of $450 billion. Nuclear is a key pillar, with plans for large scale nuclear facilities and proposals for two new sites in the province. It’s also building the G7’s first grid-connected small modular reactor (SMR) at the new Darlington nuclear site.

Regional expansion

BC Hydro is investing $36 billion over the next decade to upgrade grid capacity, plus new electrification expansion and greenhouse gas reduction efforts.

Quebec’s Action Plan 2035 will oversee the development of 11,000 MW of clean energy through investments totalling $200 billion.

With production of 60 minerals and metals from more than 200 operating mines, Canada is seen as a viable commodity source for countries looking to diversify their critical mineral supplies. Canada is already the world’s largest producer of potash, the second-largest producer of uranium, and the second-largest exporter of aluminum. Meanwhile, deposits of lithium, graphite, nickel, copper, cobalt, and rare earth elements across the country offer fresh opportunities.

Federal policy is now focused on providing direct capital and faster permitting to accelerate critical mineral development. Canada combines a diversified resource base with growing policy support, allied demand and major processing opportunities.

$162B

Mineral and metal exports

140

Number of mining projects
planned between 2024-2034

171

Number of advanced
projects

$72.4B

Value of critical mineral
projects planned in
Canada through 2034

A high-grade resource

Saskatchewan’s Athabasca Basin is home to the world’s highest-grade uranium deposits. Uranium exports topped $2.9 billion in 2025.

A formidable food security resource

Potash is a vital component in fertilizers. Canada is the world’s largest potash producer and exporter and has the world’s largest potash reserves.

A copper powerhouse

Canada’s copper exports reached $11.9 billion in 2025, while nickel hit $4.3 billion and zinc $1.9 billion. The pending Teck–Anglo American merger will put the headquarters of a top-five global copper producer in Vancouver, with commitments to spend at least $4.5 billion in Canada within five years.

Midstream processing opportunities

Canada’s strength is upstream—most of the $49.4 billion in critical mineral exports are primary, smelted or refined products. There is a gap in process and specialty materials. Federal capital and allied offtakes are focusing on processing, as it offers a strong investment case.

The northern Ring of Fire

The Ring of Fire, about 500-kilometres northeast of Thunder Bay, Ont., is home to many critical minerals. While no mine operates there yet, Ontario is advancing several road projects to the region, which has the potential to create 70,000 jobs and generate more than $22 billion over 30 years.

Rare earths and magnets resource

The Saskatchewan Research Council’s Saskatoon facility was the first in North America to produce rare earth metals at commercial scale. Substantial completion of the facility is scheduled for September, and it will be fully operational in 2027.

As the world’s second largest country by size, Canada’s infrastructure is in a constant state of construction, expansion and revitalization. It began with the 4,600-kilometre Canadian Pacific Railway in 1871, which bound the country together. The country’s railways network is now the world’s fifth largest, supplemented by a one-million-kilometer road network, the 8th largest globally.

And there’s more construction ahead. Canada’s infrastructure deficit—also spanning airports and seaports—is estimated at up to $270 billion, with Transport Canada projecting $4.4 trillion in trade-enabling investment by 2070. That gap is beginning to be addressed with both funding and policy.

7th

Canada’s rank in the
World Bank’s Logistics
Performance Index, ahead
of the U.S.

224

Number of airports across
the country

$300B

Value of goods shipped
through Canada’s 17
seaports annually

$4.6B

Federal investment
pledge to expand the
National Trade Corridors
by 2028

The federal budget for 2025 committed $6 billion to a Trade Infrastructure Strategy covering ports, railways, airports, highways, and northern corridors, while a Major Projects Office was created to streamline permitting timelines and target $500 billion in private investment in the next five years.

A continental rail network

Two major railways, Canadian National (CN) and Canadian Pacific Kansas City (CPKC) represent more than 75% of the total tonnage moved by rail.

With 70% of Canadian exports destined for the U.S., much of the rail and road infrastructure is built around that market. But Canada’s national target to double non-U.S. exports within a decade and generate $300 billion in new trade requires moving far more volume east and west rather than south. Rail, ports, and roads will need major investment to accommodate these new volumes.

Seaport expansion to help cast a wider trade net

Seventeen Canada Port Authorities operate in marine shipping, led by Vancouver, moving $300 billion in goods a year, alongside Prince Rupert, Montreal, Halifax, and Saint John. Nation-building seaport projects, such as Montreal’s Contrecoeur Container Terminal Project, and the Roberts Bank Terminal 2 project in the Port of Vancouver, are set to accelerate development of the country’s diversified trade routes.

Proximity to Asia

B.C. coast LNG projects are 10 shipping days from Asia versus 20 days from the U.S. Gulf Coast; Eastern Canada is 6 to 8 shipping days from Europe—the shortest distance of any North American LNG project.

Bringing Arctic and Northern Corridors riches to market

The $1-billion Arctic Infrastructure Fund is poised to kickstart investment into logistics, but private capital will be required for scaling development of the north.

The airport privatization opportunity

Canada’s major airports are run by not-for-profit authorities that are closed to private equity since the model was created in the 1990s. More than $28 billion in upgrades are needed over the next decade to revitalize major airports. The federal government has committed to introducing legislation in 2026 to review ownership and lease reform, potentially creating significant opportunities for private investors.

Surrounded by three oceans, and a vast Arctic territory, Canada is exposed to a rise in military activity. As allied defence spending surges, Canada is stepping up military innovation and laying the ground for a globally competitive defence industry.

Canada shares responsibility for continental defence with the U.S. through the North American Aerospace Defence Command, and is part of the Five Eyes intelligence network, and a founding member of NATO. In the past 18 months, Canada has secured more than 20 international defence and security partnerships and agreements, and has become the only non- European state with preferential access to the European Union’s €150-billion SAFE defence procurement program.

5%

Canada’s pledge to raise
defence spending as a
share of GDP (from less
than 2%)

2nd

Rank among exporters of
armoured vehicles

$290B

Value of defence-related
capital investment
opportunities

600

Defence firms, employing
an 81,000-strong
workforce

The surge in Canada’s defence spending includes a $180 billion defence procurement pipeline and a projected $290 billion in defence-related capital investment opportunities.

A new Defence Industrial Strategy

The new strategy aims to accelerate domestic revenue by 240%, while raising domestic procurement share to 70% and boosting defence exports by 50%.

A new dedicated Defence Investment Agency aims to streamline major procurements targeting 10 key sovereign capabilities, including aerospace, ammunition, and specialized manufacturing.

The multilateral Defence, Security and Resilience Bank will be headquartered in Canada, while the Business Development Bank of Canada and Export Development Canada have established dedicated defence platforms.

Command, Control, Communications, Computers, Intelligence, Surveillance and Reconnaissance (C4ISR)

Canada’s $38.6 billion, 20-year NORAD modernization creates sustained demand across sensors, secure communications and space-based surveillance. Unmanned Autonomous Systems (UAS) will play a key role in these networks and represent a growing sector of Canada’s defence industry.

A training and simulation hub

Canada ranks in the top five globally for in-flight simulation, with an export-oriented base for training and mission rehearsal.

Training and simulation are designated sovereign capabilities, while new defence programs are expanding access to operational environments, ranges and test infrastructure for Canadian technology developers.

Raising dual-use industrial capacity

A $5-billion industrial fund was launched to support retooling (including to the defence sector) in steel, aluminum and other tariff-exposed industries. And in April 2026, Canadian manufacturers established the country’s first integrated ballistic-steel production venture.

Defence infrastructure spending includes a $3.7-billion pipeline to build military housing, using modular construction and Canadian steel, lumber and building systems. $40 million has also been allocated to assess microreactors for remote and Northern operations.

Canada has a proud history as a spacefaring nation dating back to 1962, when it became only the third nation to successfully orbit a satellite with Alouette 1. A decade later, Canada became the first country to launch a domestic communications satellite into orbit. And in 1981 when the Canadarm technology made its debut on NASA’s second Space Shuttle mission, it revolutionized space exploration and satellite maintenance.

More recently in 2020, Canada joined the NASA-led multinational Artemis mission to return humans to the moon and prepare for crewed missions to Mars. Earlier this year, Canadian astronaut Jeremy Hansen flew on the Artemis II mission looping behind the far side of the moon, making him the first non-American to ever travel beyond low Earth orbit.

200

Organizations

$5B

Annual revenue
(43% from exports)

170%

Increase since 2019
in upstream revenue
from space-systems
manufacturing, navigation
and Earth observation

413

Number of space-related
patents in 2024, a 21%
increase year-on-year

Launching a commercial space system

Canada is already globally recognized for its expertise in sensing technologies. The country is building one of the largest commercial space systems around a sovereign low Earth orbit broadband constellation and expanding satellite manufacturing.

Space data, sensing & in-orbit infrastructure

Canada has long-established Earth observation capability and new systems are moving data and computing into orbit.

A higher orbit

Canada is targeting initial sovereign orbital launch capability by 2028 from its Atlantic coast with geography that places satellites into polar paths that can scan the entire globe.

A stellar communications opportunity

Roughly $12 billion in new capital for Canadian space ventures over the next decade, could in turn generate more than $20 billion in annual industry revenue building on these capabilities and unlocking new opportunities.

Now, Canada is investing in programs focused on nextgeneration technology in robotic space exploration, sovereign orbital infrastructure and
satellite communications. Last month, the government awarded an initial $2.3 billion contract to expand Arctic low Earth orbit satellite systems entirely to Canadian firms.

A North American opportunity

NASA’s US$24-billion budget for 2026 includes more than US$7 billion for lunar exploration and US$1 billion in new investments for Mars-focused programs. Private developers also have multi-billion-dollar plans spanning satellite communications, spacecraft development and space travel. Several of these plans span the continent.

A burgeoning export industry

While 68% of Canada’s space-related exports are destined for the U.S., Europe has emerged as Canada’s second-largest market. Last year, Canada invested more than $660 million in European Space Agency programs to advance research and development of Canadian-made space technologies for both civilian and defence purposes.

Canada’s abundant and fertile lands have transformed it into one of the world’s biggest food exporters. The sector employs more than two million people, making up 7% of the country’s GDP. Agricultural innovation has long been a Canadian strength—it is where canola, named after the nation, was invented in the 1970s. Canada is now the world’s largest canola exporter.

Today, Canadian agriculture continues to undergo a technological transformation, with AI, drones, robotics, genetics, biologicals and precision tools playing increasing roles in production, and creating significant opportunities for Canada.

1 in 9

Jobs that are supported by
Canadian agriculture

$100B

The value of Canada’s
agri-food exports

#1

World’s top producer of
canola and pulses

6.2%

Canada’s land area
covered by farms

Value-add and processing

Food and beverage processing is the second largest manufacturing sector in Canada, with sales reaching $173.4 billion in 2024.

Canada is now home to 15 canola crushing and refining plants that process 14 million tonnes of canola each year, helping meet growing demand for biofuels and cooking oil. Similar opportunities exist across other commodities.

The era of agri-tech

Agricultural technology is transforming farming, through the use of AI, drones, robotics, as well as the use of genetics and biologicals. The precision farming market—using technology to make the process more efficient—is growing and expected to reach $4.9 billion by 2030.

Public research capacity in seed genetics and crop protection is well established in Canada and closely tied to industry, with companies eager for capital to scale their solutions.

Infrastructure expansion plans

Agricultural value chain opportunities are rife, such as the Westside Irrigation Rehabilitation Project in Saskatchewan that is expected to open 90,000 acres of irrigated land, contributing $12.9 billion to GDP.

Most of Canada’s agri-food is produced in regions that depend on railway systems and inland terminals. Infrastructure will have to keep up with rising global demand, requiring investments in capacity, terminal throughput and storage.

Export opportunities

Global demand for food continues to rise, while arable land and freshwater is scarcer—and Canada holds both in a surplus. Canada is the ninth largest exporter of agri-food, fish and seafood products, exporting to more than 200 countries as of 2024. While the U.S. is the destination for most agri-food exports, Canada has been diversifying to other markets.

Canada’s life science sector is a growing economic and innovation centre, featuring a world-class research network and top pharmaceutical, biotechnology and medical technology firms. Canadian researchers have made foundational contributions to public health—including the discovery of insulin, stem cells and the GLP-1 hormone—and have contributed to major advances in vaccine development and disease treatment.

With billions of dollars invested in research and development, the sector combines scientific expertise with commercial potential. Innovative research, major multinational presence and government investments aimed at growing the sector position Canada to become a more prominent player in the years to come.

+15K

Number of clinical trial
researchers

$51B

Pharmaceutical sales

23.6%

10-year internal rate of
return

$250-
300B

Economic value that
Canadian innovations are
projected to generate by
2035

A pharmaceuticals and biotechnology hub

The worldwide pharmaceutical market exceeded US$1.7 trillion in 2025 and continues to grow. Last year, roughly 95% of innovator drugs in major pharmaceutical pipelines traced back to smaller biotech firms. As pharmaceutical firms diversify their innovation activities, Canadian companies and research organizations are taking on an increasingly important role in R&D.

Canada’s pharmaceutical sector is the 9th largest in the world and has been growing rapidly at 9% per annum since 2020.

Since 2021, more than $15 billion in Canadian biotech value has been acquired by global pharmaceutical players— including Trillium (acquired by Pfizer, 2021), Inversago (Novo Nordisk, 2023), Chinook (Novartis, 2023), Bellus Health (GSK, 2023), Fusion (AstraZeneca 2024).

Some of the world’s largest global firms—such as AstraZeneca, Merck, Novartis, Pfizer and Sanofi—have made significant investments in operations, as well as research and development in Canada.

Clinical trials and R&D

Canada ranks No. 1 in active clinical trial productivity (number of trials per capita) among G7 nations. It’s No. 4 in the world in terms of clinical trial sites. In 2025, there were approximately 3,100 clinical trials taking place countrywide.

Canada offers world-class research infrastructure, with an extensive network of academic institutions conducting clinical research, including 17 medical schools, 40 academic healthcare organizations and more than 15,000 researchers.

Expertise in oncology, immunotherapy and specialty medicines positions Canadian companies to attract international partnerships and investments in these highvalue therapeutic areas.

Health Canada’s Agile Licensing pathway allows for promising therapies to be accelerated, with some treatments getting authorization in as little as 200 days, comparable to the Food and Drug Administration (FDA), but with early access to the Canadian market.

Foreign investors can tap various government organizations and programs to mitigate risk and help enhance return on investment.

First-loss / concessional risk absorption

Public capital can be structured to absorb a disproportionate share of downside risk

The Canada Growth Fund (CGF) was incorporated in 2022 with $15 billion to invest in strategic sectors, using public capital to absorb policy, execution, and market risks.

  • The Fund’s investments will look to accelerate the deployment of key technologies, support emissions reduction, scale up companies, encourage the domestic retention of intellectual property, capitalize on Canada’s natural resources, and strengthen supply chains.

In some cases, the CGF will “invest concessionally by accepting, where necessary, below-market returns relative to the risk it incurs,” using the lowest discount or risk absorption necessary to allow a project to move forward.

  • Private investors will not get disproportionate returns compared to the risk they carry and must share in the downside even if the Fund absorbs first-loss.

Common equity

Public institutions can anchor or enlarge the equity pool

In April this year, the federal government announced Canada’s first national sovereign wealth fund: the Canada Strong Fund (CSF), seeded with $25 billion over three years.

  • The CSF is intended principally as a commercial equity co-investor in nation-building projects, alongside private capital.

  • It will be designed to allow retail Canadian investors to participate, and the government has committed to delivering “commercial market-rate financial returns” for Canadians.

The Canada Infrastructure Bank (CIB) was created in 2017 to help address Canada’s infrastructure deficit, supporting revenue-generating projects “in the public interest.”

  • The CIB is focused on supporting community and housing infrastructure and clean energy development. It has committed $18.6 billion across 112 projects worth $55 billion.

  • It can take equity positions where an infrastructure financing gap prevents a project proceeding.

The Business Development Bank of Canada (BDC) is Canada’s national development bank mandated to help Canadian entrepreneurs and small and medium-sized enterprises create and develop stronger businesses, with $58.6 billion committed to clients.

  • Its subsidiary, BDC Capital, takes equity positions primarily in Canadian growth companies.

Export Development Canada (EDC) is Canada’s trade and export financing agency to help Canadian companies access and expand in foreign markets with over $52 billion in assets.

  • EDC can make equity investments where there is a relevance to Canadian trade or export activity.

Preferred / hybrid equity

Public institutions can provide capital between common equity and debt

The CGF can use preferred shares and hybrid securities with negotiated priority, return or conversion rights.

The CIB can similarly utilize preferred or hybrid equity to absorb specific project risks that deter private investors.

The CSF is expected to have flexibility within equity structures.

In some cases, EDC can take preferred or hybrid equity positions to match the lead investor’s commercial terms.

Subordinated / mezzanine debt

Junior debt from public institutions can add loss-absorbing capital beneath senior lenders

The CIB provides subordinated and mezzanine debt on concessionary terms for projects and will accept commercial risk that other investors are unwilling to bear, at a reasonable price, to crowd in private lenders.

At the corporate level, BDC Capital can provide junior debt to Canadian growth companies.

Senior debt

Public lending can extend financing capacity

Senior financing is generally supplied by commercial banks and institutional lenders.

EDC can lend directly alongside them where Canadian trade or export activity is involved, including structured and project finance.

The CIB can also provide senior project loans where financing constraints such as tenor or risk allocation prevent sufficient private lending.

Revenue / price floors

The CGF can support project investment through contracts for differences and offtake agreements.

  • These instruments may apply to industrial carbon credits and commodities and are designed to underwrite demand, insulating investors from future policy or regulatory changes.

Credit / political-risk protection

Defined credit or political risks can be transferred to a public balance sheet

EDC can provide trade and credit insurance, political-risk protection, and guarantee commercial lending; its credit insurance can typically cover up to 90% of an insured loss.

  • This can include trade credit insurance for when a foreign buyer does not pay, political risk insurance to cover currency inconvertibility and transfer restrictions, and expropriation, and commercial lending guarantees.

The CIB can also provide project loan guarantees on major infrastructure to crowd-in private lending on higher-risk projects.

Indigenous partner-level credit support

Sovereign guarantees can finance Indigenous equity ownership in projects

Indigenous land rights are constitutionally embedded in Canada, and the Crown has a duty to consult Indigenous groups which can lead to delays or halt infrastructure projects with government backing.

  • Most Indigenous reserve assets cannot be pledged as collateral, previously leaving communities largely unable to finance equity positions in projects.

  • Loan guarantees programs, designed to supply that financing while giving communities an ownership stake in a project’s performance, have proliferated across Canada to address this issue.

Through federal and provincial Indigenous Loan Guarantee Programs, an Indigenous community, or group of communities, can form an entity that borrows money to buy an equity stake in a project, with the government guaranteeing the lender.

  • If the project fails, the Indigenous partners’ equity is lost in the same order as other common shareholders, and the lender is repaid by government.

  • There are six government Indigenous Loan Guarantee programs in Canada (one federal, five provincial holding $18 billion of combined authority). Federal and provincial guarantees can be combined on a single transaction.

An Indigenous partner may also borrow directly. The CIB’s Indigenous Equity Initiative lends $5 million to $100 million for up to 90% of an equity purchase price where the CIB is already investing in the same project.

Permitting / schedule risk

A new government office will accelerate regulatory timelines for major projects

Established in August 2025 to cut regulatory and permitting bottlenecks impeding the development of critical national infrastructure, the Major Projects Office (MPO) assesses project proposals against national resilience and security, economic benefit, likelihood of successful completion, Indigenous benefit, and climate objectives.

  • Successful projects will be listed as a project of national interest, with the office mandated to cap the review timeline for these at a maximum of two-years compared to previous timelines of five years or more.

  • The process must run alongside Indigenous consultation and provincial permitting where relevant.

Download the Report

Disclaimer

rbc_tl_disclaimer

➔ Nepal floods highlight the consequences of glacier meltdowns

➔ Five signals from the government climate report

➔ Three bottlenecks delaying climate progress

U.S. tariffs are squeezing Canadian cleantech startups. Canadian cleantech firms raised $365 million in the first half of 2026, roughly flat year-over-year. The Canadian Clean Tech Alliance recommends smaller companies should think U.S.-plus, rather than U.S.-only to hedge their bets, protect contracts and stress-test a few reasonable scenarios. Ottawa’s upcoming fall budget is seen as pivotal to the sector’s competitiveness. The slow rollout of the federal Clean Tech Investment Tax credits is already feeding anxiety.

How do you protect one of Canada’s most pristine wetlands? Ducks Unlimited Canada, a wetland conservation leader, recently acquired East Meadows Ranch on Lake Manitoba, marking the largest conservation land purchase in the province’s history. The deal preserves 8,000 acres of coastal marsh, native grassland and Aspen Parkland, northwest of Winnipeg. Agriculture Policy Lead Wilson Fink says at roughly $9 million, paid for by private donors and the federal National Heritage Conservation, the deal showcases a blended capital model that’s sorely needed to protect Canada’s wild frontiers.

A Saskatchewan startup announced a hydrogen breakthrough. Regina-based Max Power drilled Canada’s first well dedicated to clean natural hydrogen at its Lawson Complex. The company says the drilling success is a global first, with the potential to develop into an entirely new primary energy industry. Major commodity investor Eric Sprott, who had backed the company, has boosted his stake in the startup to 24.35%. Natural hydrogen can feed into fuel cells to generate electricity and does not emit greenhouse gases.

The Canada Investment Summit on September 14-15 aims to showcase Canadian opportunities to the world. Interest spans a wide range of Canadian assets, but we’re focused on two energy transition-focused plays: critical minerals, and nuclear technology.

While the summit is focused on capital, climate watchers would be looking for clues on where climate policy, and crucially where climate competitiveness, fits in Ottawa’s grand plan to attract global capital.

Both critical minerals and nuclear offer climate policy momentum, but also face several obstacles.

Critical Minerals

Momentum

  • More than 55 active critical-mineral mines, 31 processing facilities, and 171 advanced projects, gives Canada a solid platform to build on.

  • Canada landed 13 new partnerships across eight-plus countries via the Critical Minerals Resilience and Production Alliance, launched during its own 2025 G7 presidency

  • Quebec added $1 billion to its critical minerals fund in Budget 2026-27, plus new mineral pacts with the U.K. (December 2025) and Germany (March 2026). Ontario launched its own $500 million fund last year.

  • Addressing the infrastructure gap and creating more certainty in the permitting and regulatory process, could help make Canada’s resources both more accessible and affordable, according to our new report in collaboration with McKinsey & Company.

Obstacles

  • Permitting remains the bottleneck despite the 2025 Building Canada Act’s single-window fixes; projects still take years to clear.

  • The strategy stays fragmented, with data gaps and undeveloped circular systems unaddressed across jurisdictions.

  • Rising global energy prices and trade tensions are actively squeezing project economics.

  • Most Indigenous partnership commitments are still mostly at the framework stage.

  • Heavy reliance on federal subsidy tools (Strategic Innovation Fund, tax credits) to de-risk private investment, suggests the market hasn’t proven it can stand alone yet.

Nuclear

Momentum

  • Darlington’s BWRX-300 is under construction—the first SMR in the G7, targeting grid connection by the end of 2030.

  • Strong existing base: 17 CANDU reactors already supply 13% of national electricity
    generation, while Canada supplies 24% of global uranium output, giving it real upstream leverage.

  • June 2026 loan guarantee enabled seven Williams Treaties First Nations to take a minority ownership stake in Darlington, highlighting Indigenous involvement going beyond consultation.

  • Ontario Power Generation’s new Wesleyville project filing (could add up to 10 GW more capacity),

  • Ottawa’s $100-billion Nuclear Energy Strategy, out in June, targets up to 10 new large reactors by 2040 and lays the platform for an export-based industry, targeting countries like Poland.

Obstacles

  • Darlington is the first-of-its-kind SMR in the G7, so budget and schedule assumptions would be carefully watched.

  • Execution risk is a key question—on-time, on-budget delivery isn’t guaranteed, and could cast shadow over future projects.

  • The $20.9 billion price tag for just four 300MW units invites comparisons with more affordable clean-power options.

  • Despite its advantages, Canada struggles with coordination between federal government, provinces, utilities and financing agencies, according to a new report by the Canadian Global Affairs Institute. Following the South Korea and France playbook of combining technology, diplomacy, financing and government advocacy could win contracts, the report recommends.

The recent Nepal floods, that some analysts say was triggered by glacier movements, brings home the real human and economic tragedy of the unstable nature system. Climate catastrophes are costing the world US$450 billion annually—much of it uninsured.

Glaciers in western Canada are projected to lose more than 75% of their ice, intense precipitation is projected to increase by a median estimate of 40% in Canada, and there is a greater than two-thirds chance that the central Arctic Ocean will be ice-free most Septembers, according to a new Canada government report. From water supplies and hydropower to flooding and infrastructure, the economic risks are spreading well beyond the Arctic. Twila Moon, a glaciologist at the Colorado-based National Snow and Ice Data Center, talks about what’s changing, what comes next and where there’s still room for action. Key insights from the interview:

Why glacial ice loss is not just an environmental challenge?

It’s also a financial problem. Glaciers are really valuable for drinking and agricultural water, and provide hydropower. The economic impacts include uncertainties or losses in hydropower, variability in water availability, flooding, and other hazards.

Is the focus now on adaptation?

There shouldn’t be an anticipation that we can stop ice loss or reverse it. The focus is on slowing ice loss as best we can, and understanding and adapting to the changes that have already occurred and that are underway.

Five numbers tell Canada’s climate story

Canadians will experience hotter heatwaves, more intense downpours and flash-flood risk, longer wildfire seasons and summer drought across the country, according to the government’s latest Canada’s Changing Climate Report, “unequivocally been caused by emissions from the burning of fossil fuels and human-caused land-use change.”

Five numbers tell the story of a country in the throes of dramatic environmental changes:

2.6°C Warming across Canada’s North’s over the past 75 years—faster than the national average of 2.0°C.

2x Canada’s warming rate since the 1970s compared to the global average. The Canadian Arctic has warmed three times as fast.

1°C Canada’s forecast annual average temperature increase from 2021 to 2040—no matter how global emissions change.

5°C Canada’s projected temperature rise by 2100, relative to 1850 to 1900. There’s a greater than 50% chance winter warming in Nunavut will exceed 10°C.

34 centimetres Sea-levelrise already recorded in southern Atlantic Canada and the western Arctic, compared to 20 cm since 1900.

  • With AI’s summer acceleration in full swing, John Stackhouse opted to slow down in August with a The Infinity Machine, a wonderfully human biography of Demis Hassabis, the founder of Deep Mind and one of AI’s most influential pioneers.

  • Global clean energy investment reached US$2.1 trillion in 2025, and clean electricity is growing 2.3 times faster than overall energy supply. So why aren’t emissions falling? The Energy Transition Monitor 2026 lays out three bottlenecks, including grid constraints, holding back progress.

Curated by Yadullah Hussain, Managing Editor, RBC Climate Action Institute.

Climate Crunch would not be possible without John Stackhouse, Jordan Brennan, John Intini, Farhad PanahovLisa AshtonShaz MerwatVivan SorabCaprice Biasoni, Lavanya Kaleeswaran and Joelle Schonberg .

Have a comment, commendation, or umm, criticism? Write to me here (yadullahhussain@rbc.com)

Climate Crunch Newsletter

Disclaimer

rbc_tl_disclaimer

Next week in Toronto, the Canada Investment Summit will bring together 100 global investors—managing over $1 trillion each—with Canadian leaders and CEOs. Energy, critical minerals, defence, and advanced technologies are a few of the key areas of focus.

RBC’s John Stackhouse shares what you should be thinking about on the cusp of this first-of-its-kind event.

Disclaimer

rbc_tl_disclaimer

Listen on Apple Podcasts, Spotify or Simplecast

For years, the mandate of Disruptors was simple: explore how technology is changing everything. But in 2026, a deeper dynamic is taking center stage—how geo-technology (the merger of scale, power, and innovation) is redrawing the global economic map.

In this episode, host John Stackhouse is joined by economist, writer, and Noahpinion creator Noah Smith for a candid look at global competition. Smith breaks down why modern power is no longer defined strictly by large military platforms, but by control over the physical supply chains that fuel modern technology—specifically the “Electric Tech Stack” of lithium-ion batteries, rare earth permanent magnets, and power electronics.

The conversation explores why Western industrial policy must shift from traditional growth toward strategic preservation, how AI is complementing human labor rather than eliminating it, and why middle powers like Canada, Europe, Japan, South Korea, and India must collaborate to achieve “allied scale.”

For Canadian business leaders and policymakers, this episode offers a clear diagnostic on how external pressures can serve as a catalyst for national cohesion, industrial capacity, and global trade partnerships.

Noah Smith is an economist, former Bloomberg Opinion columnist, finance professor, and the creator of Noahpinion, one of the world’s most widely read economics and technology newsletters.

As defined by host John Stackhouse, geo-technology is the merger of scale, power, and technological innovation with the strategic intent to create dominance, shaping a new global race among nation-states and tech giants.

Coined by Noah Smith, the Electric Tech Stack refers to three foundational hardware components underlying modern physical technologies: lithium-ion batteries, rare earth permanent magnet motors, and power electronics. These inputs power everything from commercial smartphones and electric vehicles to military drones and robotics.

Allied scale refers to strategic cooperation among non-hegemonic middle powers—including Canada, European nations, Japan, South Korea, and India. By coordinating trade, defense procurement, and regulations, these nations can aggregate enough industrial and supply chain scale to maintain technological independence.

You can stream all episodes on Apple Podcasts, Spotify or read transcripts and research reports directly on rbc.com/thoughtleadership

Disclaimer

rbc_tl_disclaimer

U.S. President Donald Trump put Canada “on notice” with a Venezuela pivot and plan to take control of a portion of the South American country’s oil reserves. 

But can Venezuela realistically displace the oilsands? 

Why is heavy oil so important to the U.S.?: The U.S. cannot easily replace Canadian supply: domestic production is overwhelmingly light, and heavy-crude alternatives from Mexico and Venezuela have structurally declined. 

The Venezuelan-Canadian heavy oil rivalry is not new. The two were vying for space in U.S. refineries in the 1990s and early 2000s —but that hasn’t been the case for years. Heavy crude exports from Venezuela to the U.S. has plummeted from more than 1.5 million barrels per day (bpd) in 2000 to negligible levels in recent years. However, since Washington’s toppling of Nicolas Maduro’s regime, Venezuelan crude has pushed back up, hitting  630,000 bpd in June. In contrast, Canada exported more than four-million bpd to the U.S. that month—and it remains the U.S.’s biggest source of imported crude.

The cost of boosting production in Venezuela would be staggering. It would require billions in investment over a decade, in part due to the mismanagement of infrastructure and assets in Venezuela from the mid-2000s onward, as well as the aging of many of the country’s most prolific fields, according to the RBC Commodity Strategy Team.   

A Venezuelan oil comeback “would likely be slow, expensive and politically fragile,.” wrote Shaz Merwat, RBC Thought Leadership Energy Policy Lead in a note late last year. 

Most companies are wary of returning to Venezuela—for now. Companies that previously operated in Venezuela have hesitated due to concerns including debt recovery stemming from the sanctions era. ExxonMobil and ConocoPhillips have held off returning to Venezuela after losing billions of dollars’ worth of assets in state expropriations.  

But some have jumped in. U.S. firm Chevron and Italy’s Eni are the first to return after Trump’s announcement. Chevron’s US$7 billion investment plan over the next five years could more than double its production in Venezuela to 600,000 barrels per day. 

The heavy oil fight will be more intense in the next few years. Venezuela’s supply could rise by 110,000 bpd in 2026 and another 245,000 bpd in 2027, according to the RBC commodity strategy team. With the U.S. claim that it controls 65 billion barrels of proven oil reserves in Venezuela, there’s potential for more, assuming the plan could survive legal and contractual challenges in Venezuela and the U.S., and political shifts in both countries.   

What does it mean for Canada? Canadian oil firms pumped out a record 5.35 million barrels per day in crude oil production last year, and have largely shrugged off U.S. efforts to resurrect Venezuela’s oil industry. The country’s top energy stocks have continued to rise amid higher oil prices.  

Canadian oil and gas industry is attracting U.S. and global attention. In recent weeks, firms like KKR, Apollo and Northern Oil and Gas have invested in the Canadian industry. LNG Canada’s Phase 2 project—a joint venture comprised of five global energy companies including oil major Shell—is now with the government’s Major Projects Office (MPO) for streamlined approval. 

Canada is looking to Asia. Efforts are also underway to help Canada diversify if Venezuela boost productions in a more meaningful way. The proposed West Coast Pipeline will bring one million bpd from Alberta to B.C., targetting Asia. Regardless of how U.S. policy evolves, Canadian producers are positioning themselves to secure diversified market access and greater resilience, amid the rising competition.  

Canada and the U.S. traded barbs: U.S. Treasury Secretary Scott Bessent said his country was “not at war” with Canada, mocking the threat it could pose with “submarines from the Edmonton mall.” Prime Minister Mark Carney said Americans should “stop doing memes, stop throwing shade, stop trying to be tough and start being serious.”  

Republicans backed Trump’s trade war: Republican members of Congress met with U.S. Trade Representative Jamieson Greer this week, and generally expressed support for the president’s trade strategy, blaming Carney for walking away from negotiations.  

Global finance ministers and central bankers met at the G20: China was the lone country that rejected parts of a joint statement that was released following the summit, including a paragraph that said countries would “take steps to eliminate non-market policies and practices.”  

The Canada Investment Summit draws near, as trade tensions with U.S. loom: Carney and top Canadian CEOs plan to showcase energy, critical minerals, defence and advanced technologies at the investment summit, according to a report. 

Disclaimer

rbc_tl_disclaimer

After talks between Canada and the U.S. collapsed, U.S. President Donald Trump slapped 50% tariffs on more than 500 Canadian goods—amounting to 5% (~US$20 billion) of total exports to the U.S. Canada’s response:  dollar-for-dollar retaliatory tariffs.

Our colleagues in RBC Economics analyzed the impact of the new U.S. tariffs:

  • 5.5% — The average tariff rate on U.S. imports from Canada, up from ~3%, but still below the average U.S. tariff rate on imports from all countries.  

  • 0.4% —Share of Canadian GDP directly exposed to new tariffs. While more than 80% of exports will remain tariff-free under the rules outlined in the Canada-U.S.-Mexico Agreement (CUSMA), the impact on the sectors that have been targeted will be significant.   

Read the entire RBC Economics report here

  • B.C., Quebec, and Ontario are facing the brunt of the impact of the latest tariffs, with ~10-15% of their U.S. exports affected by the new levies.  

  • Electrical equipment, plastics and packaging, and furniture and lighting make up the bulk of the affected goods.  

  • The Prairies and Atlantic provinces, which largely export key goods that the U.S. relies on such as energy, potash and grains, are largely spared. 

Many of Canada’s primary agri-food exports, such as grains, oilseeds, major protein and livestock, and processed goods were excluded from the Section 338 list.  

However, several important sectors are impacted: 

  • Dairy: The sector was targeted meaningfully, but unevenly. The schedule applies to dozens of products most aimed at whey, milk/cream concentrates, and several milk-protein ingredient products. The most significant product family affected is whey, of which more than $100 million worth of products were sold to the U.S. in 2025. Of note, yogurt, butter, and cheese are not included in the latest tariffs. 

  • Honey, Sugars, Syrups: Natural honey was targeted, which could have severe impacts for beekeepers. Approximately $30 million worth of honey—more than 50% of its exports—went to the U.S. last year. Other syrup and sugar products such as glucose and glucose syrup ($100 million exported to U.S.) are included, but maple syrup ($540 million), was spared.  

  • Horticulture, Botanicals, Essential Oils: Most bulbs, cut flowers, and other live plants are impacted, along with a comprehensive inclusion of essential oils. These are consequential, as $155 million worth of cut flower and flower buds were exported to the U.S. in 2025, and $52 million of bulbs and tubers. The value of essential oil exports to the U.S. was around $55 million, with 80% of exports going south of the border.   

  • Alcoholic beverages: The tariff schedule contains 63 lines classified as alcoholic beverages and is a substantial, broad sectoral hit. It covers more than $1.2 billion of the major beer, wine, other fermented beverages and distilled spirits families.  

With more than 60% ($60 billion) of Canadian agri-food sector exports reaching the U.S. annually, Americans have come to depend on Canada for food security and affordability. While these tariffs are severe for the sectors impacted, and will drive up prices for U.S. consumers, they do not change the macroeconomic picture for Canadian agriculture. 

On Monday, Trump announced that he will double the tariffs on the Canadian auto industry to 50%, levying the punishing rate on cars, trucks, and parts, in addition to steel. In his post, the president said that Americans don’t need Canada.  

The North American auto industry is highly integrated; parts cross borders across North America up to eight times before a vehicle is assembled. Such tariffs would devastate Canada’s auto industry more than reciprocal tariffs would hurt the U.S. sector—but in absolute terms, the auto sectors on both sides of the border will be damaged by an escalating trade war.  

  • The breakdown: Auto trade between Canada and the U.S. is $100 billion (across assembly, parts, and body & trailer). The U.S. runs a $3 billion surplus. Whatever trade is forfeited with Americans, they stand to lose as well.  

  • Production hit in the U.S.: While most of the 10-11 million vehicles that are assembled in the U.S. are sold domestically, about 15% are exported, with Canada serving as the largest export market by far—more than the next 10 export markets combined. Closing the door on American imports would hit a channel equal to 7-10% of annual U.S. production. 

  • Canadians are big car buyers: Only Americans buy more cars than Canadians on a per-capita basis. Canadians spend nearly $110 billion annually on cars, with 90% of those vehicles built abroad. Canadians also have a penchant for heavier, higher-value vehicles. The Ford F-Series have been the best-selling vehicle in Canada for 15 consecutive years.  

  • Tariffs make vehicles more expensive: Auto tariffs on Canada and Mexico alone totalled $1,600 for every vehicle assembled in the U.S.—and that doesn’t account for steel and aluminum tariffs. Tariffs against Canada and Mexico cost North American automakers and suppliers $12.5 billion in the past year. 

  • The U.S. is losing market share: While the Canadian market is small relative to the U.S., it is still the largest global buyer of American-made cars and trucks. In the decade before Trump imposed tariffs on the Canadian auto industry, 49% of vehicles imported to Canada were manufactured in the U.S. In the first 10 months of 2025, that number dropped to 36%, with South Korean and Mexican-made vehicles gaining share. If even higher tariffs come into effect, that trend may continue.  

Disclaimer

rbc_tl_disclaimer

Breaking the silos in the Maritimes

Canada steps up nature protection efforts amid climate onslaught

Is energy transition an illusion? An IMF working paper explores

  • The Maritimes are breaking down provincial grid silos. Premiers of New Brunswick, Nova Scotia and Prince Edward Island signed an MoU in July to develop a more integrated electricity system. Aligning regulations, investments and utilities of three of the smaller regions in Canada by spring of 2027 would be a test case closely watched by larger provinces that are also eyeing interties to share power generation and capacity. Meanwhile, Newfoundland and Labrador and Quebec signed a $70-billion clean power deal—said to be North America’s largest clean energy investment, if completed. The pact would double Newfoundland’s total power capacity, and potentially boosts Quebec’s electricity exports. Quebec will pay 6.2 cents per kilowatt-hour in the new pact, a significant jump over the decades-old deal of 0.2 cents, that had triggered a long-running dispute between the two provinces.

  • Indigenous equity in Canadian projects grew 290% in eight years. Between 2017 and 2025, the number of Indigenous-owned projects starting operations grew from 10 to 39, while at least 47 Indigenous-owned projects will come online across Canada this year, according to the Indigenous Equity Monitor. Nearly 87% of the 546 Indigenous-owned projects are power and utilities and carbon capture, highlighting First Nations’ role in clean energy. The experience in project development arms communities with experience, funding and skills to participate in several energy developments on the horizon.

  • Canadian Crawford Nickel mine just got the greenlight from the Major Projects Office. The Timmins mine (featured in the 2025 Climate Action Report) is expected to be the biggest mine in the world when completed in 2029. It’s a flagship development in a Western nation for a material critical for EV batteries. Nickel production is currently dominated by Indonesia, which carefully regulates quota and exports, and Chinese processing companies. Demand for nickel is set to grow 65% this decade alone.

Nimbyism is coming for AI data centres.Oakville, Mississauga, and New York state are among North American jurisdictions looking to protect their power infrastructure from AI.

The transformative (and disruptive) technology is an energy—and capital—sponge. The communities are also seeking greater transparency on water, heat and air pollution associated with data centres, in addition to how these power-hungry projects impact Canadians provinces’ efforts to decarbonize their grids.

Here’s the scale of capital and energy AI needs:

US$715 billion: Capital expenditure of hyperscalers in 2026 globally—that’s more than the US$600-billion invested in the entire U.S. energy sector in 2024, according to the International Energy Agency.

US$200 billion: The amount AI companies tapped in debt markets to fund expansion. They are set to become the largest issuers of corporate debt going forward.

Five to 10 years. Wait times for grid connection in many jurisdictions globally. In Canada it averages six years.

10% of total electricity demand growth globally: AI power consumption will more than double to 950 TWh by 2030 from current levels. In the U.S, data centre electricity consumption would account for 45% of all growth.

Data centres will likely lean more on fossil fuels by 2030. Around 252 TWh will be powered by low-carbon energy sources, including nuclear. However, that will be eclipsed by fossil-fuel powerhouses coal and natural gas, accounting for around 270 TWh by 2030, with implications for emissions, the IEA forecasts.

Agentic AI is a power sponge. A single, context-rich query eats up 50 watt-hours (similar to charging a smartphone 2-3 times),compared to 0.05Wh for a text query (medium language model).

The AI frenzy could raise emissions. AI models raised net annual CO₂ emissions by 0.47–1.8 gigatonnes (1.2–4.8% of 2024 global energy-related CO₂ emissions), according to a study in Nature. Renewable gains must exceed fossil gains by 4–5X for net emissions to reach breakeven levels.

Big Tech has gone dark on its emissions footprint. Multi-billion-dollar AI start-ups have no obligation to report their carbon footprint, while several listed Big Tech firms and investors have also cooled on their environmental disclosures as they power through the AI frenzy.

Clash between sovereignty and power. The Ontario province unveiled a playbook last week that aims to maintain Canadian data sovereignty but also ensure that deep-pocketed hyperscalers are paying higher prices and get no financial support.

Ottawa’s new Expert Taskforce on Natural Capital Accounting and Nature Financing is among the first critical steps to attract more investment in protecting nature amid an onslaught from extreme weather. It follows the launch of a federal strategy to protect nature in the spring, aimed at increasing conservation areas, aligning economic growth with nature stewardship, and mobilizing private capital.

These efforts come after Canada missed, by a long shot, its 2025 target to protect and conserve 25% of terrestrial land and inland water and leaves a very narrow path for its 30% of land conservation by 2030 goal.  The failure was highlighted in the 2025 Report of the Commissioner of the Environment and Sustainable Development on behalf of the Auditor General of Canada.

There are more reasons to be optimistic about the approach to 30×30 than previous conservation efforts, says Wilson Fink, Director of Agriculture.

  • Pillar 1-protecting nature. Acknowledging the need for an all-of-Canada approach. Protecting 30% of land is difficult when only 6% of Canada’s land is federally owned1. The rest is controlled by provinces, Indigenous governments, and private landowners. Collaboration would be key.

  • Pillar 2—building Canada well. The commitment to be data driven and “enable integrated conservation, carbon accounting, and project planning,” to facilitate funding for nature.

  • Pillar 3—mobilizing capital. It’s the least developed of the three, but perhaps the most consequential. There is global momentum to build nature frameworks that can accommodate more substantial investments, but they need harmonization and less risk to scale successfully. This is where the taskforce will spend most of its time.

  • “We want to see carbon markets take their rightful place in the climate finance architecture,” said Mura Kurum, Turkey’s environment minister and president of COP31, hosted by his country in November.

  • Climate wonks are abuzz with a new International Monetary Fund working paper by Jean-Baptiste Fressoz, et al, on how new energy sources are additive not substituting old energy sources, effectively calling energy transition an illusion. Some say that’s not entirely true, pointing to the demise of whale oil.

  • Canadair’s water bombers “are the backbone of most European firefighting operations,” according to Neil Sweeney, De Havilland Canada’s vice-president of operations. As wildfires across North America and Europe destroy picture-perfect forests and foliage, the once-dormant Canadair line is being revived.

  • “Ottawa’s update on its National Adaptation Strategy documents a good deal of activity—but little sign that any of it is actually reducing the escalating climate and extreme weather risks that Canadians face,” said Ryan Ness, Director of Adaptation at the Canadian Climate Institute, in response to Canada’s 2026 National Adaptation Strategy Progress Report.

Curated by Yadullah Hussain, Managing Editor, RBC Climate Action Institute.

Climate Crunch would not be possible without John Stackhouse, Jordan Brennan, John Intini, Farhad PanahovLisa AshtonShaz MerwatVivan SorabCaprice Biasoni, Lavanya Kaleeswaran and Joelle Schonberg .

Have a comment, commendation, or umm, criticism? Write to me here (yadullahhussain@rbc.com)

Climate Crunch Newsletter