

 EN


Bottom Line:
The September employment report may have underwhelmed market expectations, but that doesn’t mean the labor market is weak. The 29,000 payroll gain is quite healthy in the context of our breakeven estimate of 20,000 jobs per month. Gains were broad-based, and the declines more likely reflect retirements than layoffs, especially in sectors with an older workforce (e.g., the median worker age in financial services is 44.2 years compared to 42.1 years overall). Despite a slowdown in health care hiring, strength was driven by the goods sector, which continued to recover from the post–Liberation Day layoffs earlier in 2025.
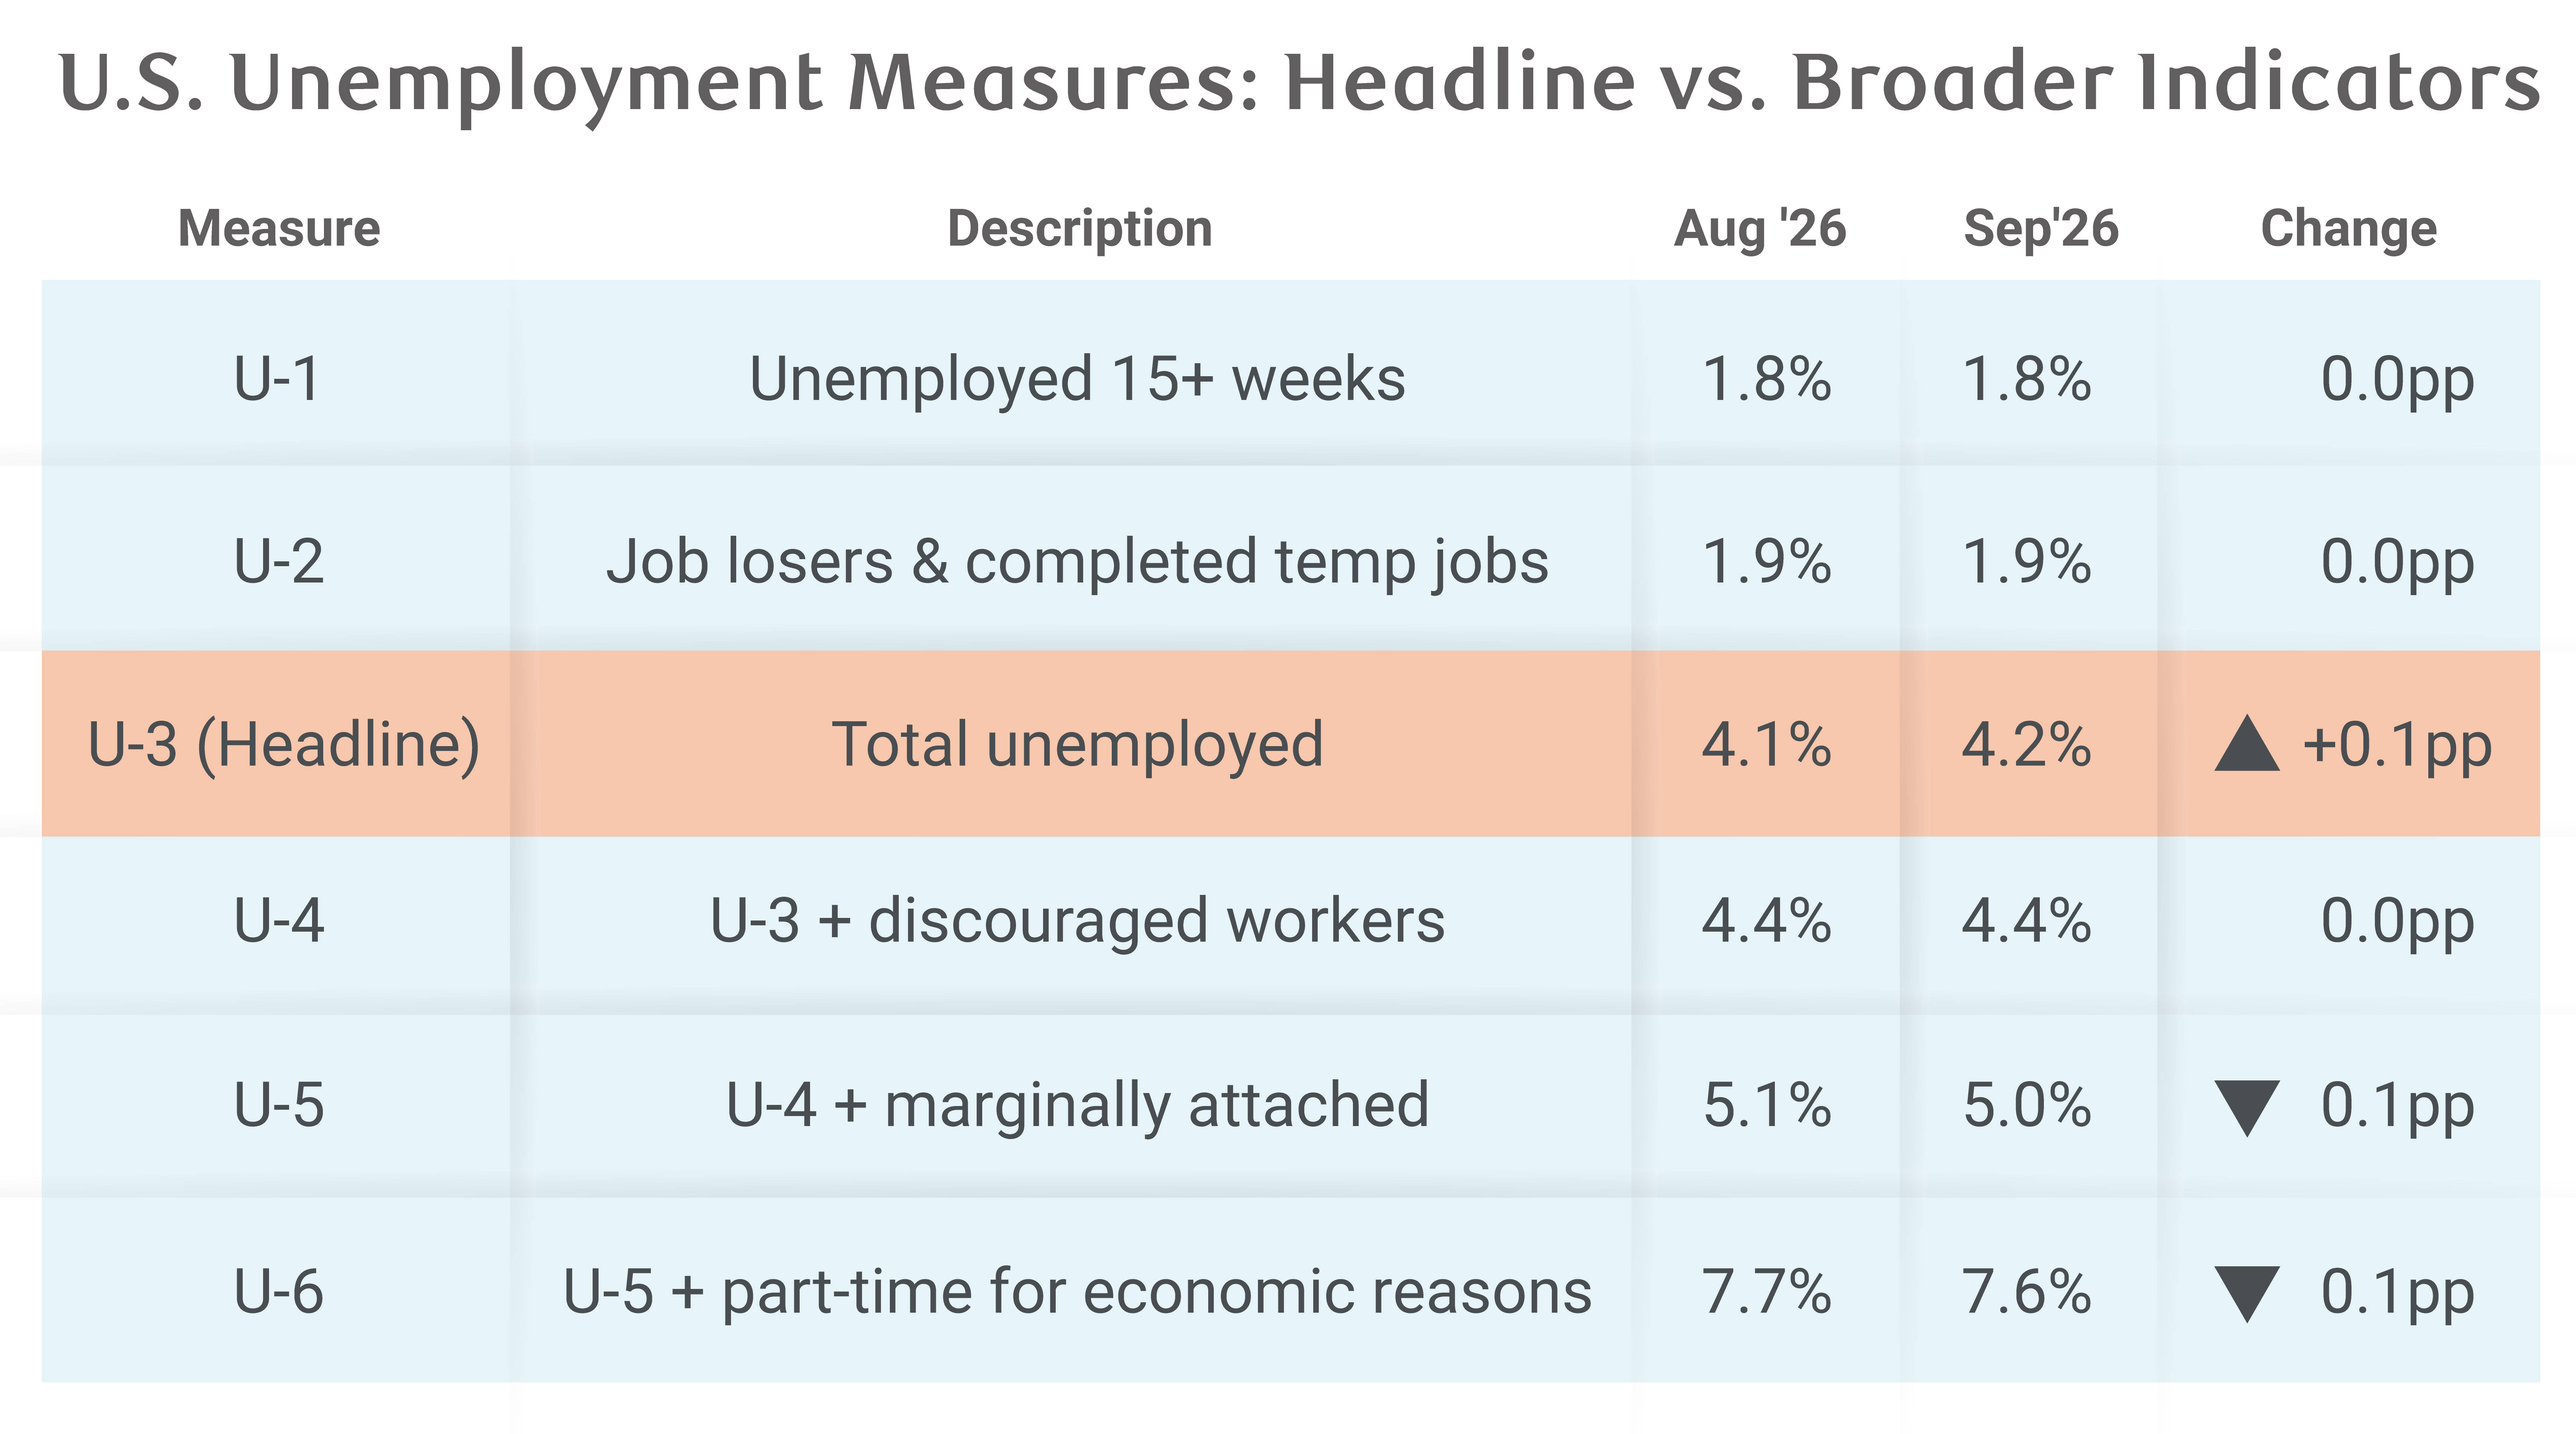
The unemployment rate ticked up to 4.2%, though the move was largely a rounding artifact (4.175% in September versus 4.141% in August). The jump in labor force participation to 61.8% contributed to the very small rise and is not concerning. In fact, every measure of unemployment outside the headline U-3 held steady or improved.
The more meaningful indicators we are watching for signs of weakening demand show that tightness persists:
-
Aggregate hours in the private sector are accelerating, meaning more workers are working more hours.
-
Part-time workers for economic reasons as a share of total employment sit near the all-time low, signaling minimal slack.
-
The job-finding rate ticked higher, and broader measures of slack improved across the board.
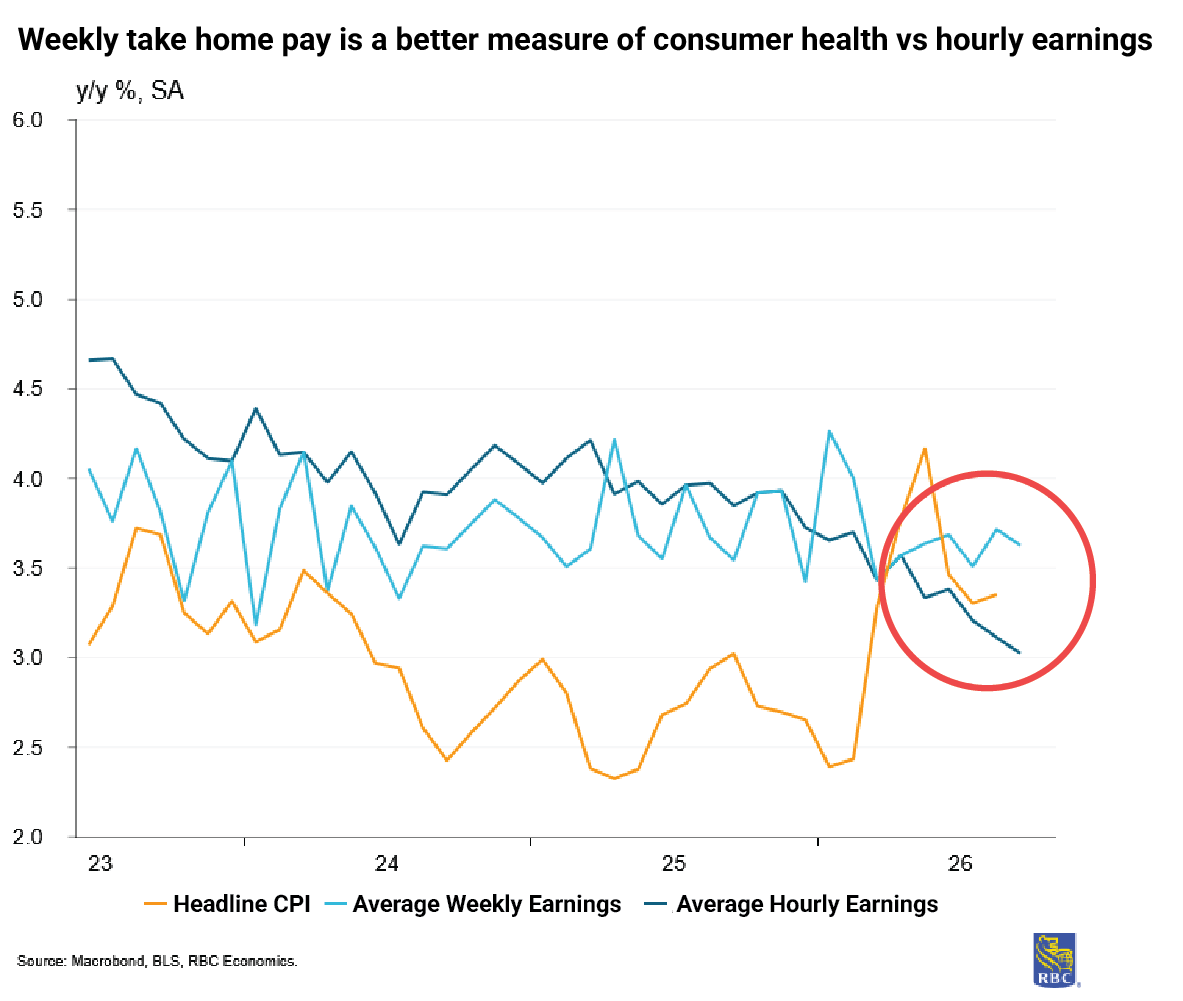
On the consumer front, we continue to emphasize that average hourly earnings can be misleading. Yes, the month-over-month reading ticked down to 0.1%, but it is subject to noise from compositional effects driven by sector-level hiring and demographics. Moreover, personal spending and the saving rate were both revised notably higher this week, even though real average hourly earnings have trended in negative territory this year. What is also true is that workers are working more hours and taking home more money in their paychecks every week. In real terms, May was the only month this year when average weekly earnings declined — a pattern that better aligns with the upward revisions noted above.
The real challenge in the U.S. economy is the inflation pipeline heating up, not the labor market backdrop.
About the authors:
Mike Reid is Head of US Economics at RBC. He is responsible for generating RBC’s U.S. economic outlook, providing commentary on macro indicators, and producing written analysis around the economic backdrop.
Carrie Freestone is a Senior US Economist at RBC. She is responsible for generating RBC’s US economic forecasts across GDP, employment, and inflation, and providing macro commentary through publications, presentations, and the media.
Imri Haggin is an US Economist at RBC, where he focuses on thematic research. His prior work has centered on consumer credit dynamics and treasury modeling, with an emphasis on leveraging data to understand behavior.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

