

 EN


Next week our focus is on the October jobs report, and we expect it will reinforce our view that that the labor market remains tight. We forecast 42K jobs were added to payrolls in October and expect the unemployment rate held steady at 4.2%.
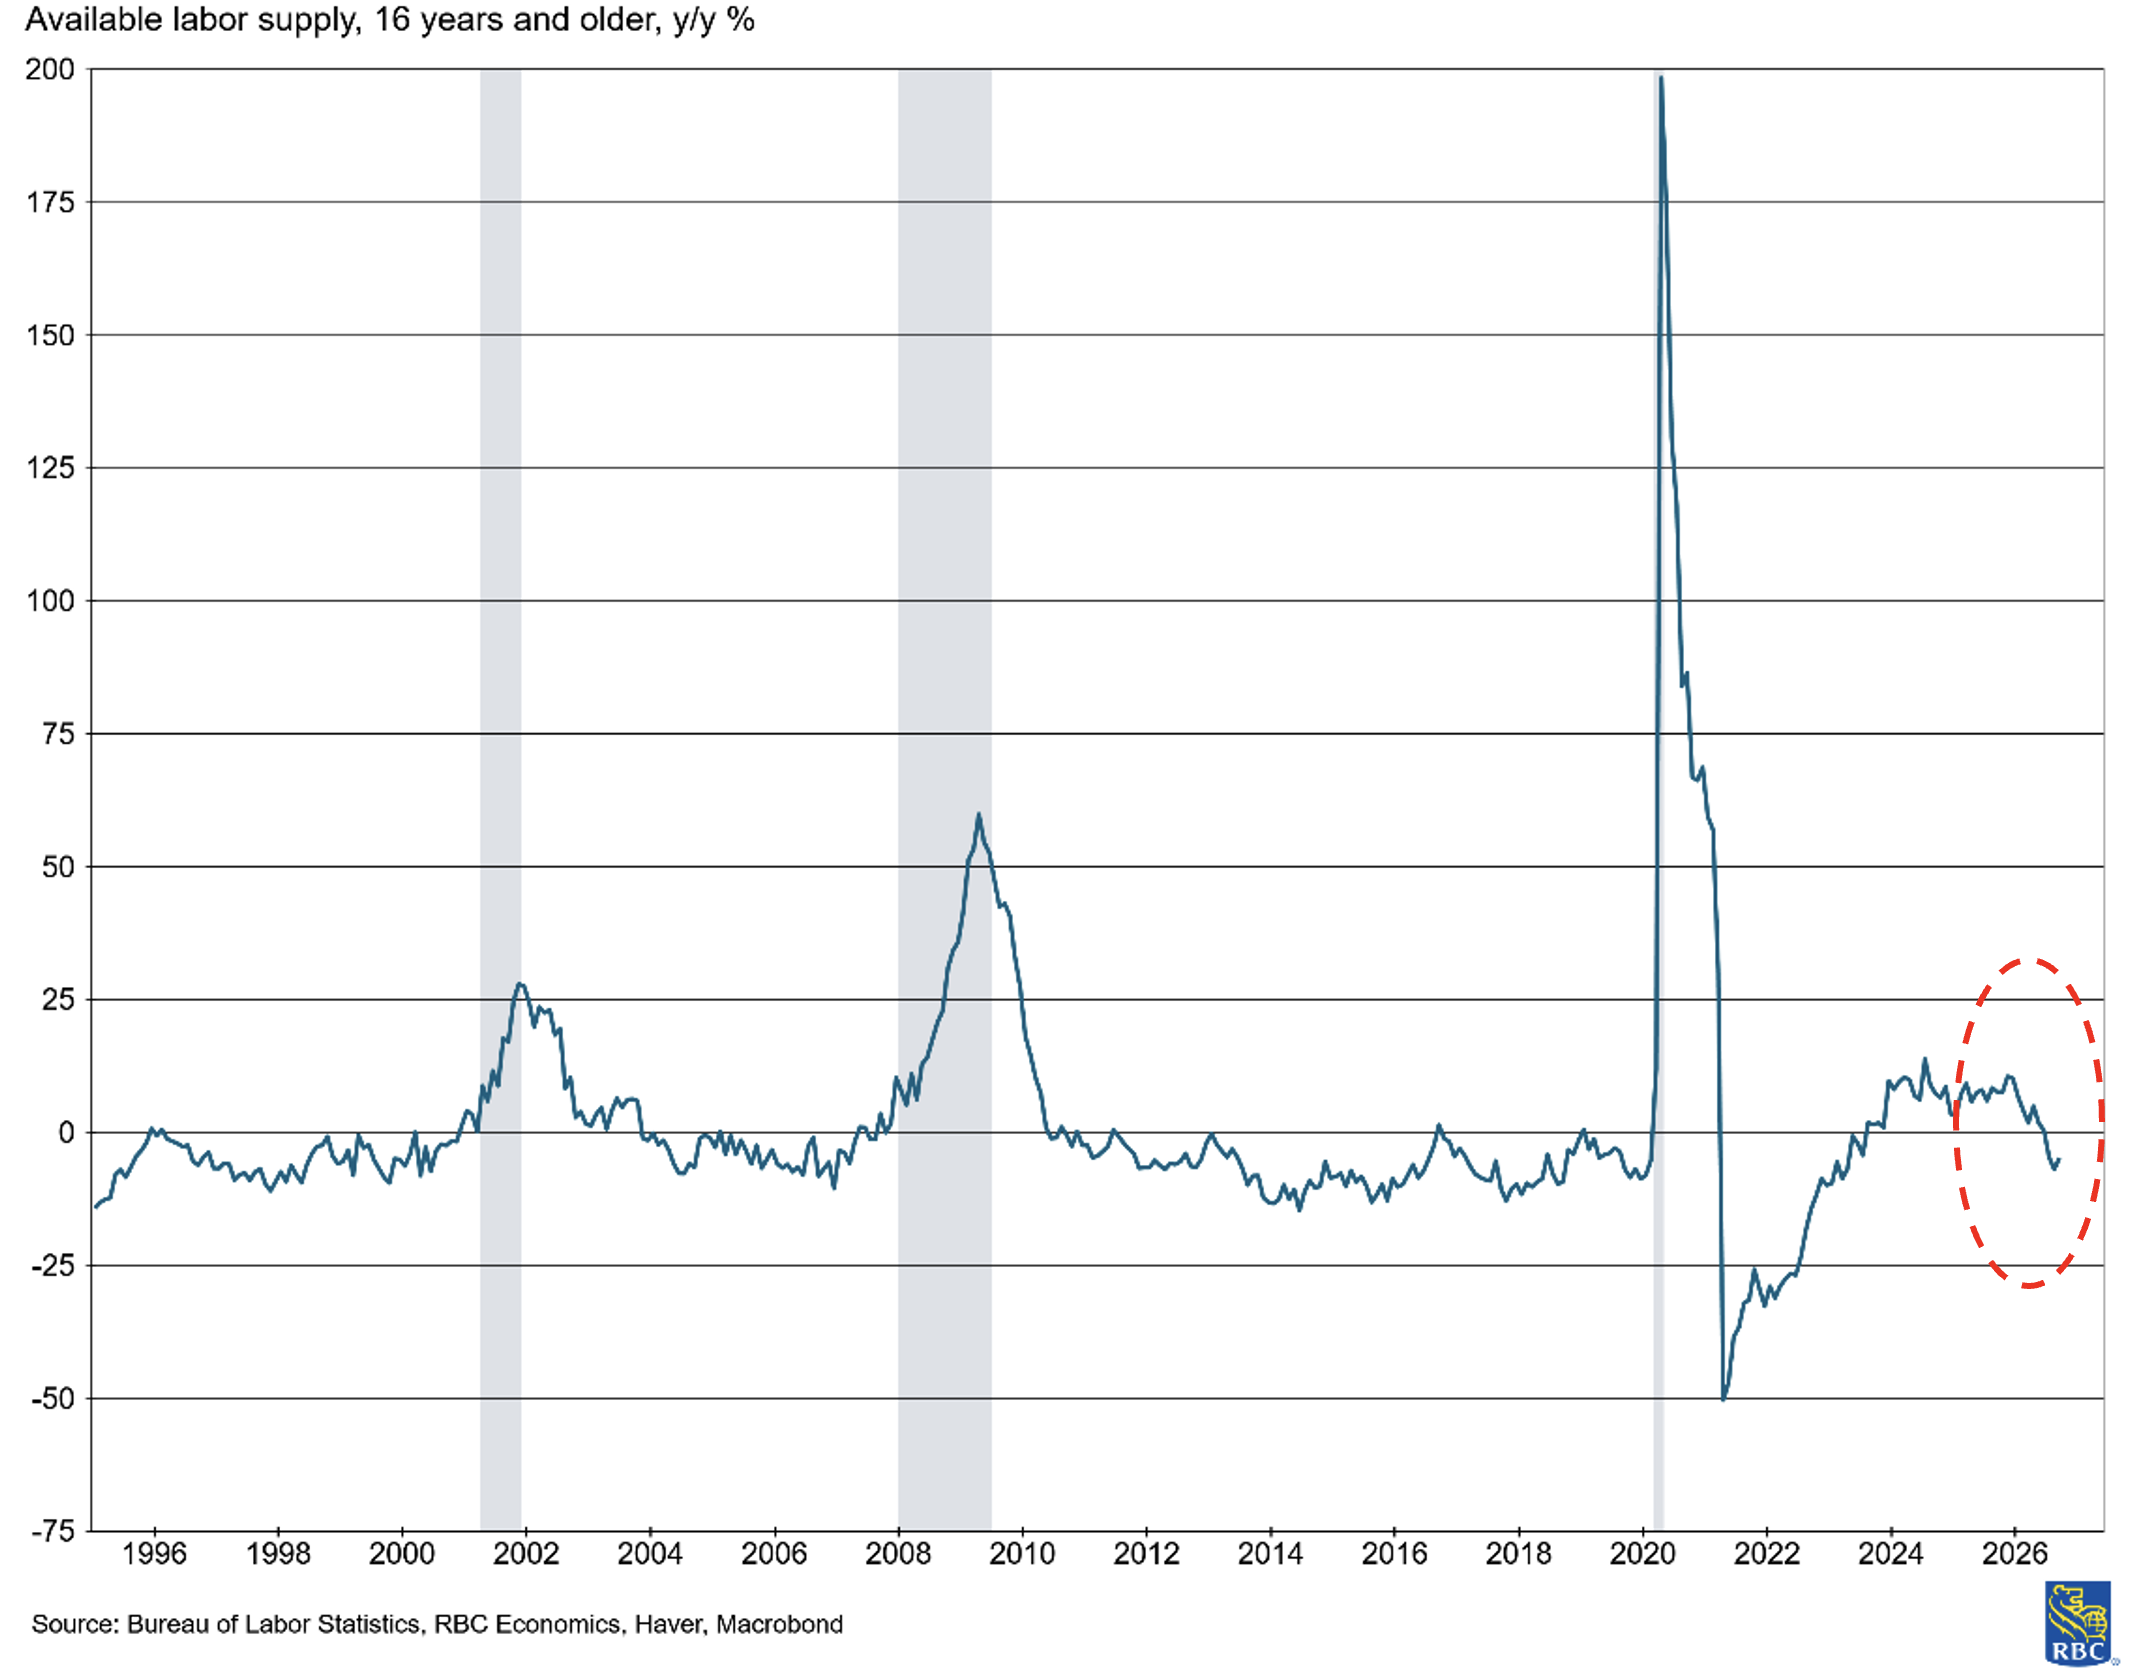
Initial jobless claims have moved sideways, ticking slightly lower between the September and October reference weeks, which is why we see minimal risk of the unemployment rate rising from layoffs. Importantly, the underemployment rate is falling, with fewer marginally attached workers and fewer working part-time for economic reasons. The September NFIB survey further highlighted that more small business owners are citing “labor quality or availability” as their top concern.
Month-to-month net new job creation is not as good a gauge of labor market health as the unemployment rate, especially since breakeven employment is exceptionally low. But the BLS diffusion index points to more sectors hiring. For October, we expect health care and non-residential construction will support the majority of hiring. We also expect transportation and warehousing to add jobs ahead of the holiday shopping season following Amazon’s announced plans to create 300,000 new roles – up 20% from what is typical for recent seasonal hiring.
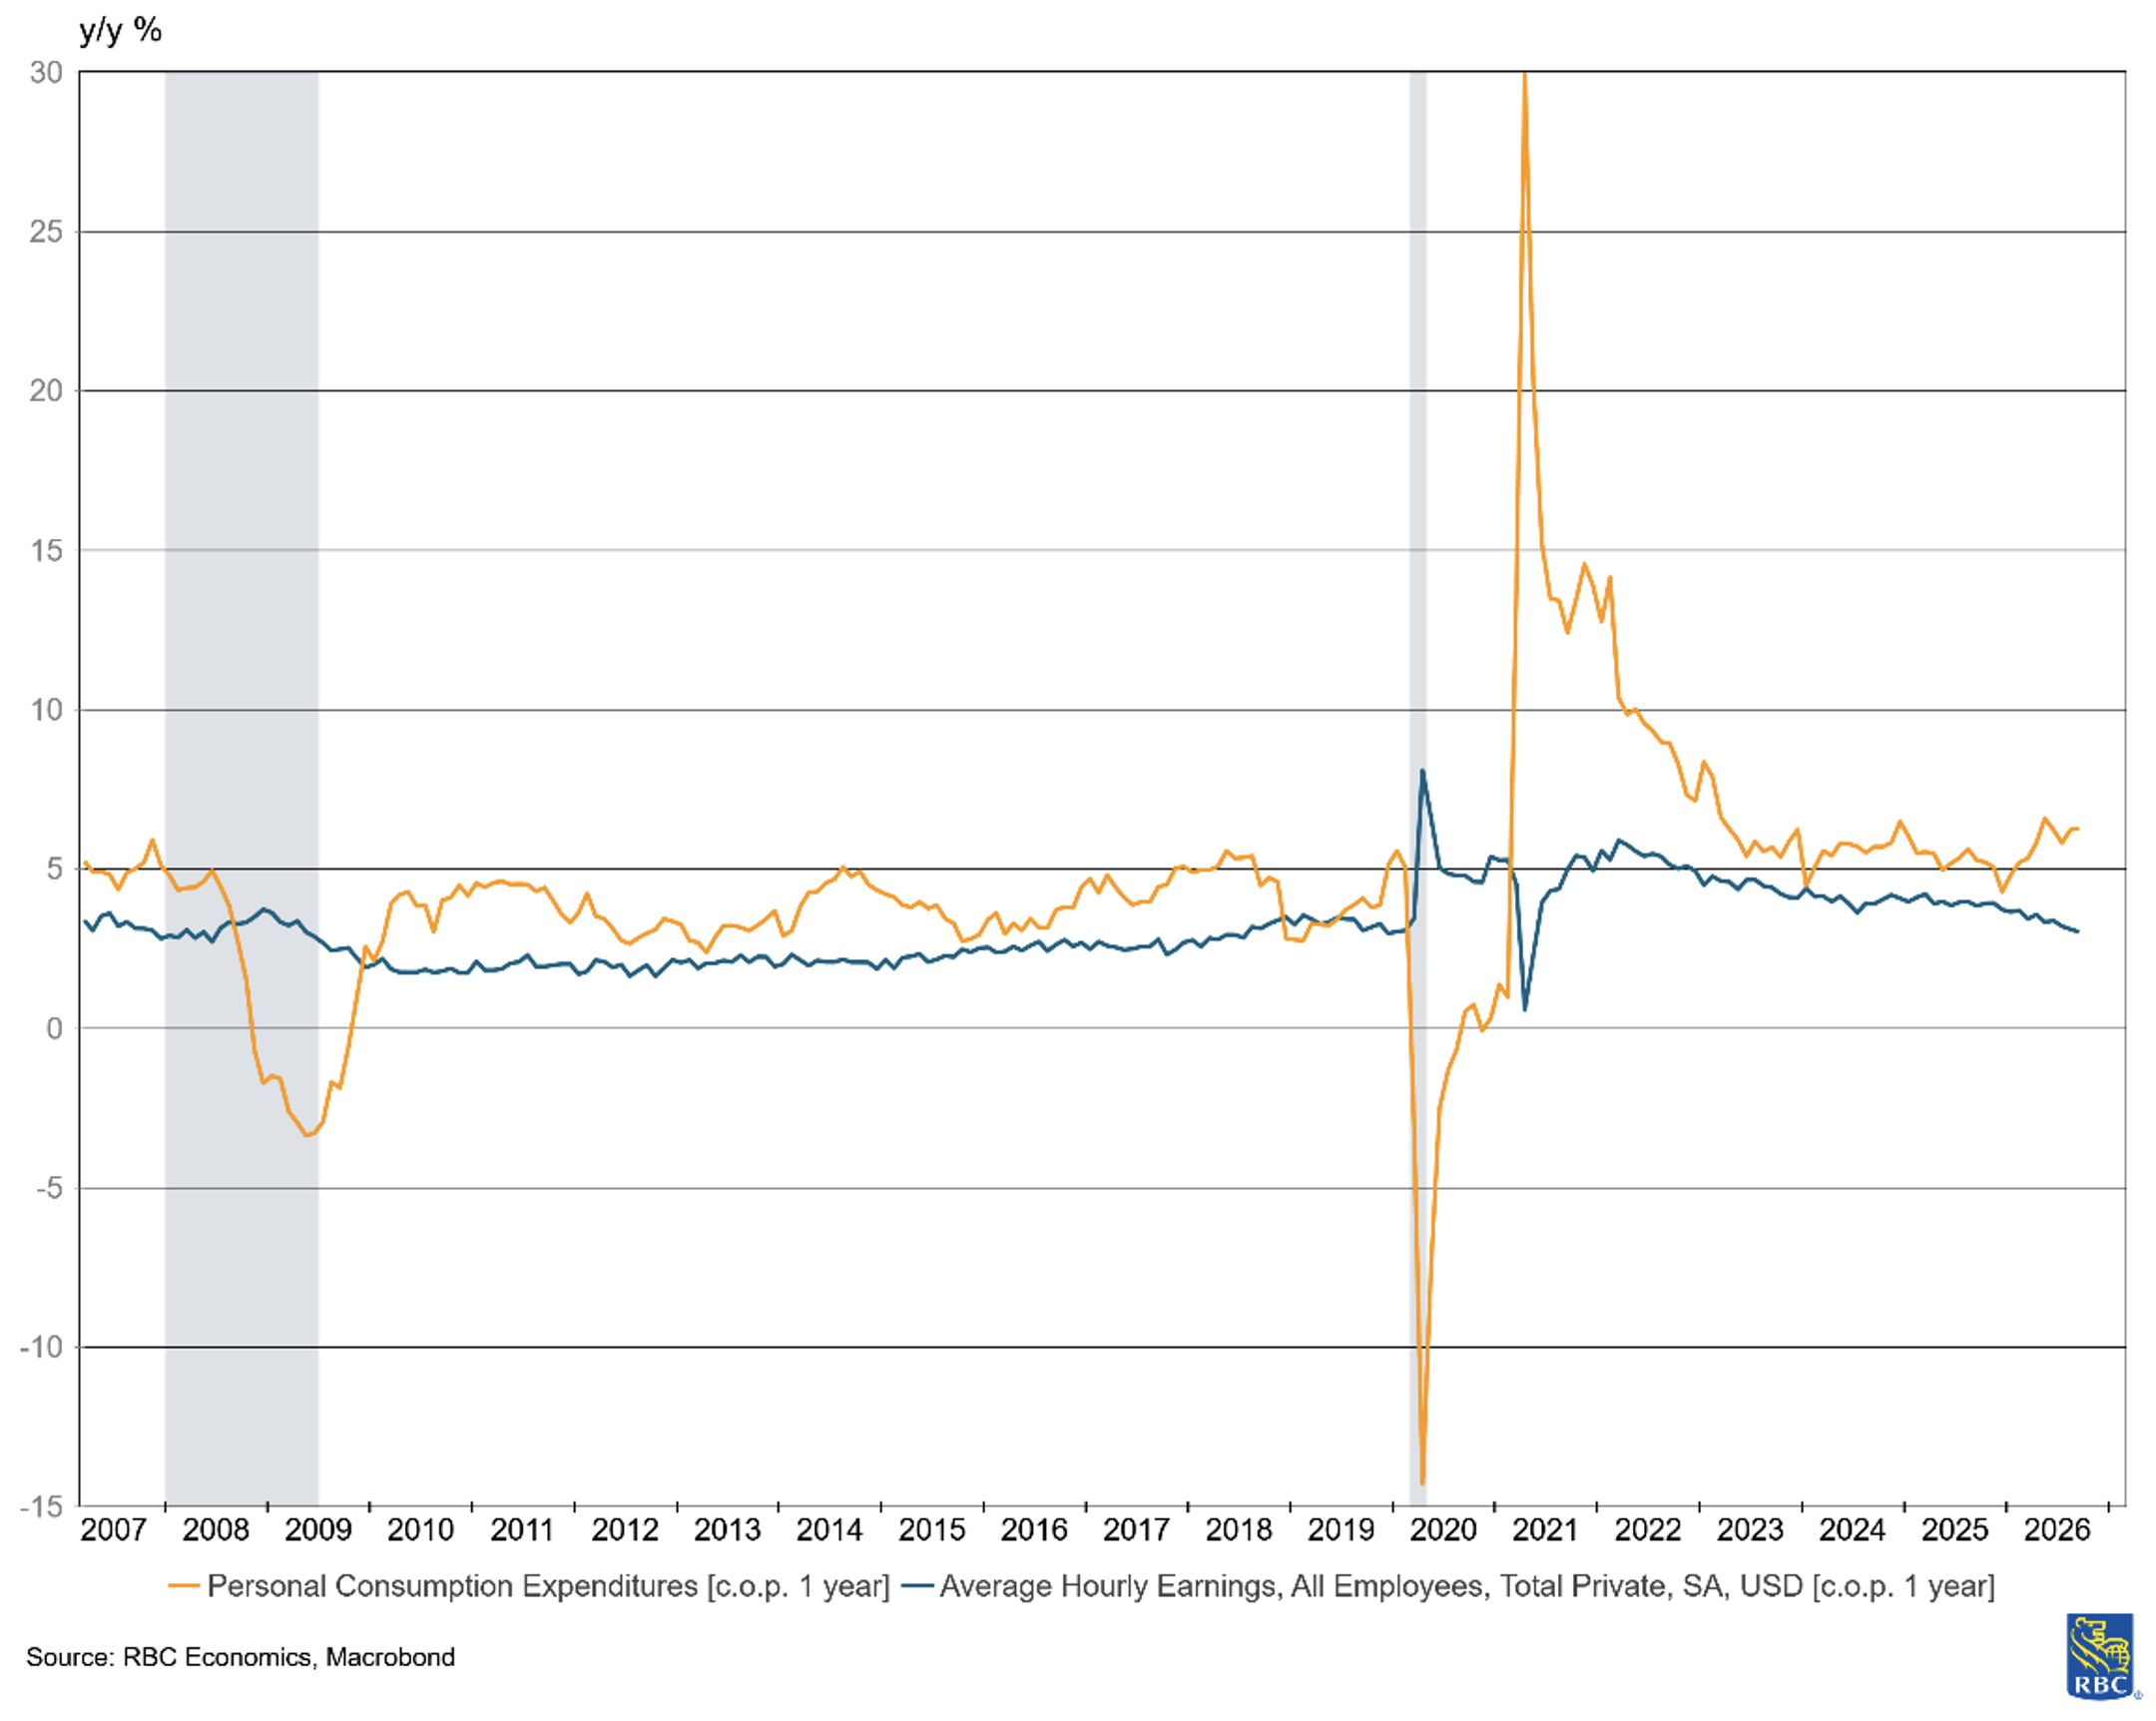
We expect average hourly earnings rose +0.3% m/m in October, holding the y/y pace steady at 3.0%. Importantly, we view the declining pace of wage growth as a compositional effect, not a story of a weakening labor market. As Baby Boomers retire and are replaced by lower-tenure, lower-earning cohorts, there is a demographic skew on top of the typical sectoral hiring that creates noise in this measure. Average weekly earnings, on the other hand, look notably stronger, reflecting the fact that employees are working more hours. If firms faced margin compression — and September PPI data does not suggest that is the case — we would expect to see hours worked fall. Instead, hours worked have risen over the last year, a solution to a limited supply of workers.
We also get consumer credit data next week, which is a growing concern. We forecast consumer credit grew by $16.8 billion in September. While there is little the Fed can do to tame inflation that is not especially rate sensitive. But higher interest rates will hurt lower-income households with rising debt exposure. Since the bulk of consumer demand is driven by higher earners and Baby Boomers, we do not expect a consumer credit crack will entirely derail spending, but we still see scope for moderating consumption if the Fed hikes beyond our expectations.
Labor market tightening is being driven by a shrinking labor supply
AHE growth is not a good predictor of consumer spending
About the authors:
Mike Reid is Head of US Economics at RBC. He is responsible for generating RBC’s US economic outlook, providing commentary on macro indicators, and producing written analysis around the economic backdrop.
Carrie Freestone is a Senior US Economist at RBC. She is responsible for generating RBC’s US economic forecasts across GDP, employment, and inflation, and providing macro commentary through publications, presentations, and the media.
Imri Haggin is an US Economist at RBC, where he focuses on thematic research. His prior work has centered on consumer credit dynamics and treasury modeling, with an emphasis on leveraging data to understand behavior.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

