

 EN


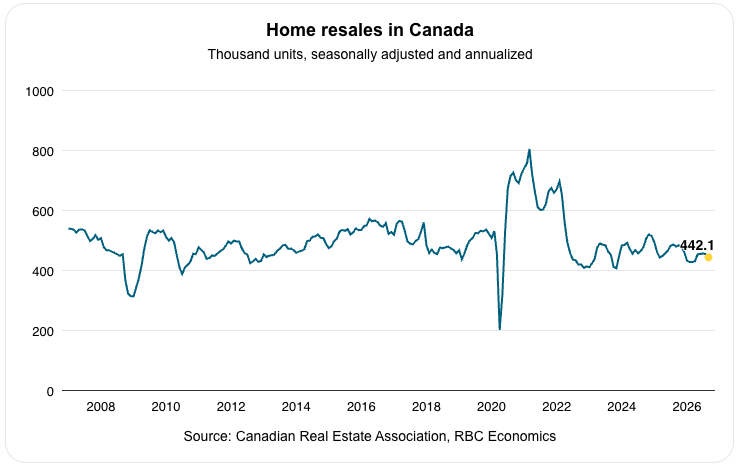
Canada’s housing market took a visible step backward in September after months of tentative progress. Resales fell 2.3% from August seasonally adjusted, interrupting the improvement emerging this spring.
Two forces converged to keep buyers on the sidelines. The intensifying Canada-U.S. trade war rattled fragile consumer confidence that was starting to rebuild, while anticipation of Bank of Canada interest rate increases pushed fixed mortgage rates slightly higher, prompting prospective homebuyers to pause. Labour markets softened simultaneously adding to buyer hesitation.
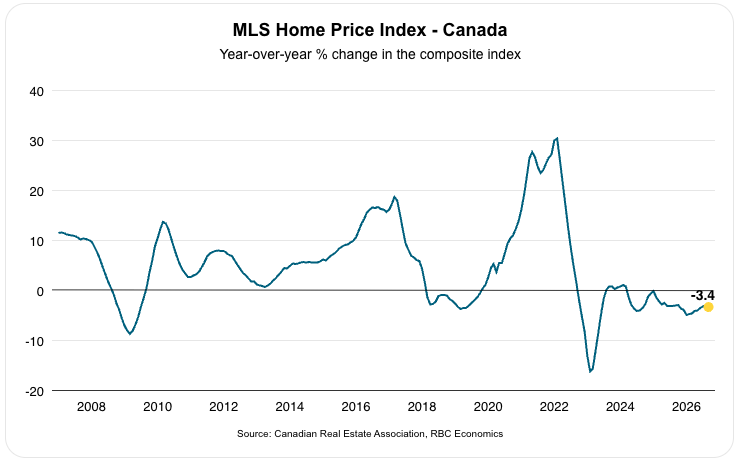
Pullback in buyer activity accelerated price declines for the first time in seven months. The MLS Home Price Index tumbled 0.4% from August and 3.5% below a year ago—rolling prices back to early 2021.
New listings also retreated, falling 1.8% month-over-month seasonally adjusted, with lower supply offering some protection against steeper price falls.
Rates rising but without the intensity of 2022
September’s decline reflects the bumpy recovery we’ve been expecting as households navigate shifting trade policy and rising borrowing costs. Bond yields have already begun climbing in anticipation of BoC rate hikes, pushing fixed-rate mortgage rates higher before the central bank moves.
That said, the scale of this cycle matters. We look for the BoC to hike the overnight rate by a total one percentage-point in 2027—a far cry from the last tightening cycle when the rate shot up from 0.25% to 5% in just over a year. Moreover, those rate hikes are likely still contingent on an improving Canadian economy.
While rate hikes would certainly still squeeze affordability for some would-be buyers this time around, the gradual pace shouldn’t trigger the same magnitude of pullback in post-pandemic resales as before.
Still, September made clear the market will face rough patches as rates climb and trade uncertainty lingers.
Poor affordability catches up to outperforming markets
Ontario and British Columbia continue to experience more buyers retreating as stretched affordability, slow population growth, and low consumer confidence weigh on demand.
In the Greater Toronto Area, resales fell 5.3% month-over-month, while Greater Vancouver declined 6.2%. Victoria’s market was even more severe with resales collapsing 25% month-over-month—the sharpest decline in the country.
The fall didn’t have a dramatic effect on prices though. New listings continued to slide for most Ontario markets and Vancouver—keeping supply and demand relatively stable.
The opposite is unfolding in Quebec—joining the affordability reckoning late. Resales have plateaued while new listings have crept higher throughout 2026, finally putting downward pressure on prices after years of resilience. Montreal is showing the first signs of strain, while Quebec City remains mixed, but vulnerable. We expect prices to soften further as future rate hikes squeeze buyers, pricing them out of markets where affordability has seldom improved from all-time worst levels.
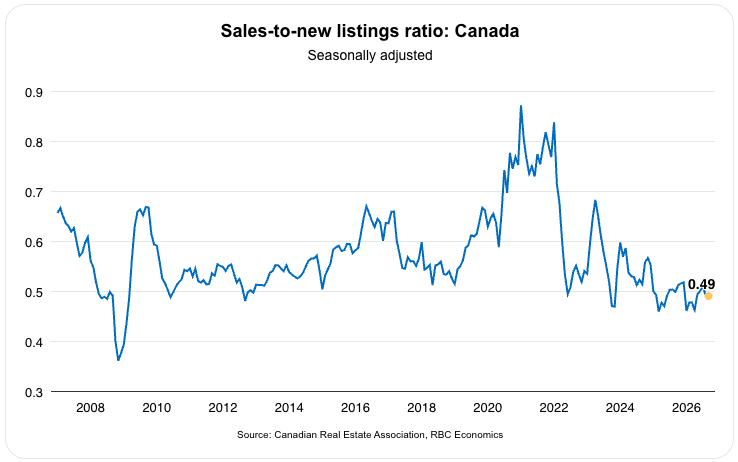
Parts of the Prairies are seeing market dynamics loosen as waning resales in Winnipeg, Regina, Saskatoon and Edmonton allow the sales-to-new listings ratio to float lower—though still favouring sellers in most cases.
Atlantic Canada presents a mixed picture. Like Quebec, some markets show signs of tapping out as prices remain near record levels, while Halifax and Newfoundland and Labrador have seen resales climb since April—pointing to stabilization after weakness since late 2025.
Two steps forward, one step back
Despite September’s stumble, the foundations for gradual stabilization remain in place heading into 2027.
We see demand gaining ground as labour markets regain footing, and pent-up demand begins to seep out. That said, the path won’t be linear. Trade policy uncertainty continues to weigh on household and business confidence, while geopolitical tensions keep energy costs unusually high.
While governments are providing fiscal support and businesses are adapting to shifting conditions, the U.S. administration’s unpredictable tariff policy leaves many uneasy about impacts on jobs and income. In this environment, we expect the housing market recovery will continue, but gradually with ups and downs.
About the author:
Rachel Battaglia is an economist at RBC, providing forecasts for the Canadian provincial economies and analyzing key trends in housing and consumer spending.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

