

 EN


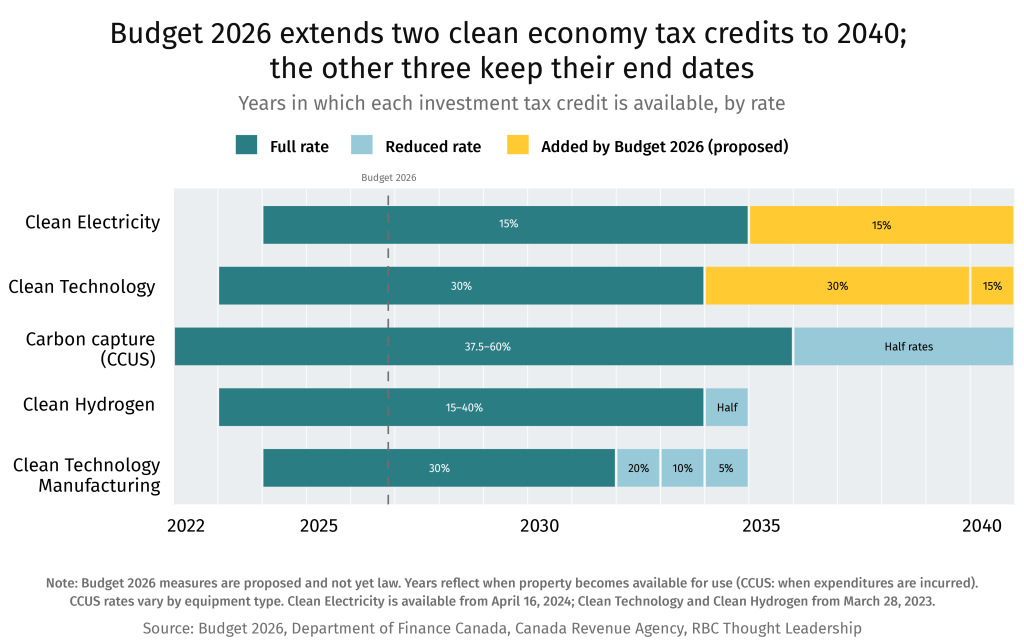
The proposed extension of two of Canada’s clean economy investment tax credits (ITCs) by six years, to the end of 2040, is the largest piece of the more than $50 billion Ottawa says it is committing to build out Canada’s electricity grid.
Ottawa says that the extension will enable the certainty that longer-term projects require. Hydroelectric dams, transmission lines, and wind farms that take years to plan and build can still qualify if they come online in the late 2030s. Utilities building major transmission lines within their provinces would also gain access to the Clean Electricity credit, and projects using Canadian-made equipment could earn a higher rate.
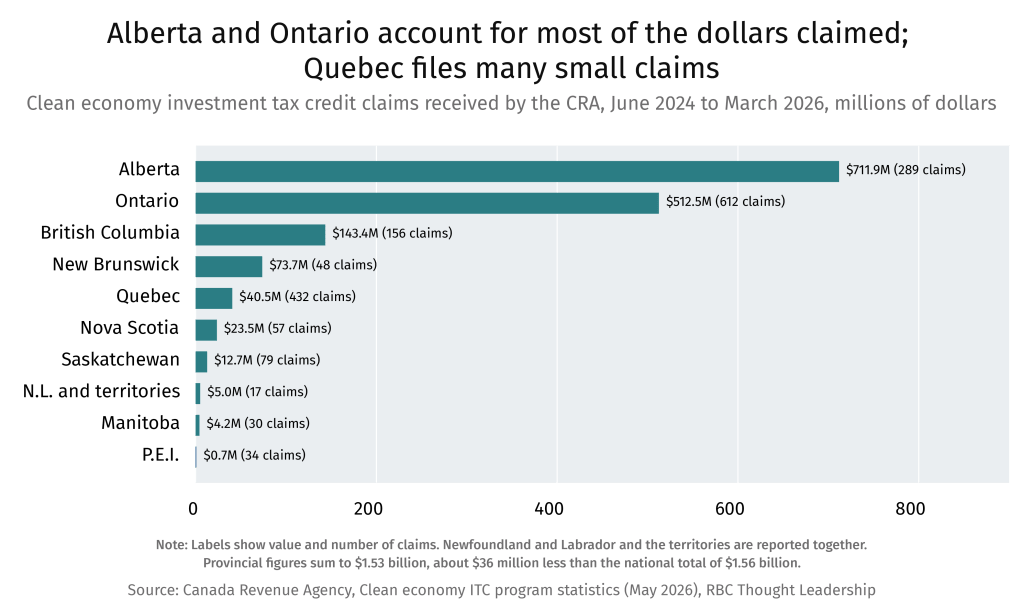
The money, however, has been slow to arrive. Companies had claimed $1.56 billion in investment tax credits by March 2026, Canada Revenue Agency data show. The most recent public figure for payments, from the federal environment commissioner, was $22 million cleared for payment as of July 2025.
The Clean Technology ITC refunds up to 30% of eligible capital costs for equipment such as solar panels, wind turbines, battery storage and heat pumps, while the Clean Electricity ITC covers up to 15% for generation, storage and transmission, and can be claimed by provincial Crown utilities.
The budget proposes extending the Clean Electricity ITC to each province’s highest-voltage transmission lines within its borders, such as 500 kilovolt (kV) lines in Ontario and 735 kV lines in Quebec. Projects that use Canadian-made products receive a bonus of up to 10 percentage points on the Clean Technology credit, and up to five on Clean Electricity, subject to a 60-day consultation period. Ottawa says the bonus is meant to support the use of Canadian industrial products in the projects needed to double the country’s electricity production and transmission.
Canada’s Department of Finance expects the extension and transmission changes to cost $2.4 billion through 2030-31, and $36.1 billion from 2031-32 to 2041-42.
However,three other clean economy credits, which support clean hydrogen, carbon capture, utilization and storage (CCUS), and clean technology manufacturing, remain unchanged, with the manufacturing credit beginning to phase down in 2032, the hydrogen credit halving in 2034, and the CCUS credit’s full rates expiring after 2035. Hydrogen is mentioned only once in the budget, and finance’s tax expenditure report estimates the hydrogen credit cost less than $500,000 a year from 2023 through 2025.
What’s been the ITC claims so far?
The CRA received 1,763 claims worth about $1.6 billion between June 2024 and March 2026 and had processed 465 of them. Clean Technology accounted for 1,261 claims worth $1.23 billion. Alberta had the highest value at $712 million across 289 claims, and Quebec had 432 claims worth $40.5 million combined.
Claims have not kept pace with expected uptake. According to reports from the federal environment commissioner, Finance had projected the credits would cost about $9.2 billion by the end of 2025. As of July 2025, $22 million had been cleared for payment, all under Clean Technology. The CRA processed about a quarter of claims by March 2026. Budget 2026 lowers its cost estimates for the credits, citing revised costing.
Part of that gap could be a result of timing. The credits were enacted retroactively and companies have until Dec. 31, 2026, to file for earlier years. Most credits can only be claimed once equipment is in use. Processing is another potential factor, with the CRA reviewing claims before paying them, which could add to the time taken for claims to be paid out. This could result in delays in recording credits against capital spending.
Comparison with the U.S.
In 2025, under the One Big Beautiful Bill Act, the U.S. legislated an end for credits for wind and solar projects that did not begin construction by July 4, 2026, unless they were operating by the end of 2027. However, credits for nuclear, geothermal, storage and hydro continue into the 2030s.
Carbon capture kept its support in the U.S. The credit now pays the same amount, up to US$85 a tonne, for CO2 used in enhanced oil recovery as for permanent storage. In April, Ottawa proposed allowing enhanced oil recovery under Canada’s CCUS credit at half the standard rates.
U.S. hydrogen projects must begin construction before 2028 to qualify for that country’s production credit. In Canada, as noted above, uptake has been minimal. And large projects in Newfoundland and Labrador and British Columbia have been shelved or paused.
The two systems also pay out differently. Canada’s credits are refundable: if a credit exceeds a company’s tax bill, the CRA pays the difference. Most U.S. credits are not, but companies can sell them to other taxpayers for cash.
Changing the U.S. rules would require legislation passed by both chambers of Congress and signed by the president.
What companies should watch for
-
Electricity projects would have support to 2040. However, manufacturers would see credits declining in 2032.
-
Payment timing could affect financing. The CRA reviews claims before paying them, and processing has been slow.
-
Meeting labour requirements makes credits more attractive. Companies that do not meet prevailing wage and apprenticeship requirements receive 5% instead of 15% under the Clean Electricity credit, and 20% instead of 30% under Clean Technology.
-
A boost for electricity providers. Utilities building their largest transmission lines can now claim the credit on transformers and other equipment they buy. The manufacturing credit, however, does not list grid equipment among the products it supports making in Canada.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates. This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/our-impact/sustainability-reporting/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.