Language Flag Filename

rbc_language_toggle_menu_flag

Also in this edition: What the future could hold for Canada’s auto industry

Agreements from Washington’s inaugural Critical Minerals Ministerial are still being digested, which saw bilateral frameworks with over a dozen trade partners and the unveiling of Project Vault.

Notably, Canada wasn’t among the signatories. So as America rewires the global minerals order, does Canada stand to gain or be left behind?

Why It Matters

Project Vault is America’s attempt to build a Strategic Petroleum Reserve for critical minerals. The problem: the SPR analogy breaks down in a way that matters enormously for Canada.

The original SPR worked because the U.S. had vast domestic refining capacity—stored crude to be converted into refined fuels along the Gulf Coast. Today, North America has almost none of the processing infrastructure needed to convert raw critical minerals into the refined compounds that defense, semiconductors, and EVs ultimately require.

So Project Vault faces a fundamental paradox: stockpile raw ore with no capacity to process it; stockpile refined material almost certainly bought from China—the very dependency the U.S. is trying to hedge.

By the Numbers

  • US$15 billion—EXIM Bank financing already mobilized across allied minerals projects globally, before Project Vault

  • US$12 billion—Project Vault financing (US$10 billion from the U.S. Export-Import Bank and US$2 billion in private capital)

  • 60-day supply target buffer for strategic minerals

  • 15 bilateral frameworks signed this week alone—including the EU, Japan, UAE.

  • China’s refining grip—98% gallium, 91% rare earth magnets, 96% battery-grade graphite, 79% cobalt

  • Canada’s position—71% of U.S. unwrought aluminum imports; Quebec’s Vaudreuil refinery is one of only two alumina refineries left in North America.

  • Project Vault covers all 60 critical minerals on the USGS list, many of which are core economic exports for Canada

The Bigger Picture

The U.S. isn’t building a multilateral framework—the word chosen deliberately at the ministerial was plurilateral. A smaller, aligned coalition setting its own rules, coordinating price floors, and directing investment collectively. Through EXIM and Project Vault, this architecture is being built in real-time.

Energy-intensive refining and smelting, the very processes needed to turn minerals reserve into usable industrial inputs, on paper at least, is a good set up for Canada. Our clean and cost competitive power (hydro, nuclear) complements existing mineral deposits, which, with integrated rail networks, allow for better full-cycle economics than stand-alone processing and refining operations.

Bottom Line

Canada’s critical minerals endowment is arguably its most important bilateral tool heading into the CUSMA renegotiation. Its broader integration into U.S. supply chains—across aluminum, copper, nickel, zinc and manganese— limits being phased-out to a large extent. If Canada can secure explicit recognition of Canadian content in U.S. value chains, via CUSMA assisted by Project Vault’s predictive offtake and access to U.S. capital, it is a clear win.

That said, our minerals chip depreciates with each passing day. Every bilateral framework Washington signs with another partner narrows Canada’s relative leverage, especially if CUSMA negotiations extend into 2027. And at a time when investment decisions at times are less about economics and more a price of admission to the U.S. market (read: Korea Zinc JV).

Threading that needle will be the challenge.

– Shaz Merwat

RBC economist Farhad Pananov was at The Globe and Mail’s Future of Automotive event this week. Here’s some of what he heard:

  • Strategic investments in the auto sector have fallen off compared to just to a few years ago when manufacturers were setting long-term pivots.

  • While panelists heaped plenty of praise on Canada’s highly skilled and educated labour force and diversified local economies, it was clear what the country’s greatest advantage is access to the second largest auto market in the world. For now, at least.

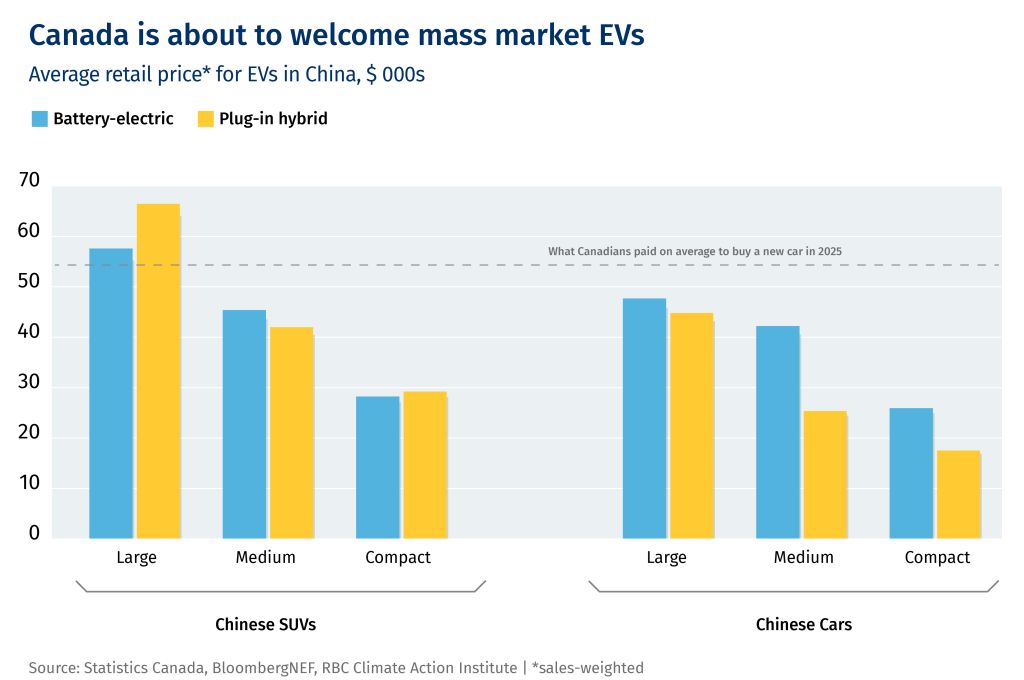
  • The Canada-China EV deal, which will facilitate the import of 49,000 Chinese EVs a year at low tariff rates, was met with skepticism in the room: Which brands will come to Canada? Will Canadians actually buy them?

The answer to that last question could all come down to the price…
U.S. lawmakers rebuke Trump’s Canada tariffs 

  • The U.S. House of Representatives voted to rescind tariffs on Canadian goods, the same week President Trump threatened to block the opening of the Gordie Howe International Bridge because of trade disputes. 

  • While the President will likely veto the motion, Wednesday’s vote was backed by six Republicans, indicating growing discontent with Trump’s trade policies and threats. 

U.S. agriculture industry lobbies for CUSMA continuation

  • Over 40 U.S. agricultural groups have formed a coalition to support the Canada-U.S.-Mexico trade agreement, emphasizing the economic benefits it brings to rural communities and American farmlands.

  • The advocacy campaign is targeting members of Congress, the White House, and the President, with economic analysis that shows Canada and Mexico account for approximately one-third of the value of U.S. agricultural exports. 

U.K. government signals closer alignment with Europe

  • Chancellor Rachel Reeves announced the U.K. is prepared to unilaterally align with the EU’s single market rules in sectors like financial services to reduce trade barriers, describing closer integration with the EU as the “biggest prize” for U.K. growth, pivoting away from prioritizing non-European trade deals.

  • The Labour government has been reticent to reopen Brexit as a political issue but are beginning to look more fondly at closer integration with the EU as they search for ways to boost economic growth. 

— Thomas Ashcroft
Language Flag Filename

rbc_language_toggle_menu_flag

Canada’s agri-food startups present a $13-billion investment opportunity. Capital flows in growing agri-food companies could help Ottawa achieve its target of unlocking $1 trillion in investment by 2030 to power economic growth.

The country’s agri-food sector is currently undercapitalized by domestic growth funds. The sector accounts for only 2% of government-backed growth, venture and infrastructure funds at the federal level, and brought in an estimated 4% of total growth funds invested in Canada over the past 5 years.

It’s not that there isn’t interest. Venture and institutional funds have attempted to flow but fragmented governance across provinces and sector fit for funds have pushed agri-food to the sidelines of mainstream approaches to deploying growth capital.

Domestic agri-food companies got a piece of the growth capital boom–$10.5 billion–between 2015 and 2021. However, investments across sectors have dwindled. Today, growth investment in Canadian agri-food is lower than it was a decade ago, with values down 32% and deals by 29%.

The basic mechanics of growth for an agri-food company can cut the sector out of fund priorities. To align investment with Canada’s growth and sovereignty ambitions, funds like the $1B Venture and Growth Capital Initiative announced in the 2025 federal budget could establish agri-food lanes with tailored tools.

Other nations–including Finland, Japan, and the United Arab Emirates–are explicitly linking food security, productivity, and industrial policy through coordinated growth capital strategies. To achieve food security goals, the UAE launched the Agri-Food Growth and Water Abundance (AGWA) cluster with the ambition to attract $48 billion by 2045 specifically for their agriculture, food and water sectors.

The opportunity for Canadian investors and innovators–public and private–is to better calibrate and scale capital and businesses to anchor economic value domestically. This starts at the idea stage, improving universities’ weakening role in innovation and reverse trends in business outsourced investments to universities for agri-food R&D, which have fallen 64% in the past five years.

Canada has one of the world’s most productive agricultural systems, globally competitive farmers, and is a net exporter of value-added agriculture and food products. Yet, the country is steadily losing its position as a preferred place to start, scale, and retain agri-fooda startups. That’s because the pipeline for investment and innovation has structural gaps and barriers, from seed to maturity.

Canada is in building mode. Its ambition to attract $1 trillionb in investment over the next five years to drive growth for the country is a signal.1 A key piece of mobilizing this investment is to put Canada’s existing infrastructure, growth, and venture funds to work for potential high-growth sectors, such as agri-food industries. Most notably, the 2025 federal budget identified agri-food as one of three sectors that Canada enjoys a strategic global advantage. But Canadian agri-food accounts for less than 2% of growth-oriented government-backed funds. And over the past five years, agri-food companies have only captured 4% of total growth capitalc investment in Canada, which agri-food investors characterize as a stark under-investment in the sector.

If Canada were to align its growth capital investment in agri-food with the industry’s contribution to GDP as a benchmark to build from, it would require an estimated $13 billion from now until 2030–a 36% boost in investment relative to the past five years. An investment ambition to focus action and position Canada as a thriving, global hub of agri-food innovation and products.

Global disruptions over the past five years highlight the need to advance Canada’s sovereign capacity in agriculture and food innovation, production and processing. And the rest of the world is not waiting for Canada to perfect its approach. Without immediate action, Canada risks capping agri-food sector’s growth potential by not hosting more value-add processing domestically. It risks hollowing out the agri-food innovation ecosystem as companies and talent look to other countries, including Australia, Japan and Germany, which are growing their investment in R&D and commercialization.2 And it risks irrelevance in the era of disruptive technologies—including AI-driven decision tools, gene editing, biological inputs, automation, robotics, and novel food processing—that will shape productivity gains in the decades ahead.

There is a mismatch between the framing of Canada’s agri-food sector as a superpower and its strategic advantages with the actual scale and focus of investments domestically. Transforming Canada into an agri-food superpower requires a targeted, nimble approach to capital and growth that navigates the sector’s restraints and fulfills its true potential.

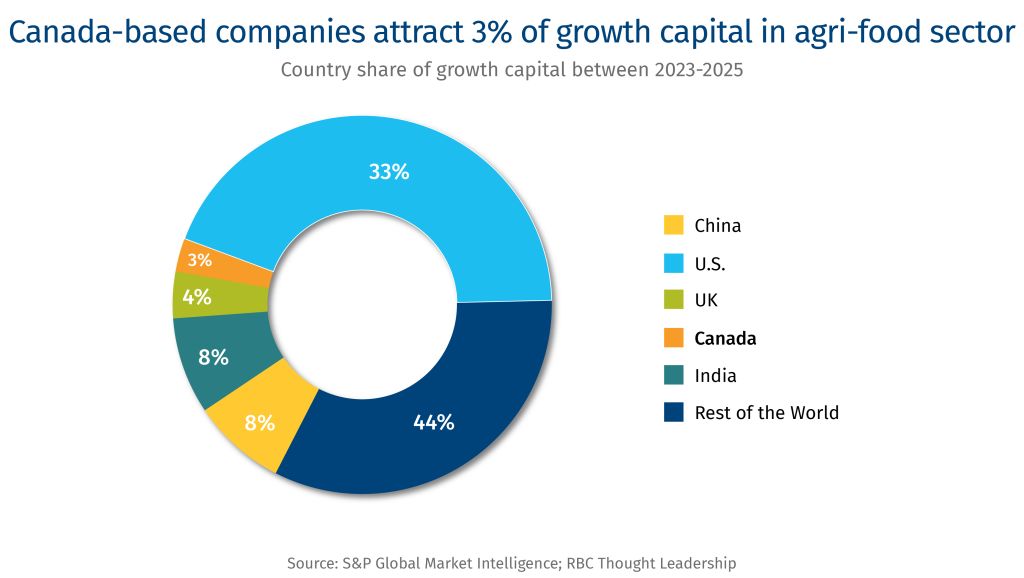
Canada-based companies attarct 3% of growth capital in agri-food sector
  • Purpose of capital: Idea development, early prototyping, market research

  • Investors: Angel investors, incubators/accelerators, university and government grants, venture seed funds, family offices

  • Strengths: Government and regionalized support via early-stage innovation programs

  • Challenge: Breakdown between public and private collaboration on commercialization of intellectual property (IP)

  • Purpose of capital: Pilots, prototyping, market testing, and small-scale production

  • Investors: Accelerators, venture firms, corporate venture, government grants, family offices, Crown corporations

  • Strengths: Growing network of venture funds

  • Challenges: Navigating investment pathways and undercapitalization risks that could force bridging rounds, slow development, and dilute equity

  • Purpose of capital: Continued innovation, market leadership emerging, scaling operations

  • Investors:  Venture firms, private equity, corporate strategic investment, Crown corporations

  • Strengths: Access to international market for capital, especially U.S. and EU

  • Challenges: Gap in follow-on fund, especially Series B to growth and fragmented domestic capital-raising options

  • Purpose of capital: Stable cash flows, slower growth, operational efficiency and expansion, exit

  • Investors: Commercial banks, private equity, merger and acquisition, trade sale, initial public offering

  • Strengths: Strong commercial bank support, however, project financing can be difficult to secure

  • Challenges: Few large domestic corporate acquirers; often requires sale to foreign buyers; Companies with infrastructure projects face structural challenges in assembling capital mixes

Not enough companies make it to growth; and not enough capital is available for the select few that do.

The scale, staging, and value of growth capital invested in growing companies are indicators of a sector’s momentum and growth prospects. In Canada, upstream and midstream marketsd  that cover agriculture inputs to food processing is generally well covered for early-stage capital by government grants, family offices, and venture firms. While end-stream markets like food brands have less access to early stage-funds, with fewer active venture firms in the market. Agri-food companies across market segments start to face Canada’s growth capital challenge of fragmented and shallow domestic funds when seeking to raise $15 million in capital or more. And across economic sectors, there is a significant gap in capital for growth, with domestic venture firms not positioned to inject more than $30 million. This constrains scaling and reduces Canada’s ability to attract and retain high-potential agri-food companies. The situation is exacerbated as agri-food in Canada is too complex for general investors to navigate without industry expertise. The capital pools, for example, engaging with an agriculture-tech company are often completely different from those engaged with a food brand company as their growth metrics, markets, and use of capital differ substantially (e.g., IP vs. a distribution warehouse).

The growth capital market has had a volatile decade. The world experienced a surge in growth capital across sectors, including agri-food, in the lead up to the peak in 2021. Between 2015 and 2021, growth capital in Canadian agri-food in the early and venture stages grew by 1,405% and 480%, respectively.3 This growth was driven by a few factors, and actors:

  • Global interest in agri-food technology and sustainable agriculture surged with the growing urgency to feed more people with fewer environmental impacts. As a result, global investment in agri-food technology rose to $71 billion in 2021.4

  • In response, Canada launched incubators (YSpace Food Incubator), accelerators (SVG Thrive) and applied food science centres (Saskatchewan Food Industry Development Centre) to enable commercialization of agri-food innovation.

  • Agriculture and food focused venture funds also grew in Canada, including District Ventures Capital, Ag Capital Canada, Emmertech, Tall Grass Ventures, and Nya Ventures.

  • And some crown corporations helped drive momentum in the sector through initiatives like Farm Credit Canada’s (FCC) $2 billion commitment by 2030 to advance innovation in the domestic agriculture and food industry.

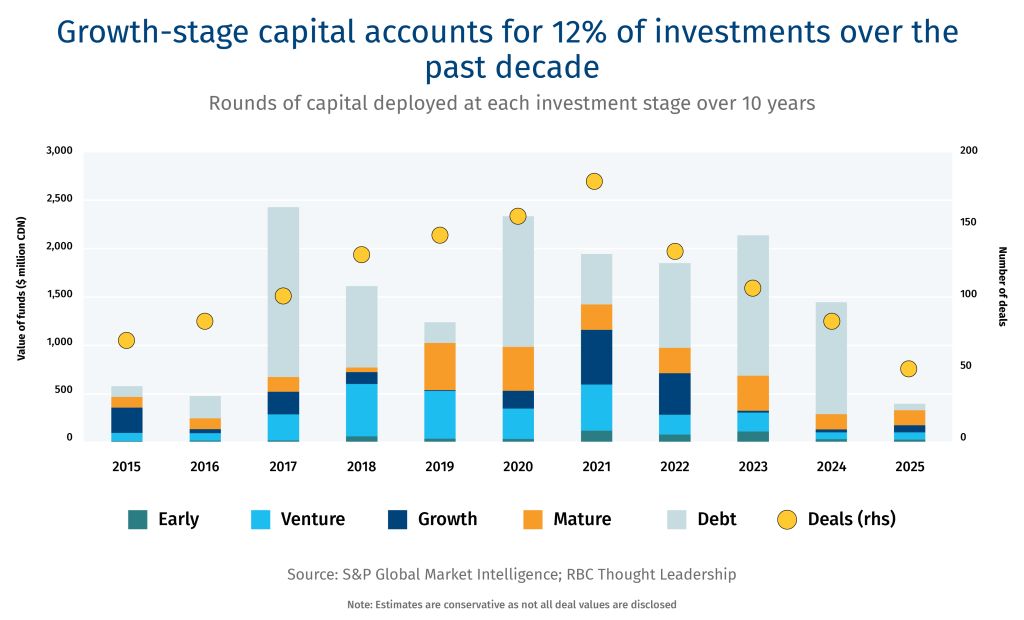
Growth stage capital acocunts for 12% of investments over the past decade

Since 2021, most segments of growth capital availability and investments have dwindled. Investment in Canadian agri-food companies is now lower than it was a decade ago, with values down 32% and deal count by 29%.5 This contraction mirrors trends in other major agri-food economies—including the U.S., Brazil, and Australia—where funding focused on agri-food technologies dropped to a 10-year low.6

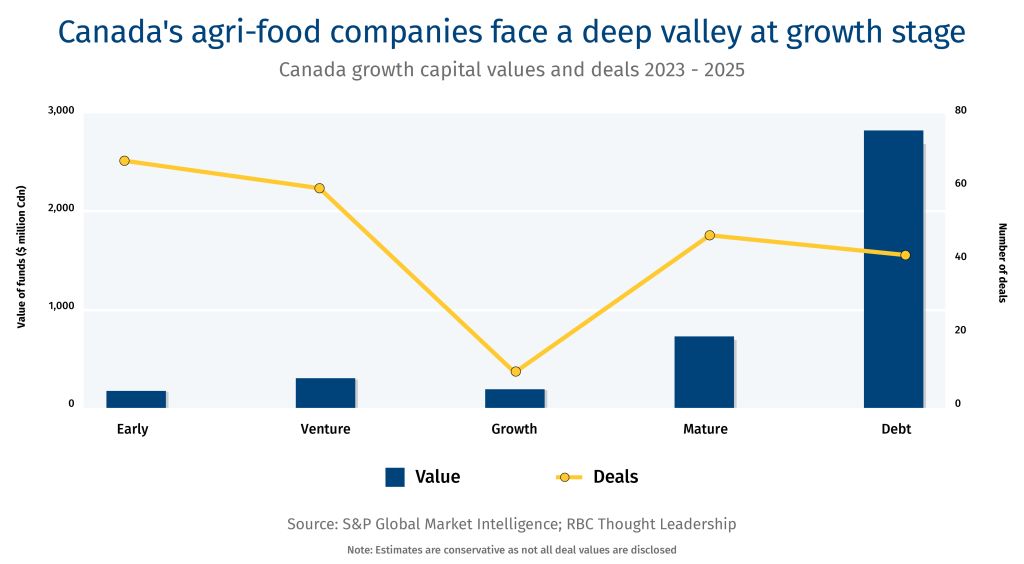
While there have been some positive signs in the past five years, such as rising private equity and a shift to focusing on impactful and mature companies, fundamental challenges in retaining and attracting capital remain. The most obvious challenge is the growth-stage. The value of available capital in Canada in growth stages falls roughly 37% compared to the venture stage where the startups are more supported by venture firms and incubators.7

Canada's agri-food companies face a deep valley at growth stage

However, focusing on fixing this problem in isolation, can result in new problems arising along the pipeline. For example, the agri-food venture funds that emerged over the past decade in Canada now seek to raise new, larger funds to address gaps at the growth capital stage, and this shift could risk creating a new gap in early venture—rounds of between $1 million and $5 million. Enabling capital availability at each stage of growth and across market segments therefore requires coordination among investors to build coverage along the pipeline.

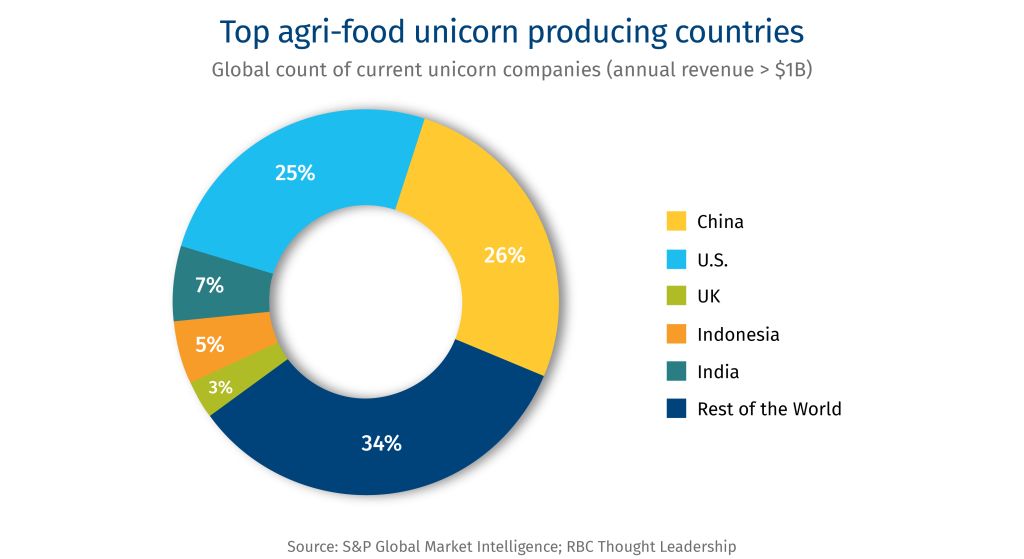
The absence of a Canadian agri-food unicorn—defined as a privately held startup valued at more than $1 billion—is a macro signal that Canada does not have an ecosystem that can propel promising companies.8 Peers like the Netherlands, Germany, and Australia all have unicorns—and heavy hitters like the U.S., India, and China have a stable-full.

Top agri-food unicorn producing countries

Capital structures push companies down and out of Canada.

Canada’s agri-food startups often advance slower through their commercialization and market expansion stages relative to those in competing markets because capital pools are shallower. Less capital leads to incremental growth and longer time horizons to demonstrate returns. While early-stage companies can attract public and venture funding, those seeking larger rounds are often forced to seek capital abroad.

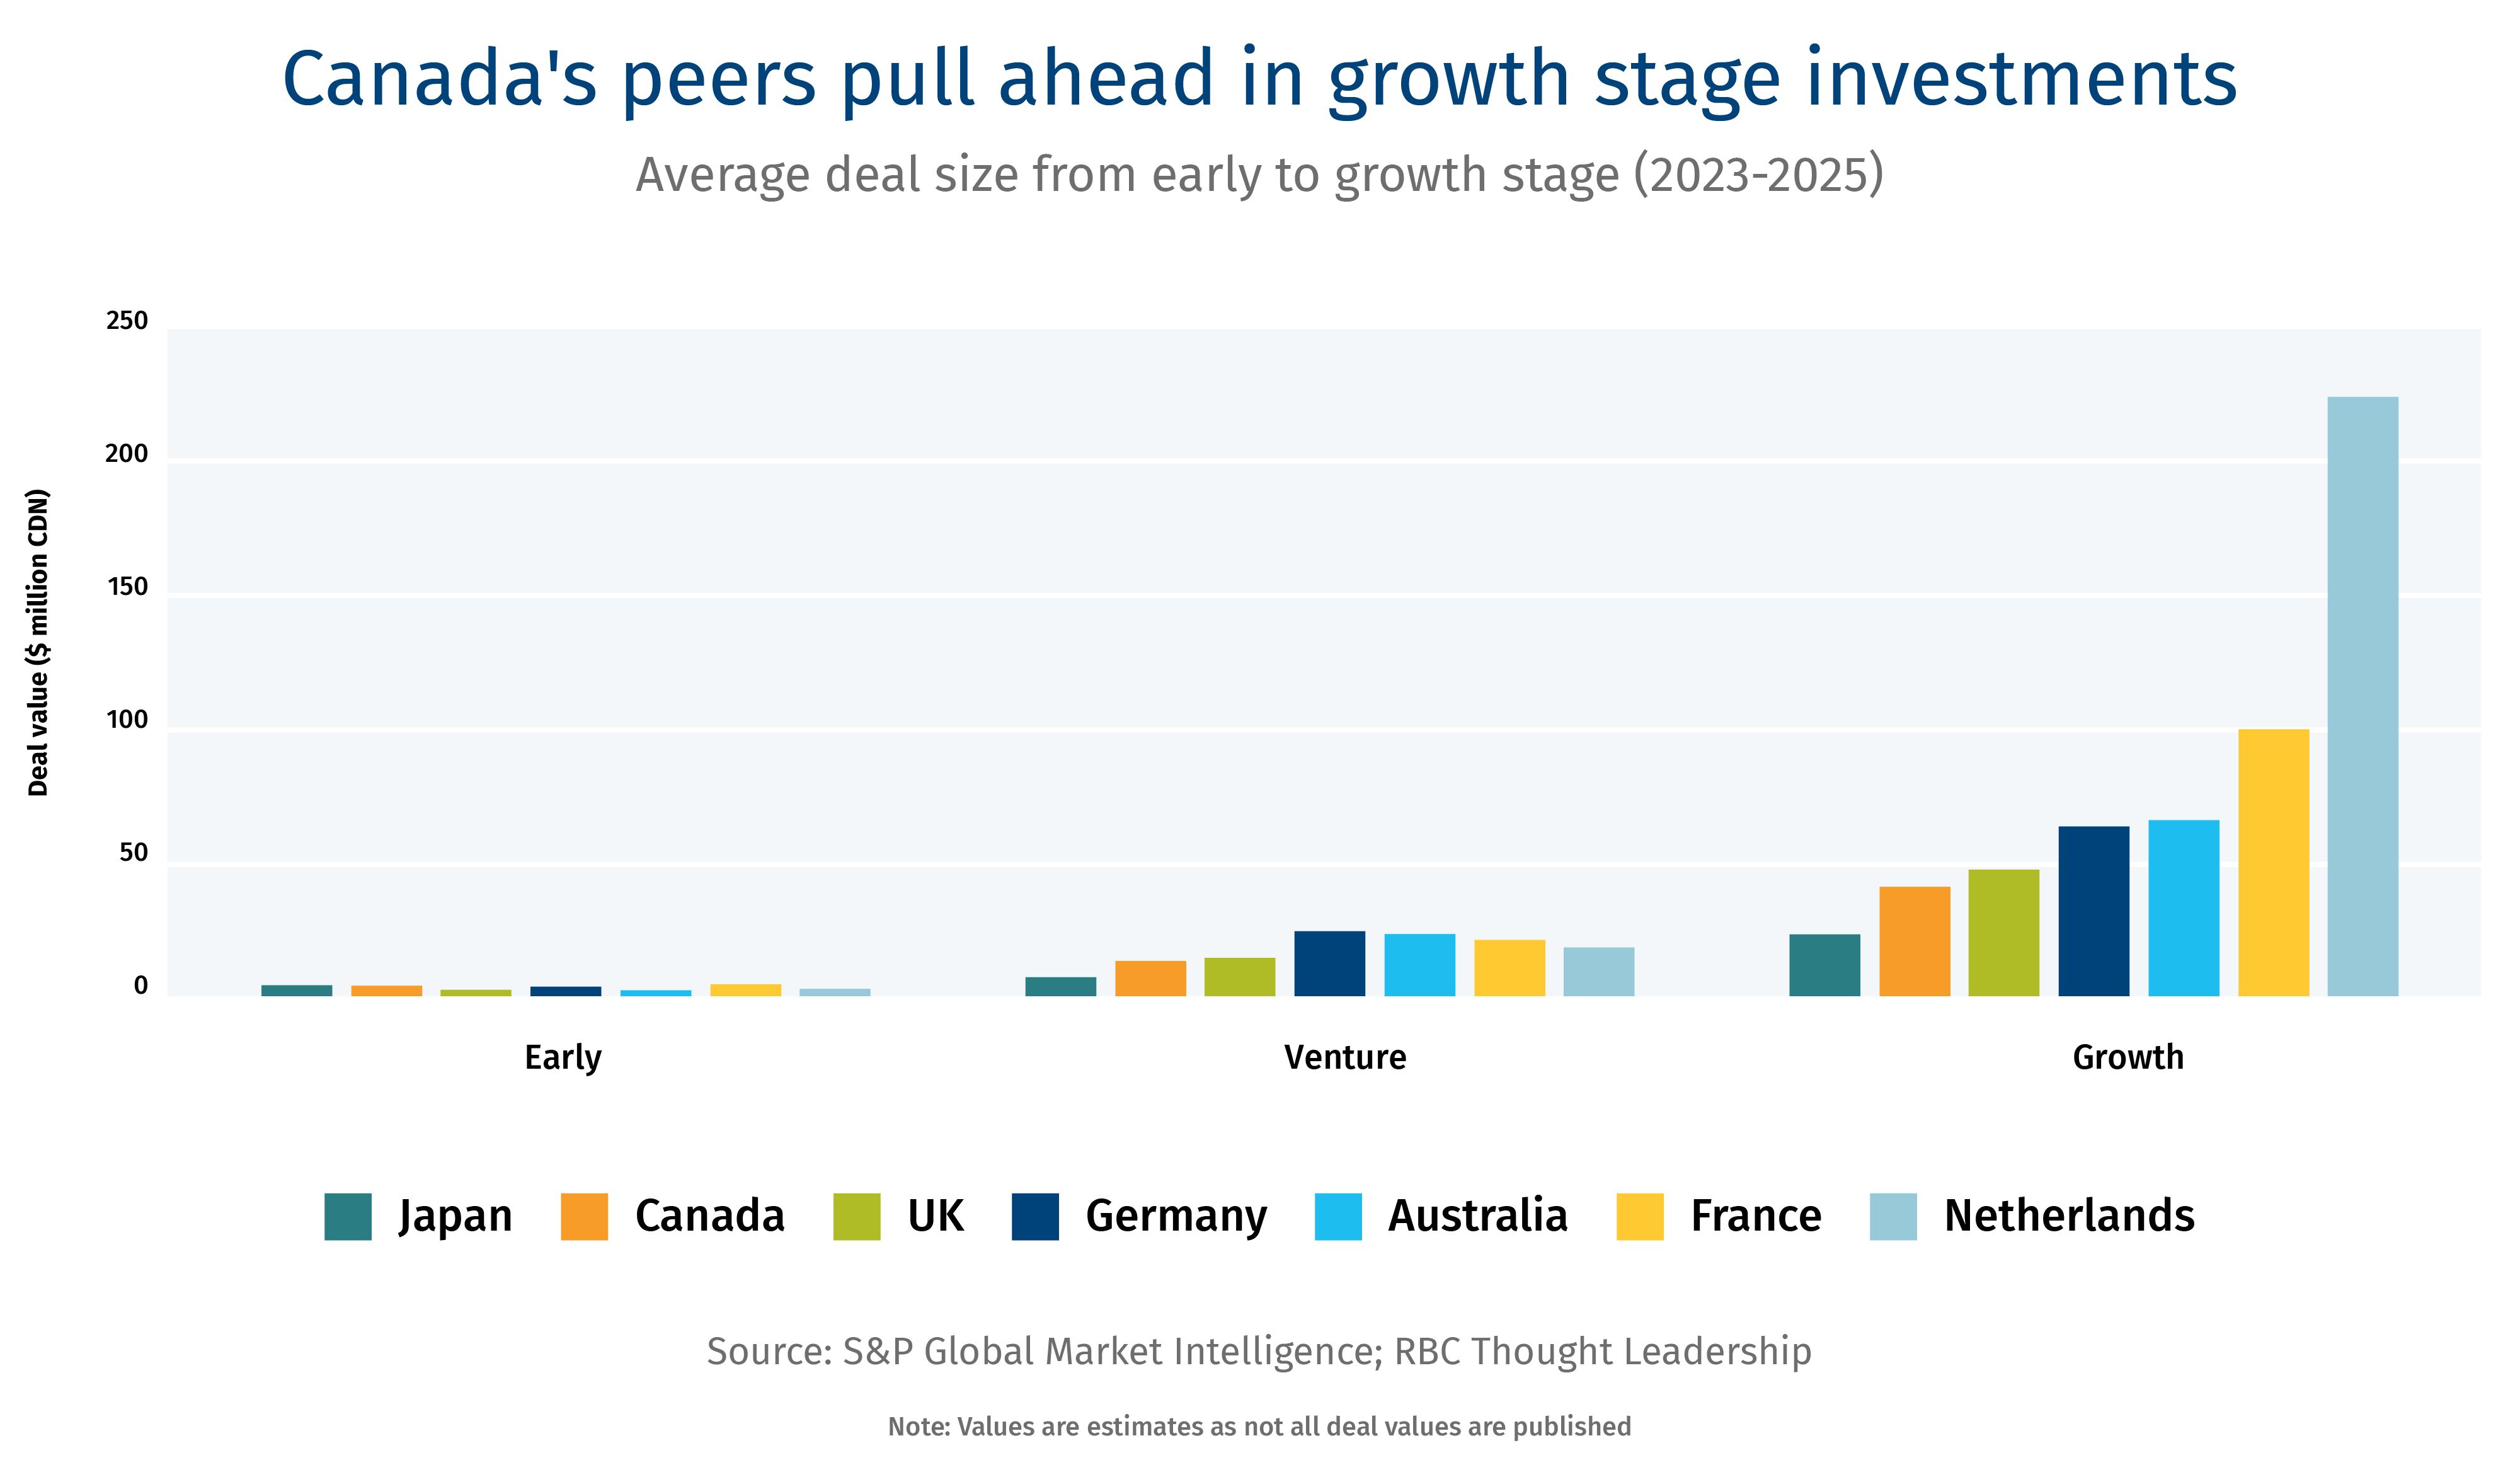
Canada's peers pull ahead in growth stage investments

Vive, a crop protection company based in Mississauga, Ontario, is looking to raise Series D capital, seeking more than $40 million, starting in Q1 of 2026. Vive expects that more than 75% of the capital raised in this round will come from outside Canada. This builds on Vive’s initial market expansion, which occurred in the U.S. because the active ingredient approval for their products took four years compared to the eight years it took in Canada.

Fueling early agri-food innovations but avoiding support for those same innovations at growth stages.

Support from government at the early stages of growth comes largely from incubators, accelerators, cost-share and R&D programs, which are important pieces of Canada’s agri-food innovation pipeline. Yet, this concentration and program delivery often results in Canada’s emerging leaders in agri-food being described as “grant-entrepreneurs” who are forced to spend excessive time on finding and writing applications and meeting reporting requirements instead of building investor-ready businesses. Of course, government checks and balances are vital in public funding, but accessing and reporting on these funds can be made more efficient.

Another challenge with government capital is that economy-wide pools of funds like the Canada Growth Fund do not intentionally restrict agri-food, but the sector often does not fit neatly within investment criteria for several reasons, including project scales, geographical dispersion of production and projects, and the definitions of innovation or clean technology. As a result:

  • Canada Growth Fund’s 17+ investments do not feature a single agri-food company.

  • Of Canada Infrastructure Bank’s 106 investments, only one is focused on agriculture production.

  • The agri-food sector makes up an estimated 3% of the 575 companies invested in through the Venture Capital Catalyst Initiative (VCCI) and Venture Capital Action Plan.

Capital from asset-tied farmers to blocked out institutional investors is an untapped resource for Canada’s agri-food sector.

Institutional investors in Canada, like pensionfunds and private equity firms, want to be engaged in Canadian agri-food but face a trifecta of investment barriers:

  • Limited number of sizeable projects

  • Co-investors, both private and public, to share risk

  • Investment-limiting regulations

Canada’s model for capital attraction in primary agriculture illustrates some of these barriers. Canada is optimized for family ownership with differing provincial regulations on ownership restrictions including foreign investment and supply management for some sub-sectors. This is in sharp contrast to Australia, for example, which treats agriculture as an investable export industry via large, aggregated farms with professional farm management companies. Investors can inject hundreds of millions into single companies, who then have more liquidity to make investments in new companies and innovations that can boost their productivity.

Institutional investors looking to make significant investments with proven returns might see Canada’s fragmented model difficult to navigate. As a result, some of Canada’s largest pension funds invest in agriculture outside of Canada. Public Service Pension Investment’s natural resource portfolio is made up of roughly 77% agri-food investments, with Canada accounting for 9.3%. The largest share, 43.3%, goes to Oceania countries, predominately Australia.

Farmers also have an important role in the agri-food innovation and capital pipeline as new products and services in the upstream market segment can directly impact their growth and productivity. But Canadian farmers are limited since capital is often tied up in operational costs and assets, like land, buildings and equipment. This reduces both demand signals for novel technologies and co-investment opportunities in impactful projects relative to countries that can attract large-scale investments at the farm-level and have available capital for expenditures beyond operations and assets.

Risk aversion dampens investor appetite, entrepreneurship, and innovation.

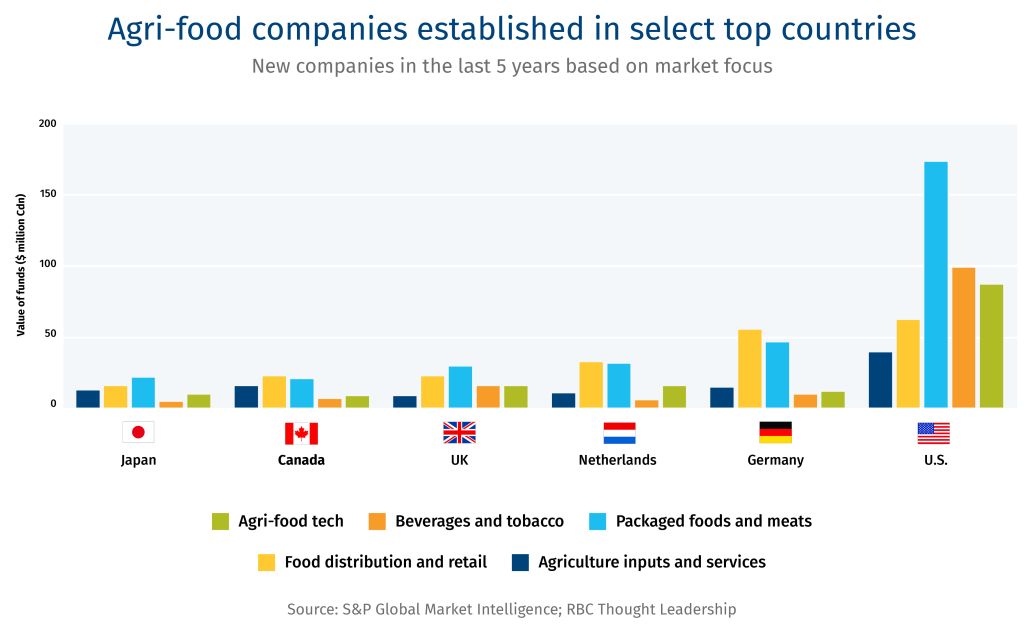
Unlike the U.S., where a “fail fast, iterate, scale” culture fuels deal activity and risk appetite, Canadian investors are generally more risk-averse, particularly beyond seed stage, which discourages bold bets. This shows up in the number of new Canadian companies seeking funding rounds.

Agri-food companies established in select top countries

Traditional investor preferences toward, for example, information technology over agri-food innovation —often perceived as lower-growth and lower-return—limit participation by generalist venture firms and institutional investors. This reinforces narrow capital pools for late-stage agri-food deals.

The onus to build clear and consistent approaches to access support and capital should not lie solely with investors. If startups can get customers, capital often follows. This stresses the need for improving the applicability of new innovations to real-world problems and the adoption of these innovations alongside investment, starting with Canadian farmers, corporates and retailers but also foreign customers for Canadian companies to truly scale.

Proven demand would enable startups to forge capital paths through their growth stages and work with investors to build the right capital stacks. Three Farmers, a Saskatchewan-based snack food company, scaled production in the Prairies and sells its seasoned pulses in more than 4,000 retailers across Canada and the U.S. Attracting growth capital has been a key component of the company’s success. That includes a 2022 raise of $6.2 million led by three pivotal investors: Venture capital firm District Ventures Capital who has deep consumer packaged goods expertise, Export Development Canada how helps companies effectively grow in foreign markets like the U.S., and Protein Industries Canada who can offer access to innovation and supply chain networks.9 In 2025, a new strategic partnership with Farm Credit Canada (FCC) added equity but also the smart capital that growing companies need in the form of mentorship to help navigate regulations and optimal approaches to capital mixes. Such examples offer a gameplan on engaging and connecting with the right type of investors—at the right time.

Building supply chains requires capital—emerging agri-food companies struggle to source it domestically.

Building out agri-food supply chains and commercializing products often requires infrastructure development for production and processing facilities, which demands the right capital structures across equity and debt to make the developments attractive for companies and investors. Often new facilities for production, especially for food products and processing, require off-take contracts or adoption commitments to secure investor confidence. In Canada, where there is a small pool of investors willing to engage in large capital projects, food supply chains are decentralized, and price benchmarks can be uncertain, particularly for novel food ingredients, obtaining these commitments can be difficult, raising percieved risk.

Despite the upfront cost to commercialize and expand, growth in the industry runs counter to the assumption that momentum is not building for value-add processing in Canada. Over the past decade, year-over-year revenue growth in agri-food manufacturing has averaged 5.9%, compared to the manufacturing average of 3.6%.10

Investment in agri-food manufacturing assets has grown by about 32% in constant prices over the past decade.11 This moderate growth is primarily driven by expansion of established, large scale agri-food companies building out meaningful processing capacity.

Yet, many new companies innovating in food ingredients face barriers in bringing together the right capital stacks due to supply-chain barriers–a lack of price certainty and contractual commitments from buyers before processing infrastructure is built. As a result, Canada risks losing value-add processing to other growing jurisdictions where the capital is flowing it. For example, Phytokana Ingredients Inc., an Alberta startup turning Canadian-grown fava beans into food ingredients, is working to build out Canada’s value-add processing of pulses and is in the process of securing funding to construct and commission a fully automated 30,000-metric-tonne-a-year dry fractionation processing facility near Strathmore, Alberta.12 However, building the right capital base is proving challenging with domestic investors, pushing Phytokana to explore foreign investors, which may have implications for where future value-add processing is developed.

Canada’s agri-food landscape is difficult to navigate for startups and investors not ingrained in the network of agri-food regional and national organizations. Once in these networks, startups in the early stages are often well supported, but two challenges to building consistent pathways for companies to attract staged capital remain:

  • Navigating the funding and support opportunities and application processes

  • Identifying where to go for follow-on funding

Mapping investor profiles to specific market segments and their mandates provides a structured roadmap for scaling capital from seed through to growth stages. Countries like the U.K., Israel, and Singapore offer examples of how to build such structure. The U.K., for example, is known for structured paths from seed accelerators and hubs into mid-and late-stage capital with organizations such as Founder Factory.

A key reason why agri-food deal counts in Canada over the past three years shrink by 450% between early to growth stage is the state of startup companies’ readiness. Investors consistently cite company readiness as a primary constraint. Founders of startups often excel at proof-of-concept and R&D but face challenges when transitioning to validated customer demand, repeatable revenue models, regulatory and supply-chain readiness and management and governance maturity.

Many organizations, including university research innovation offices and accelerators, are positioned to work on these issues. For example, the Canadian Food Innovation Network (CFIN) connects startups with corporate partners around defined food technology market segments such as food ingredients. These programs enable startups to build relationships with retailers and strategic buyers earlier, while giving corporates and supply-chain actors clearer visibility into emerging innovations. Making this connection is critical to improving startup success rates and building connectivity among industry leaders and startups, as only 6% of public corporate companies engage in venture investment in Canada, compared to 40% in the U.S.13

Canada is increasingly perceived as a regulatory burdensome place to scale an agri-food business and commercialize its IP in agri-food.

Canada lags key competitors like Australia, Japan, Germany, France, Italy, UK and South Korea as a priority jurisdiction for agri-food patent filing.14 An outcome of multinational companies, especially those in life sciences that reported that they have seen Canada significantly fall in their internal ranking of jurisdictions to invest in R&D over the last decade. This is in part due to approval processes for agri-inputs like active ingredients in pesticides struggling to maintain a timely and transparent process for reviewing applications.15 These trends are chipping away at Canada’s brand as a supporter of early agri-food innovation.

United States: Scale and depth

Market share: The U.S. captured 33% of global agri-food investments over the past three years.

Strength: The sheer scale and maturity of its capital markets.

Lesson: Build growth funds that can actively participate across the full company lifecycle. For example, Chicago-based S2G Investments has multiple funds, and can work with companies at different stages of growth, creating deeper capital pools, where agri-food companies have historically struggled to access capital from PE or commercial banks (e.g., pre-revenue).

India: Demand-driven growth

Market share: India now attracts 8% of global agri-food growth investment and is projected to be even more dominate over the next decade as its agriculture productivity rapidly improves.

Strength: Growth is anchored in massive domestic demand, a rapidly modernizing food system, and strong government support for agricultural innovation.

Lesson: Focus on the basics of where production and consumption is growing to steer investment. To meet consumption and production projections, India is experiencing strong growth in agri-marketplace platforms, supply-chain logistics, and precision agriculture through increased participation from domestic venture funds and strategic.

The country now captures nearly 8% of Europe’s agri-food tech investments.16 The recent surge was driven largely by a $260-million growth-stage investment in Finnforel, an aquaculture company, highlighting Finland’s strength in sustainable protein and advanced food production systems.

Despite just 2.3 million hectares of farmland—3.7% of Canada’s farmland mass—Finland is emerging as an innovation hub following a similar government-backed approach that the Netherlands and Denmark have taken to crowd-in private investment for the sector. Finland’s ecosystem is characterized by strong public-private collaboration, deep expertise in cold-climate agriculture and aquaculture, and a focus on export-oriented, high-technology solutions.

Japan is now the third largest agri-food technology investor in Asia capturing an estimated 13% of the market–behind India and China.17 Japan rose in the global rankings on the back of several large growth-stage deals, including a $89-million investment in biomaterials startup Spiber.

Japan’s competitive advantages include active participation by large corporate venture investors, including Global Brain Corporation and Beyond Next Ventures. Japan is a mature domestic market that supports commercialization of premium and functional foods and has notable advantages in key growth areas including biomaterials and fermentation technologies. The country’s domestic ecosystem also excels at scaling capital-intensive technologies that require long development timelines and strong industrial partners.

The UAE imports approximately 80% of its food. In response, food security has become a national priority. The UAE aims to produce 50% of its food domestically and rank first in the Global Food Security Index by 2051.18 To achieve this, the UAE launched the Agri-Food Growth and Water Abundance (AGWA) economic cluster, which aims to attract nearly $48 billion by 2045.

Food security as a strategic imperative has fueled rapid growth in the country’s agri-food sector, and is supported by broader benefits of the UAE’s economy, including:

  • Tax-free zones and investor-friendly regulation

  • Leading logistics infrastructure and a strategic geographic location as a connector between Europe, Africa, and Asia

  • Strong government backing aligned with long-term national goals.

Potential impact: Improve universities’ weakening role in innovation and reverse trends in business outsourced investments to universities for agri-food R&D, which have fallen 64% in the past five years.19

Incentivizing commercialization requires exploring approaches beyond rewarding researchers via grants that measure success based on peer-reviewed publications and promotions dependent on traditional academic-research-services model. Agri-food faculties across Canada could consider strengthening their promotion of academic-entrepreneur pathways for researchers—like Dalhousie University’s Agriculture Faculty offers—and create structured opportunities for universities and the private sector to negotiate IP ownership to support commercialization. This could include enabling co-design partnerships among institutions and companies, providing clearer conflict-of-interest guidance, and embedding commercialization activity into promotion and tenure criteria, particularly in applied sciences and engineering disciplines.

It is common practice for Canadian universities and colleges engaged in private-sector projects to automatically own the IP that’s developed. While this approach is often designed to protect public interest and institutional value, these conditions—combined with the lack of formal recognition, tenure credit, and financial reward structures for researchers acting as entrepreneurs—can create material barriers to commercialization. As a result, institutions like universities, which are foundational breeding grounds for experimentation and novel idea generation, risk being increasingly excluded from the agri-food commercialization pipeline, particularly in capital-intensive and applied innovation areas such as food processing, biomanufacturing, and agriculture tech. The U.S, Israel, and parts of Europe have demonstrated that flexible IP ownership models—such as creator-owned or shared-IP frameworks paired with clear revenue-sharing mechanisms—can materially increase startup formation, industry collaboration, and downstream investment without compromising academic integrity.

Potential impact: Mitigate the stark deal count shrink of 450% from early stage to growth stage; and retain entrepreneurial STEM and business talent in agriculture beyond the current 1% of postgraduates.20

To solve early-stage roadblocks, build an AI-powered concierge platform within an existing national organization with sector credibility and institutional knowledge that allows startups to navigate public and private opportunities in one place, building upon existing tools like AgPal.

There have been previous attempts at building similar services to help startups navigate this landscape, and many incubators and accelerators offer connection and navigation services. Yet, agri-food startups consistently report being lost in the early stages of company formation and experience a sharp drop-off in support once they graduate from an incubator or accelerator. This “support cliff” is particularly acute in agri-food due to long R&D cycles, regulatory complexity, and capital intensity. Such a tool could provide tailored, real-time guidance on funding eligibility, customer discovery, regulatory pathways, clearer hand-offs for each growth capital stage, and ecosystem connections.

Optimizing the platform would require investors and early-stage supporters to align on shared definitions of market segments, innovation categories, and support mandates so the tool can accurately route startups to the right opportunities.

Potential impact: Address agri-food’s underwhelming share of total domestic growth capital by engaging more generalists in the sector, while also attracting a larger share of global venture capital investment, totally more than $500 billion in 2025.21

If the sector wants outsiders to engage, existing agri-food leaders and investors in Canada need to offer more intentional platforms for non-agri-food investors to build familiarity, context, and conviction. A starting point could be targeted national roundtables for each market segment led by select agri-food investment leaders for domestic and international generalist investors to start building connections, share sector-specific investment theses, and compare notes on market segment profiles, timelines, and exit pathways.

On the other side, general investors that have intentions to materially and strategically invest in the sector also have an opportunity to pull agri-food into their coverage area. Opportunities to embed agri-food expertise directly into investment decision-making could include:

  • Investment committees and advisory panels that upgrade their agri-food expertise by including agri-food operators, processors, and sector investors.

  • Fund managers of investment firms participating in federal programs like VCCI must have a team with either:

    • Prior agri-food investing experience, or

    • A formal advisory relationship with sector experts.

Venture funds and programs allow for sector-specialist sub-allocations within broader funds such as agri-food market segment carve-outs within generalist funds.

The potential impact: Position agri-food to have investable projects and companies for government-back funds to invest in beyond the current 2% that the sector captures from these funds.

Although agri-food is cited as one of Canada’s key strategic advantages, government investment programs – at the provincial and federal level – are often not accessible to growing agri-food companies because they are not fit for purpose for the types of innovation, asset intensity, and scaling timelines typical of the sector. This misalignment leaves significant agri-food potential unleveraged.

For example, VCCI does not explicitly exclude agri-food, and some participating fund managers do operate agri-food-focused funds. But only 3% of companies invested in through VCCI-supported funds operate within the agri-food sector. While fund manager expertise and explicit mention of agri-food plays a role, so too do program criteria, technology definitions, and innovation classifications that shape investment decisions and systematically bias capital toward digital-first or asset-light sectors, resulting in agri-food being overlooked.

Rather than creating entirely new programs, existing funds could establish agri-food lanes with tailored tools. One option is to explore a growth-stage agri-food mandate within VCCI or its successor under the $1B Venture and Growth Capital Initiative that was announced in the 2025 federal budget.

There is an opportunity to adjust eligibility rules for federal and provincial government funds to reflect how agri-food companies scale as they raise growth capital, making way for high-quality agri-food companies:

  • Accepting asset-heavy business models that have robust business and risk management plans (e.g., processing facilities, fermentation tanks, cold storage, pilot plants)

  • Recognizing process innovation, novel ingredients, yield improvement, and cost reduction as legitimate innovation—not just software or IP-only advances

  • Allowing longer commercialization timelines (7–10 years vs. 3–5) consistent with regulatory, construction, and market adoption realities.

Potential impact: Canada is a net exporter of processed and value added agri-food products with immense potential to host more processing of products that are largely still exported as raw ingredients. One example is plant protein: while Canada is the number one exporter of dried peas, roughly 88% of production over the past five years has been exported as a raw commodity.22 23 This one example significant missed opportunity for domestic value creation, job growth, and export diversification to benefit from the burgeoning pea protein industry.

Expanding the Canadian agri-food value chain, requires public and private investors to be deploying blended capital structures that reflect agri-food economics. This includes considering tools to mitigate risks in capital deployment for high-impact projects that address a clear growth opportunity for Canada’s agri-food sector such as:

  • Subordinated or patient capital alongside private equity

  • Government first-loss guarantees to de-risk infrastructure projects

  • Revenue-linked instruments or convertible structures suited to variable margins

  • Support for offtake-linked financing when buyer commitments are conditional but there is clear demand

In agri-food markets, upstream buyers often hesitate to confirm long-term offtake agreements before facilities are built or scaled, while investors require revenue certainty to deploy capital—creating a structural deadlock. Targeted risk-sharing tools can bridge this gap and unlock private investment into processing, ingredients, and food manufacturing capacity. Of course, Canada will need to find buyers for processed verse raw ingredients, but not exploring the opportunities to scale processing domestically is a lost value creation opportunity for Canada.

Investing in abundance: Addressing Canada’s growth capital gap in agri-food - social

Download the Report

Alison Suntrum, Nya Ventures and CDL Agri-Food

Amy Standish, Saskatchewan Ministry of Agriculture

Andrew Heintzman, InvestEco Capital

Arlene Dickinson, District Ventures Capital

Ben Gibbons, Water Point Lane

Bianca Parsons, Alberta Food Processors Association

Blair Knippel, Inside Out LLC.

Brennan Gillis, Dalhousie University

Bruce Rathgeber, Dalhousie University

Celine Hildebrandt, Farm Credit Canada

Chris Hartt, Dalhousie University

Chris Paterson, Tall Grass Ventures

Chris Theal, Phytokana

D’Arcy Hilgartner, RDAR

Dana Gibson, Alberta Innovates

Darren Anderson, Vive Crop Protection

Dave Barrett, Dalhousie University

Dawn Trautman, SVG Ventures, THRIVE

Drew Dwernychuk, Innovation Saskatchewan

Evan Fraser, Arrell Food Institute, University of Guelph

Ghader Manafiazar, Dalhousie University

Glen Price, Venturepark

Graeme Millen, Farm Credit Canada

Graham Markham, New Protein International

Greg McElheran, Export Development Canada

Haibo Niu, Dalhousie University

Heather Bruce, Dalhousie University

Jeff Linner, PFM Capital Inc.

Jeff McKinnon, Four Mile

Jeff Zweig, Fiera Comox

Jodie Parmer, Canada Infrastructure Bank

Jolene MacEachern, Dalhousie University

Kassandra Quayle, Protein Industries Canada

Kee Jim, G.K., K Jim Farms and Feedlot Health Management Services Ltd.

Ken McDougall, McDougall Acres Grainex Inc.

Kirby Sawatzky, Parkland Potato Varieties

Krista Heidebrecht, Sofina Foods

Kristjan Hebert, Hebert Grain Ventures

Kyle Scott, Emmertech

Laurie Dmytryshyn, PIC Investment Group Inc.

Lawerence Hanson, Agriculture and Agri-Food Canada

Leah Perry, Wittington Ventures

Lenore Newman, University of Fraser Valley

Marie Barnes, Invest Alberta

Martin Vanderloo, New Protein International

Marvin Slingerland, MNP

Matt Coutts, Coutts Agro Ltd.

Matt Petrow, Rayhawk Technologies

Miranda Stahn, New Harvest Canada

Oleta LeRush, BASF Canada

Richa Gupta, Canadian Food Innovation Network

Rob Russell, Emmertech

Robert Saik, T1 Technology Corporation

Shaun Vey, Syngenta Canada

Stefanie Colombo, Dalhousie University

Steven Webb, Global Institute of Food Security

Suresh Neethirajan, Dalhousie University

Travis Esau, Dalhousie University

Tyler Groeneveld, Protein Industries Canada

Wayne Arsenault, Avena Foods

Wilson Acton, Tall Grass Ventures

Language Flag Filename

rbc_language_toggle_menu_flag

Also in this edition: Canada’s trade with non-U.S. markets is hitting all-time highs and the U.S. looks to create a critical minerals trading bloc to rival China

The Liberal government’s much-anticipated auto-sector strategy reinstates electric vehicle incentives, eliminates EV sales mandates, invests in expanding the EV charging network, and offers incentives and tax breaks for global auto makers to build in the country.

It’s all in response to U.S. tariffs, and the looming threat that President Donald Trump might tear up CUSMA in the coming months.

Of course, Prime Minister Mark Carney is hoping to preserve CUSMA and build on its North American supply chain advantages to a new set of investors. But even if Canada’s access to the U.S. market is no longer unfettered, Ottawa can point to several reasons why European and Asian countries may want to set up their auto shop in Canada:

  • Canadians buy a lot of pricey cars and SUVs: Canada is the world’s 9th-largest auto market, with ~1.9 million vehicles sold annually—skewed toward higher-value SUVs and trucks, with a robust servicing and after-market (courtesy of our harsh winters). OEMs also now compete for high-margin customers, not volume. Canadians buy a lot of cars, including a lot of expensive (read: high margin) cars.

  • Asian carmakers want a North American hub: With 7.2 million global sales in 2024, the combined Korean power of Hyundai-Kia edged out GM and Stellantis for the third spot in the global rankings. However, the companies’ manufacturing footprint and market share remains Asia-heavy, creating an incentive to rebalance toward North America. Canada could become a second North American production zone, hedging geopolitical, climate, and labour risks.

  • Canada is critical to global supply chains: Our store of critical minerals (nickel, cobalt, lithium, graphite), batteries, parts ecosystem, and reliable, clean power offer supply chain integrity at low cost. Just ask Volkswagen.

  • The Ontario-Quebec corridor is an auto-tech Silicon Valley: Canada’s strengths in AI, autonomy, and software—the frontier of future value creation for the auto industry—further enhances the offering.

  • Canada is a free-trade haven: It stands to reason that Canada will secure some form of market access to the U.S. that makes an auto trade possible. We shouldn’t forget the 14 other free trade agreements we’ve signed that cover 50+ countries, 1.5 billion consumers, and 60% of global GDP.

— Jordan Brennan

According to RBC Economist Claire Fan:

“Despite the deteriorating trade balance, Canadian exporters continue to show signs of partial diversification into non-U.S. markets. Goods exports to non-U.S. destinations were 29% above year-ago levels in November, while goods imports from non-U.S. markets rose 18%—both near or at all-time highs.”

U.S. looks to create a critical minerals trading bloc rivalling China

  • At a Washington summit, attended by representatives from more than 50 nations, the U.S. outlined a vision for a rare earths trade zone, using tariffs to create a price floor for minerals and drawing on the respective strengths of partner countries across the value chain, to counter Chinese dominance.

  • Several bilateral deals were struck, including U.S. “Action Plans” with Mexico, the EU and Japan, to develop coordinated trade policies.

  • Foreign Minister Anita Anand said more details were needed before agreeing to such a framework, which would play a role and potentially give Canada some leverage in upcoming CUSMA negotiations.  

Trump and Modi broker trade truce

  • Washington committed to cutting tariffs on Indian goods from 50% to 18%, in return for New Delhi stopping its purchases of Russian oil.

  • While details on the timing of the tariff changes and other trade barrier reductions remain vague, the amelioration of some of Trump’s most punitive tariffs gave a boost to U.S.-listed shares of Indian companies.

Red Sea reopening adds to shipping overcapacity pressures

  • As Houthi attacks on the critical shipping lane subside, and Suez Canal transit rises, container companies are bracing for pressures on their bottom line if freight rates lower and oversupply worsens.

  • Danish group AP Møller-Maersk, the world’s second largest container shipping company, announced its first operating loss in years and plans to cut jobs to insulate these impacts.

  • Naval escorts have become a necessity for container ships passing through the Red Sea, and tensions between Iran, the U.S. and Israel remain a threat to the stability of the passage.

Ottawa indicates foreign aid will be increasingly tied to trade objectives

  • Randeep Sarai, Secretary of State for International Development, said Canada’s development and humanitarian spending will focus more on opportunities that create “mutual prosperity.”

  • As it reduces the foreign aid budget, the government will look to use the distribution of these dollars as a tool with countries that Canada wants to increase trade with.

— Thomas Ashcroft
Language Flag Filename

rbc_language_toggle_menu_flag

Also in this edition: Tariff lawsuits ramp up, Canada-India relations are re-energized, and two economic giants strike the “mother of all trade deals.”

On the same day the International Monetary Fund released a report showing that the removal of internal trade barriers in Canada could result in a 7% boost in real GDP, an important discussion took place at the Canadian Club of Toronto.

Two of Canada’s top CEOs—Tracy Robinson of CN Rail and Max Koeune of McCain Foods—joined Sean Strickland of Canada’s Building Trades Unions for a discussion with the Business Council of Canada’s Goldy Hyder, on the big changes that Canada needs to make to infrastructure development, business regulation and immigration.

Here are some bottlenecks we need to fix—quickly:

  • Canada is among the worst in the OECD in days lost to labour disruptions. That means our connective tissue to the world—ports, rail, sea lanes—are MIA when the rest of the world is expecting us to be on time.

  • The TMX oil pipeline expansion took longer to permit than to build. Just one of many agonizing stories about our glacial speed of permitting and other approvals.

  • Despite massive shortages in the skilled trades, our provinces are bringing in paltry numbers through immigration. Who else is going to build all those big projects?

  • It’s easier regulation-wise to export food to the U.S. than between provinces. When will we get to the one economy idea?

What needs to be done?

Robinson said we need to review our approach to labour negotiations to ensure the economy doesn’t get shut down as often as it does, especially in a world when other countries are happy to see that happen.

Strickland pushed for better labour force planning, to ensure we’re recruiting the right people and right numbers for the right needs in our economy. We’ve talked about that for years. It’s solvable.

Koeune called for immigration reforms that would give permanent residency applicants a clearer view of how long it will take, and where their application is at. He called the system a “black box,” which I’ve heard from plenty of other employers in recent months.

We can’t take on the world if we don’t take on our own challenges first.

Elbows up, fine. Heads up, better.

–John Stackhouse

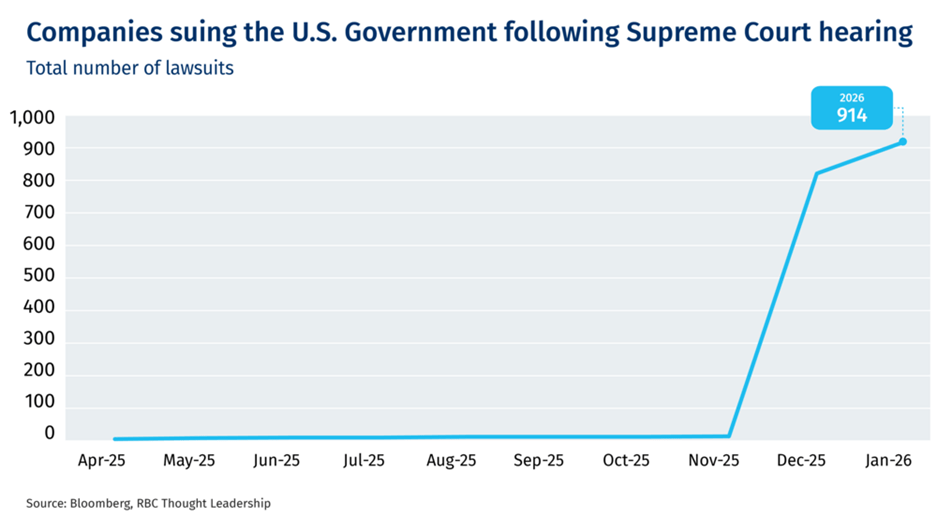
Companies suing the U.S. government following Supreme Court hearing

Since the Supreme Court’s November 5th hearing on the legality of U.S. tariffs, more than 1,000 companies, including Costco, Revlon and Ray-Ban, have sued the Donald Trump administration. The reason? If the highest court in the land strikes down the tariffs (verdict date unknown), the suitors hope to recoup some of the money they allege has been lost due to tariffs.

Record Canadian oil output finds new markets

  • Despite weak global prices, Canada’s oil industry is pumping record volumes and boosting exports to Asian markets, particularly China where sales more than quadrupled last year, as well as India and South Korea.  

  • Though most Canada’s oil exports still go to the U.S., the sector’s resilience, record output driven by expanded pipeline capacity, and growth in Asian markets, is boosting oil majors’ shares and strengthening the country’s economic diversification drive. Expect more calls for additional pipeline capacity, to sustain this trend.

Canada-India pursue apolitical, reliable energy trade

  • As diplomatic relations continue to improve, officials pledged that Canada would supply more crude oil, liquefied natural gas, and liquefied petroleum gas to India, and that more refined petroleum products will be sent the other way.

  • Energy minister Tim Hodgson noted that India represents the fastest-growing source of energy demand while assuring his counterparts “we will never use our energy for coercion.” The relaunch of a “ministerial energy dialogue” between Canada and India promises to facilitate greater reciprocal investment and collaboration in other areas including hydrogen, uranium, biofuels, batter storage, critical minerals, electricity, and AI.   

  • India’s High Commissioner to Canada said Prime Minister Carney will likely visit India in March, and that under his government no longer views Canada as the “younger brother” of the U.S.

India and EU agree “mother of all trade deals”

  • As Washington targets both with steep tariffs, two of the world’s biggest markets have agreed a trade deal that,  once in effect, will eliminate tariffs on more than 90% of goods, marking a new era in economic relations.

  • The two sides made no secret of the fact this breakthrough was catalyzed by U.S. trade policy, to soften the blow of tariffs and increase their economic autonomy. This will result in boosts to India’s export of manufactured goods and give the EU preferential access to a massive, growing market.

  • The EU is already one of India’s largest trading partners, and while India is only the EU’s ninth-trading partner, the EU predicts its exports there to double by 2032. Negotiations over an Investment Protection Agreement are ongoing.

–Thomas Ashcroft

Language Flag Filename

rbc_language_toggle_menu_flag

The World Economic Forum this year became a tale of two Davoses.

Inside the main Congress Centre, a record number of attendees, including 850 CEOs, 80 tech billionaires and founders, hundreds of ministers and 65 heads of government spent the week hearing about the decline of globalization and the inward turn of societies.

Outside, it was a very different world. On the town’s main promenade, you couldn’t walk 50 metres without feeling like you were in a mash-up of Wall Street, Silicon Valley and the United Nations, as countries from Brazil to Indonesia and companies from Tech Mahindra to Pinterest pitched themselves to the passing kaleidoscope of a crowd.

Mark Carney called this new environment one of “variable geometry.” Others called it a new age of “multi-alignment”—as if the global economy is becoming a bit more of a bartering and babbling souk than a tightly wired marketplace. By any name, the emerging world order, or disorder, seems as slippery and risky as the icy streets of Davos. Here’s some of what to look out for:

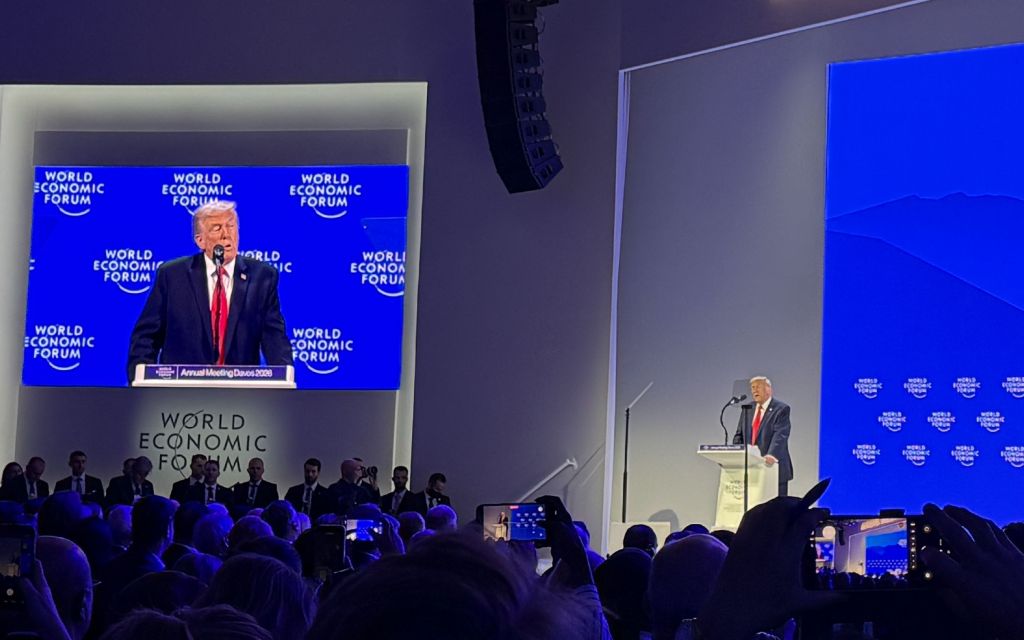
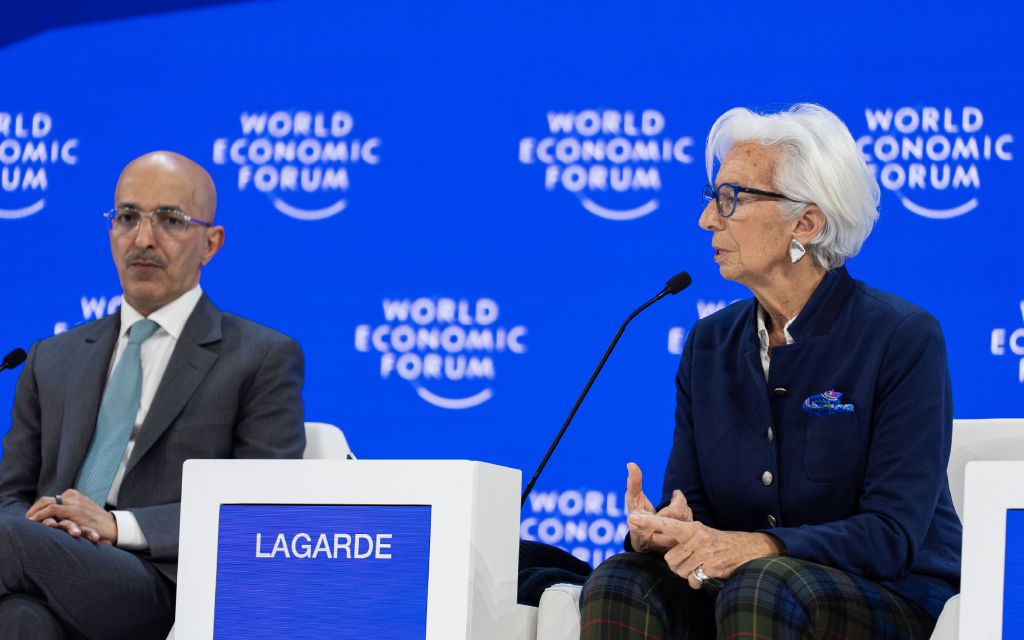
Last year, a day after his second inauguration, Donald Trump spoke by video to the Forum and promised a golden age for America. This time, he came in person to proclaim victory. With five cabinet secretaries and hundreds of American CEOs in tow, the President spent an extraordinary two days in the Swiss Alps projecting a 21st century version of American power. This is no stay-at-home superpower. In Trump’s vision, the world will trade and prosper more than ever, on America’s terms.  Close to three-quarters of global trade is still compliant with WTO rules. Inventory build-ups helped many companies escape the initial tariffs. A greater impact may come this year. But for the most part, “it’s still holding,” said Christine Lagarde, head of the European Central Bank, arguing the global economy is so intricate and intertwined even the U.S. cannot unravel it. Trump’s more mercantile Pax America is not just economic. He came with an unsolicited bid for Greenland that was rejected by his closest NATO allies. He left with a Board of Peace, supported by an unlikely collection of 19 countries with a combined GDP of $5 trillion, roughly equal to Germany. Only four (Albania, Bulgaria, Hungary, Turkiye) are in NATO, and only four (Argentina, Indonesia, Saudi Arabia, Turkiye) are in the G20. Will Trump be able to expand America’s reach without stronger partners? Or is this the new geometry of power?

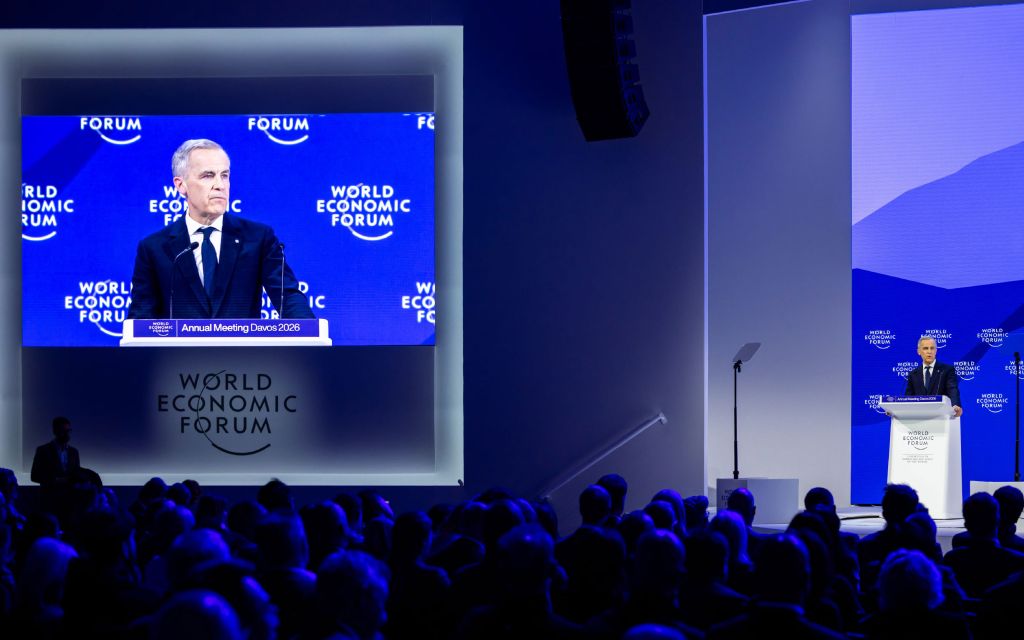
Mark Carney, long viewed as the quintessential “Davos Man,” gave a keynote speech that was widely celebrated for capturing the distraught mood of many there and crystallizing the desire for a new approach to international affairs. His tag line—“nostalgia is not a strategy”—resonated. Now he has to deliver on diversification. There’s no easy path. Canada’s closest allies in Europe are each struggling, economically and politically, weakened by the Ukraine war, immigration crises and a growing appeal of nationalism, which is now the biggest political force on the continent. Europe’s biggest economy, Germany, narrowly escaped a recession last year, after two years of decline. Chancellor Friedrich Merz called Europe “world champions of over-regulation” and at risk of losing its unity if it doesn’t reform. Canada will need more distant partners, too, particularly China and India, which the WEF estimates will account for nearly 40% of global economic growth over the next five years. Both emerging giants can be as tough as Trump when it comes to trade. The Persian Gulf beckons, too, with trillions of dollars of capital investment. But there, too, a new generation of economic partners have different political and legal systems—and social customs—to the neighbourhood where Canada grew up.

High above Davos, someone carved a message into a mountaintop glacier: “No King.” It was probably meant for the visiting U.S. President but equally could have been a message from European markets to the mighty greenback. King Dollar had a rough week, facing big questions as global trade winds shift, and countries and companies look to re-orient capital flows. The dollar still dominates 88% of global foreign exchange transactions, and 54% of global trade, which is why so many still cite TINA (There Is No Alternative). Or is there? The WEF opened to the startling news that Denmark’s largest pension funds had dumped U.S. treasuries in retaliation to the Greenland threat. A risk-off America vibe sent U.S. bond yields higher, reducing hopes for broader rate cuts. In moments like this, investors tended to stay in America, through real estate or stocks. This time, at least among Europeans, there was plenty of corridor chatter about a secular shift forming. One fund manager said his investors had asked him to sell down U.S. holdings. A few American tech executives said long-time European clients were cancelling orders. The euro, yen and Canadian dollar may play greater roles. The renminbi should gain prominence, although is years away from being a serious global alternative. Uneasy lies its head, but there’s still only one king wearing the currency crown.

The World Economic Forum was created in the 1970s to help Europe avoid the rise of socialism, and turn instead to free markets. A half century later, much of the West is again turning to the state to meet various economic ambitions—and the risks are evident. As countries, Canada included, seek to build back their militaries, build up their own technology foundations and become less reliant on the U.S.—home to roughly half the world’s financial capital—they are looking to leverage their own balance sheet and use other tools to direct capital to national priorities. These ambitions are so pronounced that many prime ministers and presidents seemed more like investment bankers working the Davos crowd. Advanced economies like Australia, Norway, Germany and South Korea do indeed have capacity to borrow more for investment, as do many emerging economic powers like Saudi Arabia. But capitalism is about more than capital; it’s about putting capital to work, with results. Singapore’s president, Tharman Shanmugaratnam, offered some sage advice, urging these new nation-state capitalists to be ruthless with investing, and with spending and regulation, too. Growth requires governments to focus on productive investments, including education, rather than redistribution—and a humble recognition that governments are inherently weak at building economic enterprises. If this new shot at state capitalism is to work, a new mindset will be needed, too.

Right after Donald Trump was first elected President, Xi Jinping came to Davos, to offer up China as a global leader for an emerging age. In the ensuing decade, Beijing has delivered—in renewable energy, nuclear power, critical minerals, pharmaceuticals and AI. So much so that Xi no longer needs to be there. This time, while the U.S. and Europe shouted at each other, he sent one of his less powerful vice premiers, He Lifeng, to position their country as a defender of multilateral trade and “inclusive globalization.” China experts said Beijing is not missing a moment to quietly advance its two biggest priorities—reunification with Taiwan and AI supremacy. Xi sees AI as critical to China’s future, and DeepSeek 4, the next-generation AI model expected in February, will show how far China’s come. On that other front, it’s believed the Chinese military, which conducted naval exercises around Taiwan at New Year’s, is ready to take the island by force, if necessary, within a year, which would give it sway over the world’s semiconductor industry that is so essential to AI. Democratic Senator Chris Coons, who was at Davos, fears the U.S. Administration doesn’t appreciate the need for “a network of allies with core values” to contain China. We’ll get a clearer picture when Trump and Xi meet in April, but don’t expect a grand bargain between the hegemons. Best case, Coons said, may be a series of “small landing points” to keep the world in balance.

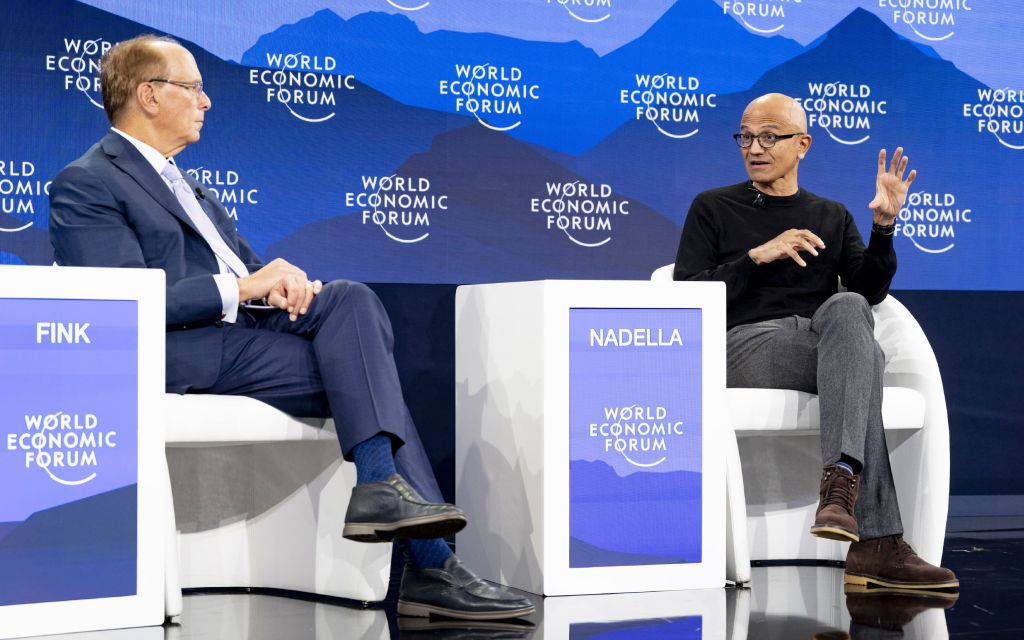
Data centres seem to be eating the world, electron by electron. But will the capital be there again in 2026 to feed their financial appetite? Data centre spending surpassed $500 billion last year, and when combined with broader electricity needs, according to McKinsey, may total $6.7 trillion over the next five years. The world has never seen an infrastructure boom like this. Data centre construction is now the single biggest contributor to U.S. economic growth; tech spending as a share of all investment is now running 50% higher than it was during the broadband boom of 2000, and triple what the U.S. spent on Interstate highways in the 1960s. Vacancy rates for data centres recently hit a record low of 1.6%, as developers bid up available spaces. “We may need more,” said Larry Fink, CEO of Blackrock. “If we don’t scale, China wins.” Equinix, a large data centre player, faces ten times the demand for every new unit they build. Land is no longer the constraint; energy is, as a medium-sized centre requires the energy of a small town. Such operations last year accounted for two-thirds of U.S. load growth, making them a new political target in boom states like Virginia and Ohio where electricity prices have soared. They’re also a growing concern in Africa and South-east Asia, the world’s fastest-growing regions, where countries have found themselves outbid for gas turbines and other power equipment.

The next energy crisis won’t be fueled by oil or gas; it will be strained by the world’s faltering electricity grids. Electricity demand globally is rising three times faster than total energy demand, driven by air conditioning and electric vehicles, as well as data centres. While 90% of Americans have access to air conditioning, the number is 20% in India, 18% in Indonesia and 5% in Nigeria—each with some of the world’s fastest-growing cities. Add to that the growing demand for EVs, which now account for a quarter of global car sales, up from 5% in just five years. Fatih Birol, head of the International Energy Agency, said the world will need 10,000 terra-watts of new electricity in the next decade, which is the equivalent of adding another U.S., Canada, Europe and Japan. Without any innovation breakthroughs, that would require 70% more copper, and a vast expansion of steel and critical minerals processing. Developments in large-scale battery storage and grid digitalization offer some hope, as most electricity systems still suffer a gross mismatch of supply and demand. But an unfortunate truth remains: it’s easier and faster to build power plants than it is to add transmission and distribution. Take this recent experience in Europe: the continent added 80 gigawatts of renewable energy supply only to find it didn’t have the capacity to transmit all that new electricity.

There were two vastly telling moments in Davos’s main Congress Hall, one speaking to scarcity, the other to abundance. Donald Trump went off script to lambaste renewable energy, especially wind which he said was for “losers.” A day later, Elon Musk used the same stage to profess a glorious future for renewables, especially solar which he said could power all of America if he had his way. Just give him a parcel of land, 160 kilometres by 160 kilometres, and tariff-free solar panels! Away from North America, renewables are still the driver of energy growth and have shifted from a “transition” source to a default for new supply in many markets. Europe reached roughly 50% renewable generation in 2024. In other fast-growing markets, renewables are increasingly seen as energy additions, not just replacements for fossil fuels. Falling battery costs (solar is down roughly 80% in India) and longer lifetimes (30–35 years) have helped shift economics from a simple cost per unit to a cost per lifecycle. But reliability remains a challenge, which will require more battery storage, pumped hydro, and hybrid round-the-clock systems. But that’s happening in places like India, which has installed 2.7 million rooftop solar systems and 3.1 million solarized pumps and has already hit its 2030 target for renewables to account for roughly 50% of non-fossil fuel energy.

AI has shifted from an experimental technology to foundational infrastructure—and now an operating system for companies and governments. The competitive advantage is not just model innovation; it’s diffusion and how fast firms can beat their competitors to transform. As diffusion accelerates, Anthropic co-founder and CEO Dario Amodei sees 2026 as the year when AI systems build AI systems, including within firms, in ways that could upend entire business models. Demis Hassabis, co-founder and CEO of DeepMind, said the advantage will go to “continuous learners” who track what models are doing and adjust strategies and workflows. Seizing that approach, most CEOs have taken AI ownership out of the tech department and parked it on their desk. A BCG survey, released at Davos, found that 72% of global CEOs see AI as a core part of their mandate, with half believing it will define their tenure. Companies plan to double AI spending this year, even though a 2025 MIT study found very few adopters had seen a financial return. David Sacks, the Silicon Valley guru who is Donald Trump’s AI czar, sees the need for leaders, in government, business and media, to dispel fears, and embrace the chance to disrupt and innovate. He cited another study that found 83% of Chinese are optimistic about AI, compared to 39% of Americans. Sacks worries that “a fit of pessimism” will result in the U.S. losing the AI race due to what he described as a “self-inflicted injury.”

There’s a new financial math for AI. It’s what Microsoft CEO Satya Nadella calls “tokens per dollar per watt”—basically the energy cost per unit of compute. Think of it as a kind of basic wage and productivity measure for AI. And the companies, and countries, that can drive down that unit cost will be positioned to win in the data economy. This new math may fundamentally change the nature of human work, too. Think of it as “data x energy x labour = success.” The C-suite consensus at Davos seemed to be that labour, like data and energy, will be needed even more. CEOs said the entry-level “job cliff” is overstated; the real problem is a widening skills mismatch, as most roles will require a re-bundling of tasks and skills. The winners will be the workers (and firms) that can integrate and operate with AI. This transformation is resetting corporate ladders, especially in professional services and governments, where basic tasks like document review, screening and modelling can be done by machines. New apprenticeship designs will be the hot HR need, to build judgement, context, and supervision skills. More model design and modification will be pushed to the frontlines, where employees can create small pieces of automation to transform their work. All this can flatten organizations, and give advantage to those with abundant data, cheap energy and AI-savvy teams.

Growing divisions in the world, and within countries, is a matter of trust. And we’re losing it. Stefanie Stantcheva, a Harvard economist, finds it’s especially acute for her generation—those under 40—who see a zero-sum world and their slice shrinking. She shared research at Davos showing how distrust now spans the political spectrum, with a wide range of millennials feeling other groups have captured government agendas through mainstream media, corporate influence and old-school politics. That tension will grow as aging voters in the West demand more income and health security, perhaps at the cost of economic and national security. The Edelman Trust Barometer, which surveys 34,000 people in 28 countries and is released annually at Davos, found societies sliding from grievance into insularity; seven in 10 people are hesitant or unwilling to trust those with different values, backgrounds, or information sources. Trust is also shifting away from institutions to “people like me,” neighbours, co-workers, and one’s CEO. Business is now seen as both most competent and most ethical, surpassing NGOs on ethics for the first time, while government and media remain the least trusted. Most starkly, optimism is fading: in many countries, majorities no longer believe they or their families will be better off in five years, citing economic anxiety, AI, misinformation, and global conflicts.

Download the Report

Language Flag Filename

rbc_language_toggle_menu_flag

To judge by Davos’s main promenade, globalization is alive and well. Yes, the U.S. took over a church and shop to celebrate America First. But there were far more storefronts promoting Brazil, Indonesia, the Philippines and Nigeria. India wrapped an entire hotel on the promenade, where thousands schlepped every morning from their crash pads to the Congress Centre, and back at night from dinners and nightcaps.

Is this a false spring, just like the mild week in Davos? Or the beginning of what Christine Lagarde called “Plan B” and a more diversified global economy?

The European Central Bank president told the closing session of the World Economic Forum that she “is not on the same page” as Mark Carney’s view of a global rupture—but does see an important diversification of trade underway.

According to the WEF’s own research, close to half of global growth over the next five years (2025-30) will come from Asia, with China accounting for 23% and India another 15%, while the U.S. will produce 11%. Combined, the G7 will account for only 18.5% of growth. 

If it feels like a new age of diversification, one should never forget the gravitational pull of the two economic superpowers, which over the past decade (and longer) have consumed much of the world’s capital and trade. Case in point: China now accounts for about 40% of published studies on drug research, while Europe’s share has dropped from 20% to 12%. Guess where most of the world’s drugs will come from in the 2030s.

With so much in flux, who will dominate the world’s future trade zones? I came away from Davos thinking three forces will help shape the answer:

1. Balance-sheet strength. We may be on the verge of some heavy government (and perhaps private sector) borrowing to underwrite all that’s needed for diversification—from new supply chains to infrastructure. Points to the U.S. for owning the world’s reserve currency, but a range of middle powers—Germany and Canada, among them—can borrow plenty on their own.

2. Artificial Intelligence. It’s sucking up much of the world’s private capital, and will determine a lot of trade outcomes as it (along with robotics) transforms production. Yes, the U.S. and China dominate, but if AI becomes available to all, like the Internet, advantage will go to those with energy to power all those learning algorithms and the entrepreneurial brains to put the results to work. The eight biggest U.S. tech companies have $18 trillion of equity value to leverage—and a lot more domestic energy than China or Europe.

3. Demographics. It’s the sleeper trend, as the West (and Far East) tumble over demographic cliffs. Even in an age of AI, trade still relies on humans to help make and ship things and humans to buy those things. Africa’s population is on course to hit 2.5 billion by 2050, when it will be home to 25% of the world’s working age population. 

Some shrewd advice I heard was for companies to think country, supplier and currency—and have an option for each. Call it a matrix of Plan Bs. Or what Carney termed “variable geometry.” 

It’s the new math.

— John Stackhouse

Bank of Canada Q4 survey shows Canadian businesses continue to be negatively impacted by trade tensions, but some are increasing non-U.S. exports

  • 33% of Canadian firms reported they are strongly impacted by U.S. trade policies. A small but increasing share of businesses reported higher sales to non-US markets. Despite weaker sales to U.S. customers, most exporters to the U.S. have not diversified into other markets citing barriers like investment in specialized equipment, compliance with regulatory requirements, and transportation costs.

  • This signals, albeit modestly, that Canadian firms are willing to expand in other markets. However, immediate economic pressures are significantly constraining hiring, investment, and diversification efforts.

Canada agrees to new partnership with Qatar to cooperate on trade, investment, and defence

  • Canada and Qatar agreed to conclude FIPA negotiations, signed an MoU to establish a Joint Economic Committee (JEC), expand air services, and increase defence collaboration (including more exports from Canada’s defence sector).

  • This is the latest in a series of wins, following last week’s agreement with China, for the Canadian government’s diversification efforts. The value of merchandise trade between Canada and Qatar in 2024 was $325 million, leaving lots of room for growth.

European lawmakers delay Mercosur trade pact over legal concerns

  • EU ratification of this agreement, decades in the making, with South American economies has been postponed by lawmakers seeking an opinion from the European Court of Justice.

  • This is the latest hurdle in a protracted process, following pressure from European farmers, which could delay the trade pact by a further two years. However, German Chancellor Friedrich Merz called on the European Commission to provisionally apply the deal, which would create one of the world’s largest free-trade zones, covering over 700 million people, and ~20% of global GDP, in recognition of the current “geopolitical situation.”

 First Chinese order of Canadian canola in months comes following trade mission

  • Prime Minister Mark Carney’s visit to Beijing has led to a Chinese importer buying 60,000 metric tons of Canadian canola, the first cargo order of its kind since China halted imports in October. This comes as China is expected to lower tariffs on Canadian canola to 15%. Canadian agriculture minister Heath MacDonald encouraged Chinese investment in Canada’s agri-food sector this week, highlighting the potential for collaboration in domestic value-added processing and research.

  • Saskatchewan, Canada’s biggest canola-producing province and the province with the highest year-over-year growth in wholesale trade, is especially well positioned to capitalize. Premier Scott Moe (who was on the trip to China) has emphasized the benefits for his province and Canada’s agricultural industry more broadly.   

— Thomas Ashcroft
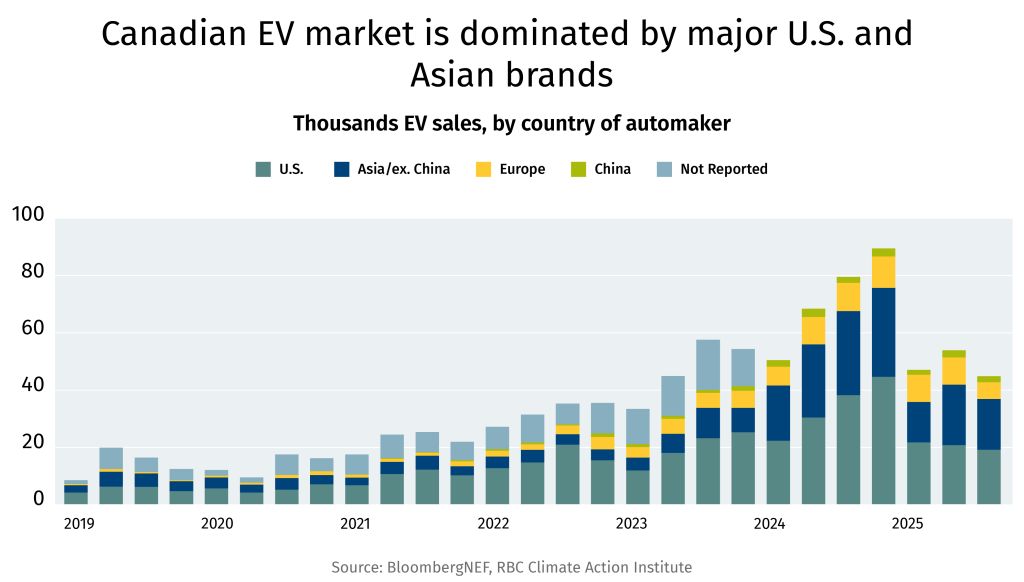
EV sales by country

Canada plans to allow 49,000 made-in-China EVs at much lower tariffs in return for easing levies on Canadian agricultural products. Here is what you need to know about the deal and its implications:

  • About half of the vehicles imported from China are expected to cost less than $35,000 by 2030. Average EV purchase price in Canada in 2024-25 was around $67,000.

  • Canadian EV sales were projected to remain largely flat in 2026 following a 30% decline last year. To size up Chinese imports, 49,000 would represent a quarter of Canada’s annual EV market. Ontario Premier Doug Ford is worried it could impact sales—and jobs—from existing manufacturers.

  • Europe’s strategy could serve as an alternative roadmap for Canada on autos: The continent worked with Chinese carmakers to level the playing field, and set targeted tariffs aimed at offsetting the impact of subsidies. Even with that, however, Chinese brands have captured 10-15% of the EV segment in Europe.

  • The Canada-China thaw comes ahead of critical CUSMA renegotiations that could disrupt the 80% of Canadian exports that enter the U.S. market tariff-free. Could it further complicate U.S.-Canada negotiations?

— Farhad Panahov

Language Flag Filename

rbc_language_toggle_menu_flag

The U.S. loves heavy oil. The blend is vital for diesel, jet fuel and petrochemicals, and Canada is, by some distance, its biggest foreign supplier. However, a U.S. plan to influence and revive Venezuelan oil has raised concerns that Canada—already facing U.S. pressure on several other domestic industries—could start losing market share to Venezuelan heavy crude in a few years. It could amount to a Washington squeeze on Canada’s most prized resource.

Imports of crude and liquids into the U.S., the millions of barrels per calendar day

U.S. crude import patterns reflect a clear structural divergence between Canada and Venezuela. The result is a fundamental reorientation of U.S. import dependence toward Canadian supply, reinforced by reliability, infrastructure, and long-cycle capital investment.

U.S. Imports, millions of barrels per calendar day

Venezuelan crude once dominated Gulf Coast imports, but its collapse created space that has only partially been filled by Canadian barrels. The Gulf Coast is seen as a battleground, but only 10% of total Canadian imports flow into the region known as PADD 3. Most Canadian crude growth has occurred within the Midwest refinery region, known as PADD 2, which accounts for 69% of total Canadian export growth into the U.S. over the past three decades.

Total U.S. Refining capacity by refining region, millions of barrels per stream day

U.S. refining capacity growth has been concentrated in PADD 3 and PADD 2, reinforcing the system’s orientation toward large-scale, complex refining hubs. The Gulf Coast’s dominance reflects decades of investment designed to process heavier and more diverse crude slates, positioning it as both a domestic refining centre and a globally relevant supply hub.

Total U.S. coking operating capacity by refining region, millions of barrels per stream day

Coking capacity remains a defining feature of the U.S. system’s ability to process heavy crude, with the majority of investment concentrated along the Gulf Coast. The steady build-out of coking units over time highlights how refiners structurally adapted assets to heavier barrels, further entrenching supply relationships that favor Canadian crude.

U.S. Total Crude + Product Exports, millions per barrel per calendar day

The U.S. energy system is increasingly focused on exports, with petroleum products accounting for majority of outbound volumes over time. This underscores the Gulf Coast’s role not only as a refining hub, but as a critical petrochemical and export platform. For Canada it reinforces the importance of market access, blending, refining, and re-export pathways within an evolving global trade landscape.

U.S. investments in western hemisphere in the mining, quarrying, oil and gas extraction sector

For all the cross-border integration, U.S. capital investment in the Canadian resource sector (mining, oil and gas) has fallen by more than half from its US$39.1 billion peak in 2011. Meanwhile, U.S. investments into other Western Hemisphere countries has steadily grown from US$16 billion in 2000 to US$64 billion in 2024, even without Venezuela.

The competition for investment dollars from the U.S. into the Western Hemisphere is growing—Canada will need to lock in American capital to ensure it preserves its pre-eminent position in the U.S. market.

Language Flag Filename

rbc_language_toggle_menu_flag

The world is undergoing a series of once-in-a-generation shocks and adjustments. Canada needs to adjust, too. Rapidly. 

Some of the economic structures and patterns that brought Canada into this century may not live out this decade. Political and security alliances, so necessary to peace and order, are in the midst of a realignment. And advanced technologies are disrupting the very nature of work, commerce and human interaction — so much so, and so quickly, that even last year’s assessments seem distant. 

The compression of time and risks means no company or government, public enterprise or community organization, can afford to wait and watch.

Eurasia Group and RBC Thought Leadership created this report, the first of its kind, to help Canadians navigate those profound risks and sea changes in 2026. The following is a combination of five assessments from Eurasia Group’s Top Risks 2026 outlook — the global ones most likely to impact Canada — and five assessments from RBC Thought Leadership, exploring the most significant domestic forces that may shape the year ahead. These are not predictions or forecasts: rather, they are carefully considered and researched analyses of the trends, forces and interests shaping our economy and policy environment, informed by economic data, market insights and interactions with leading businesses, investors and policymakers. They’re designed as lighthouses, rather than navigation systems. 

This report is also a foundation for a new global relationship between Eurasia Group and RBC, to help firms and governments assess and manage their own risks in these unprecedented and volatile times. In the year ahead, we will publish more on these issues and convene leading thinkers in the economy and government to advance our collective understanding of the risks around us. In June, we will host the annual Canada-U.S. Eurasia Group summit in Toronto, to help shed more light on the risks, and opportunities, as these two countries and neighbours — both extraordinary in their own right — advance, and as needed redirect, their economic relationship in this rapidly changing world. 

The challenges ahead can seem daunting, even overwhelming. But as we’ve seen through history, including recent history, moments of uncertainty — that amorphous cousin of risk — are when those with clear heads and confident minds excel. 

RBC Thought Leadership

Canada is looking to build its military, develop an industrial base and forge new commercial partnerships at a wartime pace. A failure to execute could lead to others, notably the U.S., stepping in.

Canada’s enthusiasm for rapid militarization began the moment Donald Trump demanded more from America’s NATO allies and deepened as he mused about taking over parts of the Western Hemisphere, from Panama to Greenland, even putting the idea of Canada as the 51st state on the table. For Canadians, the exercise was initially a budgetary one, finding ways to allocate tens of billions to its small and often overlooked military. But when Trump sent the U.S. military into Venezuela, the warning for Canada and its armed forces took on a sharper focus. Borders are no longer gates. They’re hard lines that need to be defended.

For Canada, the task of building a big military—the biggest since the Second World War—is daunting. In war, extraordinary measures like state-run supply chains can be implemented quickly. In peacetime, each step needs more negotiation—that’s made even harder with a public that barely remembers the losses of the Afghan mission and a military bureaucracy that has struggled with much smaller magnitudes of procurement and deployment. The industrial base is a further challenge. Mention the words “military-industrial complex” and most Canadians will say “no, thanks.” Before Trump returned to power, Canada ranked 27th out of 31 NATO nations when it came to military spending as a share of GDP. In fact, defence spending had languished for the past 25 years at levels well below the late 20th century averages. Military enrolment has also been in terminal decline, with less than two service members for every 1,000 people. Even peacekeeping has declined to a few dozen blue helmets.

Read the full risk here.

Eurasia Group

U.S. Political Revolution

The United States is experiencing a political revolution: President Donald Trump’s attempt to systematically dismantle the checks on his power, capture the machinery of government, and weaponize it against his enemies. Last year, we warned about the “Rule of Don”; what began as tactical norm-breaking has become a system-level transformation beyond partisan hardball or executive overreach—qualitatively different from what even the most ambitious American presidents have attempted (please see Box 1: Trump vs. FDR). With many of the guardrails that held in Trump’s first term now buckling, we can no longer say with confidence what kind of political system the United States will be when this revolution is over.

In Trump’s view, he overcame a rigged election, two partisan impeachments, dozens of unjust felony convictions, and two assassination attempts—one a whisker’s breadth from killing him—to stage the greatest political comeback in American history. President Trump sees the principal threat to him and his allies as domestic, not external, and he believes he has a mandate for retribution. The administration views this project not as an assault on democracy but as its restoration, a necessary purge of a political system captured by a deeply corrupt establishment that had already weaponized government against them. Over 77 million Americans voted for Trump in 2024, and many of them sympathize with that diagnosis: Among 2024 voters who said democracy mattered to their decision, a majority chose Trump—not because they saw him as a champion of democratic values, but because they believed the system was already broken and wanted someone who would disrupt it. “Trumpism” is structural, and at this most fundamental level, Trump’s supporters are getting what they asked for.

To read the full risk, download the report.

RBC Thought Leadership

Canada is aiming to double non-U.S. exports through two of its biggest trade antagonists, China and India, even as Canadian investment continues to pour into the United States.

Since Mark Carney launched his “elbows up” campaign to get the country to trade more with the rest of the world, and with each other, Canadians have spent and invested more in the United States, even as Americans are doing less in Canada. The strong U.S. economy, and tax breaks under the Big Beautiful Bill, have reinforced the attractiveness of the world’s largest market for Canadian investors. From pension funds to mutual funds, more Canadian dollars than ever have headed south. Business investment has done the same. Carney may need to do even more on taxes and regulations to keep Canadian investments at home.

For all the bark, and bite, of tariffs, Canadian consumers have been slow to change habits, too. Highly visible brands like Tennessee whiskey were perhaps an easy early target. Florida and Arizona vacations have taken a hit, too. But in large measure, Canadians are still watching Netflix, buying Fords and drinking Coke at the same rate as before the trade war.

Read the full risk here.

Eurasia Group

Europe Under Siege

The hollowing out of Europe’s political center has been a decade in the making. France, Germany, and the United Kingdom each enter the year with weak, unpopular governments under siege from the populist right, the populist left, and an American administration and state-aligned social media openly rooting for their collapse. None face scheduled general elections. Yet all three risk paralysis at best and destabilization at worst—and at least one leader could fall. The consequences won’t stay contained: Europe’s ability to address its economic malaise, fill the security vacuum left by America’s retreat, and keep Ukraine in the fight will suffer.

To read the full risk, download the report.

RBC Thought Leadership

A shift in global oil and gas prospects, from Venezuela to Qatar, changes the investment outlook for Albertan exports—and the big infrastructure projects designed to get them to overseas markets.

Canada’s ambitions to be an energy superpower—including oil and gas—is being tested after the U.S. intervention in Venezuela. But the challenges lie well beyond Canada’s immediate neighbourhood. Long-term demand for oil and gas remains an open question, especially as Asia continues to turn to electrons to power growth. A global surplus of supply, including American LNG, clouds the picture further. And then there’s the question of global growth. No growth, no need for more energy, from Canada or anywhere else.

In one strategic swoop in Caracas, U.S. President Donald Trump has attempted to ringfence the Americas with Washington as its most consequential capital. In that respect, Trump may have weakened Canada’s most valuable negotiating card—energy exports. A resurgent Venezuela crude production could displace Canadian oil in the U.S. and leave it scrambling for market share with Saudis and others elsewhere. It’s a potential competitive shock. Over the past 25 years, Canada had solidified its position as the foremost supplier of oil and gas to the world’s biggest oil market, accounting for nearly three out of every five imported barrels entering the U.S. An industry built to serve America now pumps out a record five million barrels per day, compared to just over two million bpd in 2000, with more than 90% of its exports ending up in refineries in the U.S. Midwest, West Coast and the Gulf Coast.

Read the full risk here.

Eurasia Group

China’s Deflation Trap

China’s deflationary spiral will deepen in 2026, and Beijing won’t do anything to stop it. With the 21st Party Congress looming in 2027, Xi Jinping will prioritize political control and technological supremacy over the consumption stimulus and structural reforms that could break the cycle. Beijing has the means to prevent a crisis, but living standards will deteriorate, the fallout will spread abroad, and the world’s second-largest economy will remain stuck in a trap of its own making.

Home prices in China have been falling for four and a half years—a household wealth destruction on par with America’s 2008 crash, except it’s still accelerating. Consumer confidence, investment, and domestic demand have cratered with it. Beijing bet big that high-tech manufacturing would fill the gap left by property. Instead, state-driven investment has created overcapacity, and weak domestic demand means there aren’t enough buyers to absorb it.

The result is “involution”: too many Chinese firms chasing too little demand, slashing prices to survive. Margins collapse, forcing even well-run firms to cut wages and jobs to stay afloat. Workers spend less. Demand weakens further, so firms cut prices again. Meanwhile, debts grow harder to service with each turn of the cycle. Banks and local governments keep zombie firms alive—rolling over loans, protecting local champions—which keeps overcapacity entrenched. The debt-deflation spiral feeds on itself. Donald Trump’s tariffs last year made the situation worse, closing off a critical export market and confronting Chinese firms with a grim choice: slash prices to find buyers outside the United States, or transship goods through third countries to reach America anyway. Either path squeezes margins further. Over a quarter of listed Chinese companies are now unprofitable, the highest share in 25 years. 

To read the full risk, download the report.

RBC Thought Leadership

An over-correction to the recent surge in irregular immigration is squeezing employers, hammering colleges and universities, and threatening to delay a new wave of resource projects and infrastructure builds—at the same time as Canada is nearing a demographic cliff.

Canadian public and political sentiment toward immigration is increasingly negative. But the sentiment is running contrary to the country’s needs: Canada’s aging population is facing declining fertility rates, leaving immigration central to the expansion of the skilled workforce. Cutting back on immigration drastically could lead to a rapid dip in population, hurting efforts to maintain living standards, drive economic and business activity and meet near-term economic ambitions.

The Mark Carney government’s plan to clamp down on immigration comes after years of expansionary policy. Temporary residents increased beyond capacity during Justin Trudeau’s decade-long tenure that began in 2015. Housing infrastructure and community services were overloaded, and productivity declined as temporary low-wage workers removed the incentive from some businesses to invest in technology, training or equipment. Targets for new temporary residents, including students, are down by over 550,000 in 2026 compared to 2024. And permanent resident targets are down by over 100,000 from 2024 admissions. Even with these reductions, Canadians feel immigration levels are too high.   

Read the full risk here.

Eurasia Group

AI Eats Its Users

Under pressure to generate revenue and unconstrained by guardrails, a number of leading AI companies will adopt business models in 2026 that threaten social and political stability—following social media’s destructive playbook, only faster and at greater scale.

We remain bullish on AI’s revolutionary potential. Today’s frontier models reason through complex problems, show their work, and are embedded in coding, research, and knowledge workflows. The hyperscalers are offloading large chunks of software development to AI, accelerating their own R&D cycles. In biotech and materials science, AI is opening new research pathways—though commercial breakthroughs remain mostly ahead of us. Hundreds of millions of people now use chatbots daily for everything from drafting emails to debugging code and learning new skills. This is real, and it’s just the beginning.

But AI can’t live up to investors’ expectations in the short term. Even after hundreds of billions of dollars of investment, the most advanced models still hallucinate. Their capabilities are jagged: dazzling at some tasks, unreliable at others (and often unpredictably so). That inconsistency makes them hard to deploy in high-stakes applications where errors are costly. Business adoption has been uneven, with only about 10% of U.S. firms using AI to produce goods and services, according to the Census Bureau. Many companies report significant productivity gains, but surveys suggest most have yet to see meaningful bottom-line impact. Real productivity increases will arrive through wide diffusion of the technology across the economy, but that takes time. Yet markets have priced in revolution, not evolution.

To read the full risk, download the report.

RBC Thought Leadership

Canada’s economic prospects are threatened not just by external shocks and demanding neighbours; they’re up against a deepening asymmetry of federalism that makes a unified economic strategy harder to design, sell, and implement.

Different views among Ottawa, the provinces, and Indigenous governments over how to use natural resources, fund and deliver education, and stabilize a strained health-care system are pulling Canada further toward a patchwork of policy regimes just as it confronts tough trade talks with a more transactional United States and intensifying global competition. Constitutional tools that were once seen as last resorts—the notwithstanding clause, aggressive jurisdictional challenges, demands for exemptions from national regulations and standards, even provincial votes on autonomy—are becoming more commonplace, raising the odds that provinces and Indigenous groups will weaponize hard and soft vetoes on national priorities. One Canada, maybe, but many nations within.
The consequences for national unity are more serious than at any point since the 1990s because fragmentation now comes with cheerleaders and sponsors abroad. A divided global order gives foreign governments, activist networks, and corporate actors more opportunities to exploit jurisdictional tensions, whether by privileging particular provinces in supply-chain decisions, funding litigation and media campaigns around resource projects, or amplifying separatist narratives. For geopolitical rivals, anything that weakens Canada’s coherence as a U.S. ally and G7 partner could even become a feature, not a bug, as sub-national players and Indigenous rights-holders seek to express their voices more assertively over energy, climate, industrial policy, internal trade and, most critically, bilateral trade with the U.S.

Read the full risk here.

Eurasia Group

Zombie USMCA

North American trade will be stuck in limbo in 2026. The United States-Mexico-Canada Agreement (USMCA) won’t be extended, updated, or killed. It will stagger on as a zombie, keeping businesses and governments guessing while President Donald Trump continues negotiations with America’s two largest trading partners.

The agreement is up for its mandated review this year, when the parties can extend it for an additional 16 years. But Trump wants to avoid the constraints of a new trilateral deal so he can keep using bilateral leverage to squeeze economic and political concessions from both countries. Canada already scrapped its digital services tax. Mexico is imposing tariffs on China. Both are cracking down on fentanyl flows. Washington gave up nothing in return. Why lock into an agreement when the current approach keeps delivering for the U.S. president? Neither Canada nor Mexico can afford to walk away. The United States is the destination for roughly 75% of Canadian exports and 80% of Mexican exports. Trump holds most of the cards and he knows it.  

The result will be a “zombie USMCA” that is neither fully dead nor alive—and a North American trade zone buffeted by chronic uncertainty. 

To read the full risk, download the report.

Download the Report

Language Flag Filename

rbc_language_toggle_menu_flag

This is a part of RBC Thought Leadership and Eurasia Group’s joint report

Canada is looking to build its military, develop an industrial base and forge new commercial partnerships at a wartime pace. A failure to execute could lead to others, notably the U.S., stepping in.

Canada’s enthusiasm for rapid militarization began the moment Donald Trump demanded more from America’s NATO allies and deepened as he mused about taking over parts of the Western Hemisphere, from Panama to Greenland, even putting the idea of Canada as the 51st state on the table. For Canadians, the exercise was initially a budgetary one, finding ways to allocate tens of billions to its small and often overlooked military. But when Trump sent the U.S. military into Venezuela, the warning for Canada and its armed forces took on a sharper focus. Borders are no longer gates. They’re hard lines that need to be defended.

For Canada, the task of building a big military—the biggest since the Second World War—is daunting. In war, extraordinary measures like state-run supply chains can be implemented quickly. In peacetime, each step needs more negotiation—that’s made even harder with a public that barely remembers the losses of the Afghan mission and a military bureaucracy that has struggled with much smaller magnitudes of procurement and deployment. The industrial base is a further challenge. Mention the words “military-industrial complex” and most Canadians will say “no, thanks.” Before Trump returned to power, Canada ranked 27th out of 31 NATO nations when it came to military spending as a share of GDP. In fact, defence spending had languished for the past 25 years at levels well below the late 20th century averages. Military enrolment has also been in terminal decline, with less than two service members for every 1,000 people. Even peacekeeping has declined to a few dozen blue helmets.

The Mark Carney government has taken the challenge head on. Its first budget injected $81.1 billion over five years. Now, Ottawa is trying to reduce the heavy concentration it spends in the United States, taking gunboat diplomacy in a very different direction: its ministers have travelled the world in search of equipment like submarines, and much more, from any ally other than the U.S. Relations with Japan and Germany have been transformed by the idea of peacetime rearmament. Same with South Korea and Sweden.

But now comes the hard part: making choices. Ottawa will inevitably irk an ally, and may very well irk its own military brass, by choosing boats, planes and weapons that aren’t as effective, on the battlefield or the balance sheet, as those American options. The challenge of “interoperability” is even greater if the Canadian military is to continue to share responsibility with the U.S. for the defence of North America. Currently, 100% of Canada’s fighter aircraft, 91% of helicopters, and more than 75% of other mission aircraft originate from the U.S. If the U.S. feels Canada’s non-American equipment isn’t up to the task of defending the Arctic or, for that matter, the North Atlantic, they may just do it themselves, even if it means torpedoing Canada’s sovereignty.
The vast web of red tape in Canada’s defence procurement system—and a bureaucracy trained to say “maybe”—has contributed to draining the private sector of much of its entrepreneurial flex. In recent budgets, fully a quarter of the Industrial and Technology Benefits Policy, or $15.3 billion, was listed as unallocated, due to deployment frictions, certification gates and poor definitions. Even the government admits it takes 15-plus years for a major fleet acquisition. And a recent study found that $18.5 billion in planned capital went unspent over a five-year period. A new ‘Buy Canadian’ military mandate may lead to, at least in the short term, more dollars chasing fewer producers. But greater cyber-security requirements—and a lot of the new spend will go to cyber defence—stands to cause further delays.

To break through that bureaucratic blockade and boost military spending at home, the Carney team opened a new Defence Investment Agency to do something soldiers are trained to do on the battlefield but is less common in government: move fast. The new money hasn’t even started to flow at speed or scale, and regions are insisting on their share, whether in the national interest or not. This will inevitably lead to lower efficiencies and higher costs, even if it does create more jobs for Canadians. It will also challenge Canada to be competitive in the growing global arms market, as it seeks to trade with allies in Europe and Asia—but will need scale and excellence to meet their standards.

Of course, missing in these equations is the sort of private capital that has helped the U.S. military-industrial complex grow. That new kind of military capitalism will be novel for many Canadian operators, and the military. Canada is seeking to play a leading role in the nascent Defence, Security and Resilience Bank—a kind of World Bank for NATO and its allies—which will draw on the strengths of members’ balance sheets to help them borrow on capital markets to finance their own budgets and supply chains. The government’s financial institutions, such as the Business Development Bank and Export Development Canada, will need to play an even greater role in helping small- and medium-sized Canadian businesses raise the capital needed to serve the so-called “primes”—or prime contractors—that sit at the top of every supply chain.

Canada’s defence industrial base includes about 600 firms—compared to 60,000 in the U.S.—and most employ fewer than 250. Those small but mighty Canadian firms have an equally small capital base. Many have been lucky to survive through the demand shocks of various governments and militaries announcing programs and then delaying them, or even shutting them down. Adding to the challenge is the fact that half of Canada’s military exports go to the U.S., which may decide to close the door if Canada snubs the big American primes. A more hidden risk for Canadian SMEs is entanglement. The IP in a complex defence product is often controlled by large operators, usually multinationals, that can shut down a small supplier.

Generals, and their political masters, love their toys, which is why so many photo ops are with big hulks of steel and not small groups of men and women doing the work behind the machines. Still, more of those people will be needed—but are harder to find. Canada’s military employs only 0.38% of the national labour force—down from 0.56% a decade ago, and well below Britain (0.58%), Australia (0.60%) and the U.S. (1.69%). The Canadian military, which has struggled to get close to 100,000 personnel, may need to double or triple in size in the next decade. And it’s not just fighter pilots and combat soldiers. It’s base operators in the Far North and cyber coders across the south. Currently, the Canadian Armed Forces (CAF) is roughly 15,000 members short of its intended size, creating persistent readiness and sustainment gaps. A lack of speed is to blame. Median recruiting timelines are upwards of 271 days, more than double the official target. The delays are sometimes greater for Canada’s large immigrant population, which needs to undergo an even longer security clearance. It’s no wonder more than half the young Canadians who apply ultimately pull out. And then there’s the hurdle of training. The CAF’s training centres are running at 80% capacity due to a shortage of instructors. That pressure may only grow as the military becomes more STEM-driven. The defence sector is 2.5 times as STEM intensive as general manufacturing.

Remilitarization is central to Canada’s effort to carve out a new relevance in the world, especially to allies, old and new. Even before Trump’s second term began, Canada was significantly growing its military participation in eastern Europe in response to the Russian invasion of Ukraine. The Canadian deployment in Latvia is one of Canada’s biggest peacetime missions anywhere and seen in Europe as a meaningful commitment to the continent’s defence. A growing Canadian military may also play a role in defending the Caribbean from drug cartels, as well as unrest in places like Haiti. And, of course, it will define itself once again in the Arctic, on land, in the air, under the ice—and overhead in low orbit, where the next battlefields may play out.

A more sophisticated and better capitalized defence industry—and a more dynamic armed forces—may even help shape the next chapter of Canada-U.S. relations. As partners, not rivals, in taking on the greater threats of China, Russia and Iran. The Great White North’s geographic sanctuary has long been a blessing. Any loss of that sanctuary will challenge the country anew. But for those Canadians who study their history, the role of conflict—present and hidden—has never been far from sight.

Download the Report

Language Flag Filename

rbc_language_toggle_menu_flag

This is a part of RBC Thought Leadership and Eurasia Group’s joint report

Canada is aiming to double non-U.S. exports through two of its biggest trade antagonists, China and India, even as Canadian investment continues to pour into the United States.

Since Mark Carney launched his “elbows up” campaign to get the country to trade more with the rest of the world, and with each other, Canadians have spent and invested more in the United States, even as Americans are doing less in Canada. The strong U.S. economy, and tax breaks under the Big Beautiful Bill, have reinforced the attractiveness of the world’s largest market for Canadian investors. From pension funds to mutual funds, more Canadian dollars than ever have headed south. Business investment has done the same. Carney may need to do even more on taxes and regulations to keep Canadian investments at home.

For all the bark, and bite, of tariffs, Canadian consumers have been slow to change habits, too. Highly visible brands like Tennessee whiskey were perhaps an easy early target. Florida and Arizona vacations have taken a hit, too. But in large measure, Canadians are still watching Netflix, buying Fords and drinking Coke at the same rate as before the trade war.

A couple of generations ago, in the Trudeau 1 era, when Canada was trying to shift away from a Vietnam-era America, similar tensions reverberated through Canadian living rooms, and board rooms. The proverbial U.S. elephant and Canadian mouse was about more than sneezes and colds; it was about dependencies (plural) in the economy, culture and ultimately sovereignty. A new approach emerged to the binary option of dependence versus independence, known as the Third Option in which Canada would become more closely tied with a reconstructed Europe, a re-emerging Asia and a resurgent Third World.

Back then, there was strong concern about Canada as a branch plant economy—meaning American branch plants. But 50 years on, instead of playing from a position of strength, Canada’s search for new global alliances comes at a moment of maximum dependence on, and maximum uncertainty about, the United States. That dependency has been built over the past century through defence and deterrence partnerships like the North American Aerospace Defense Command (NORAD), trade and investment cooperation and, for Canada, a profile that rested on being the ally most like—but not—America. Now, the central risk is not that Canada will suddenly “break” with its neighbour and ally but that attempts to diversify away from U.S. power will expose how little hard leverage Ottawa has with other partners—and how quickly a more transactional White House can weaponize asymmetry in defence, intelligence, and trade. Geography still is destiny.

Canada’s struggle for more independence starts with the economy. The impact of Trump’s tariffs has included the loss off tens of thousands of manufacturing jobs, and body blows to the auto, steel and lumber sectors and regions that depend on them. If those tariffs are sustained, most projections suggest a prolonged period of slow growth for the economy, which will further erode Canada’s relevance on the world stage. The Trump tariffs were felt quickly and deeply, driving down Canada’s overall exports by close to 10% by mid-2025.

Compounding the challenge of dependence, while Canada’s trade deficit with the U.S. is worsening, its investment surplus is growing. The first year of the trade war made Canadians even more keen to invest in the U.S., despite the bourbon boycotts. Canadians injected $61 billion in U.S. securities in the first half of 2025. The country’s biggest pension fund, the Canada Pension Plan, had raised its share of all investments in the U.S. from 35% at the start of the decade to 47% in 2025.

After decades of Canadian exports gravitating to the U.S., business is starting to find opportunities elsewhere. Britain is buying more unwrought gold as investors and central banks look for alternatives to the U.S. dollar. The rest of Europe has been buying more Canadian canola, aluminum, and oil. China is also buying more oil from Canada, thanks to the Trans Mountain pipeline expansion that fuelled an all-time high, in October 2025, of oil shipments outside North America. Even faraway Singapore and Indonesia saw a surge in Canadian sales, from oil to coal to potassium chloride.  

Those successes speak to Carney’s pledge to double exports to non-U.S. markets by 2035. To accelerate the early trend, the Carney government is focussed in 2026 on forging closer trade ties with China and India. The federal government also launched consultations on trade talks with several countries, including the United Arab Emirates, Qatar, Saudi Arabia. And the first Carney budget pledged $159 million over three years for trade-financing programs to assist firms trying to enter and grow in new markets. It will need to do a lot more to unglue the infrastructure bottlenecks that have made Canadian ports among the least efficient in the industrialized world. 

To gain leverage in more overseas markets, Canada will need to do more to enhance its relevance to those countries—especially in countries and markets, like China, India and even continental Europe, that have a history of hitting Canada with non-tariff trade measures when a point needs to be made. That won’t be easy. As global power has shifted to Asia and as Europe and the Middle East rearm and realign, Canada’s relative salience has eroded. The risk is not outright exclusion from clubs, but quiet marginalization in the working coalitions that matter most for security, technology, and industrial policy—and ultimately trade. Consider Ottawa’s Indo-Pacific Strategy and its deepening security partnership with the Philippines—politically effective, yet not enough to deliver big trade breakthroughs in a region where Japan, Australia, India, and ASEAN states look first to Washington, Beijing, and each other. In Europe, Canada’s big contributions to helping defend Latvia, and a more assertive defence of the Arctic, is buying credibility. Closer to home, in the Caribbean, commitments to helping restore order in Haiti, while important and appreciated, aren’t transforming Canada’s place in the region. 

Too often, these allies calibrate their engagement with Canada through the lens of Trump-era conditionality on NATO and trade. Ottawa is seen as tightly bound to U.S. markets and security but slow to invest in capabilities, enforcement, and industrial scale. To carve out a more independent and ambitious role in the world, Canada can build on some of the alliances and networks it’s already part of. Take the Arctic Council, a group of regional players and powers that focuses on soft issues like science and environmental protection. Canada can deepen ties with Scandinavians and perhaps one day re-engage with Russia through those non-military efforts, while also building up military capacity in the region with like-minded allies like Sweden. It cuts to the new (and old) ethos of foreign policy being rooted in interests, not values.

A very different approach could be taken to the Francophonie and Commonwealth, if other members are willing to muscle up, especially with money. In Africa, for instance, where France’s image has deteriorated, Canada can work with francophone partners to strengthen non-military defences against a resurgent ISIS in the Sahel. The Commonwealth can play its own pragmatic role, helping build trade bridges from Australia to India to South Africa while the U.S. doubles down on America First. More military commitments will be needed, too, as the U.S. pulls back from volatile regions and countries. Haiti crystallizes the risk. A Kenya-led mission with UN authority and rising pressure from the Organization of American States gives Canada a chance to be the training and standards hub for Caribbean contributors, focusing on ports, fuel logistics, and basic state functions—and perhaps with difficulty for Canadians to look the other way if the U.S. shows up in the dead of night to take out gangs or shut down migrant rings.

One of the biggest plays for Canada in gaining more leverage may be AUKUS—the security alliance of Australia, U.K. and U.S. The trilateral pact has focussed initially on nuclear submarines—not a Canadian strength—and is now widening its aperture to advanced capabilities, including undersea sensing, low-orbit satellites, and cyber defences, all of which are Canadian strengths. Canada can pitch itself as a serious member for the next stage of the alliance, which would build leverage overseas while also maintaining a respectful and relevant partnership with the U.S.

The year ahead will present plenty of opportunities to explore this sort of realpolitik diplomacy, as Canada helps design or join more strategic approaches based on interests more than values, and pragmatism more than principles. This will be a step back from those more idealistic approaches that emerged in that earlier time of Third Options. But as every nation knows, independence has a price.

Download the Report