Language Flag Filename

rbc_language_toggle_menu_flag

Canada’s immigration strategy has lost its edge. Population shocks—including the admission of a decade’s worth of immigration in just three years—policy volatility, a diminished focus on skills and experience, and a lack of real time data and transparency are to blame. The result: public sentiment has turned negative for the first time in more than 20 years.

Without immigration, Canada’s population will be cut in half by the turn of the century. Our population is aging, deaths are outpacing births, and workforce participation is shrinking at a time when international competition for highly skilled working-age talent is growing.

Express Entry is not working as intended. The goal of the flagship system is to select applicants with the highest earning potential, and it has; 30% higher median earnings after three years than those coming through the Provincial Nominee Program (the next biggest economic stream)a. But sub-categories are now undermining the program, allowing lower scorers to leapfrog people ahead in line.

Categories need to be reined in and more closely aligned with regional talent shortages. Canada needs some immigration categories to address talent shortages (e.g., blue-collar workers), which vary by region. But 80 provincial streams and duplicative federal categories add unnecessary complexity to the system.

Temporary pathways prioritized volume over skill, undermining a core two-step advantage. The focus on attracting workers and students to fill low-wage labour gaps and prop up underfunded colleges undermined a strategy that had seen former temporary residents gain an earnings advantage over direct permanent residents for more than two decades.

Canada could restore its advantage in the global competition for talent by:

  • Stabilizing with a population growth target (e.g., 1%)

  • Restoring the points system; going back to basics and removing Express Entry sub-categories

  • Concentrating most categories at the provincial and territorial level to address regional skills shortages

  • Recovering the two-step strategy with highly skilled temporary admissions and Express Entry points for Canadian experience

  • Closing the data gap with near real time and more complete information about outcomes, including exits and earnings.

We’re at a unique moment in Canadian history. The country’s economic ambitions have captured the world’s attention, with global capital and talent increasingly looking here as a place to build and invest. Whether Canada capitalizes on this momentum depends heavily on having the people, skills and ambition to drive it. That means includes a strong, stable immigration strategy, something Canada has relied on through our entire modern history.

This report was developed to help Canada get that strategy back on track, knowing the decade ahead will be unlike any other. Our country is undergoing a demographic shift. Meanwhile, advanced technologies including AI and robotics are changing the way we live and work. And the values and ambitions of our country and its communities continue to evolve.

For RBC, this is much more than a macroeconomic challenge. It cuts to the core of our purpose, in helping clients thrive and communities prosper. Since RBC’s founding, immigrants have played a critical role. Newcomers to Canada were among the group in 1864 who started the Merchants’ Bank of Halifax, which was the bank’s original name. RBC grew with the country, setting up tent branches beside railway construction to serve the people literally building Canada. More recently, we pioneered dedicated Newcomer Centres offering one-on-one advice, low-interest loans for internationally trained physicians, and currently offer our services in 200 languages.

The stakes are high. And now is the time to restore our advantage in the global competition for talent with a smarter strategy.

—John Stackhouse, Senior-Vice President, Office of the CEO, Royal Bank of Canada 

Canada’s immigration strategy needs a reset.

The country added three million migrants, roughly the equivalent of a decade’s worth of immigration, between 2022 and 2024. The historic spike, driven by a surge of lower-skilled temporary resident admissions, overwhelmed infrastructure and services and masked a softening economy; per capita GDP fell for two consecutive years. A subsequent pullback on immigration resulted in Canada’s first population decline in modern history.
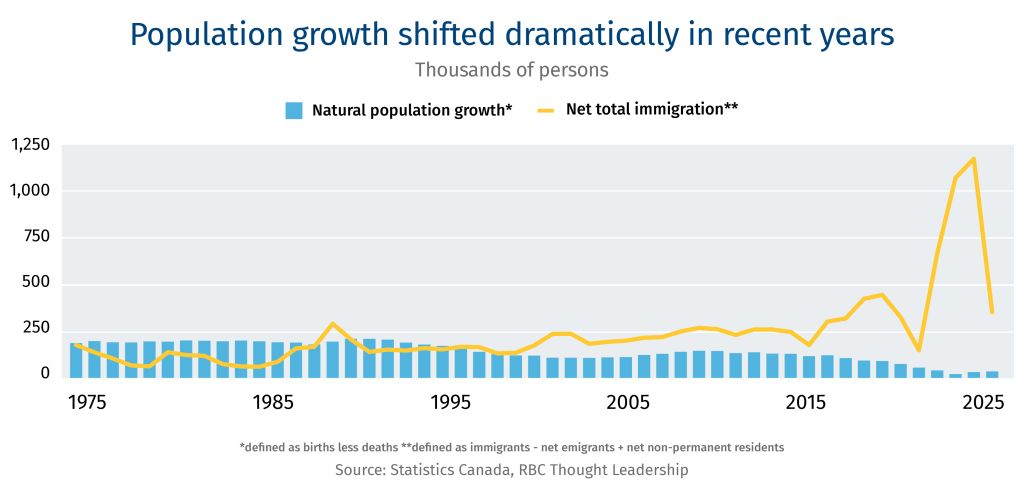
Population growth shifted dramatically in recent years. The country added three million migrants, roughly the equivalent of a decade's worth of immigration, between 2022 and 2024. The historic spike, driven by a surge of lower-skilled temporary resident admissions, overwhelmed infrastructure and services and masked a softening economy; per capita GDP fell for two consecutive years. A subsequent pullback on immigration resulted in Canada’s first population decline in modern history.

These population shocks are emblematic of how Canada’s once renowned immigration system has lost its edge. Policy volatility, a weakened points system, and a diminished focus on skills and experience also share the blame.

This loss of efficacy comes as demographic pressures rise and the global race to attract world-class talent intensifies. Deaths are outpacing births in Canada. Without immigration, the country’s population would shrink to half its size by the turn of the century.
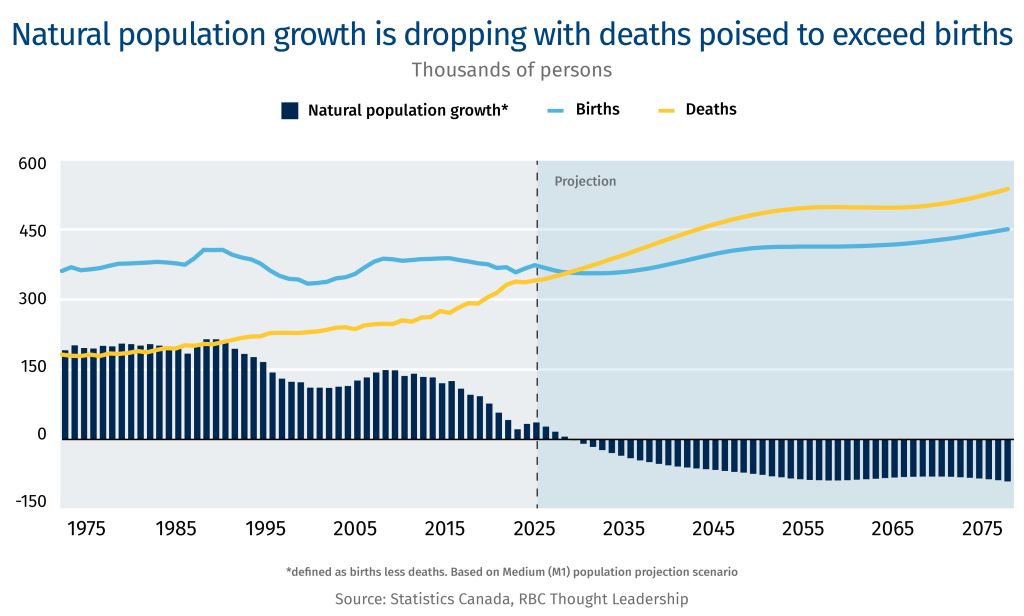
Natural population growth is dropping with deaths poised to exceed births. Without immigration, the country’s population would shrink to half its size by the turn of the century. Plus, more than 25,000 Canadians retire every month; that’s nearly double two decades ago,1 and the elderly to working-age ratio will put intense strain on pensions and healthcare models.
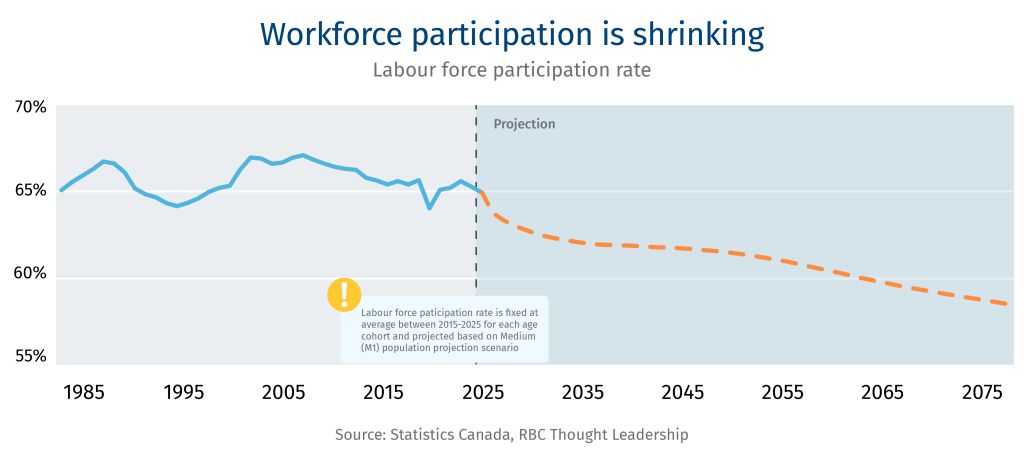
Plus, more than 25,000 Canadians retire every month; that’s nearly double two decades ago,1 and the elderly to working-age ratio will put intense strain on pensions and healthcare models.

Workforce participation is shrinking. Canada is not alone in facing these demographic challenges. The population of those under 25 across the globe has likely peaked, signalling an impending labour force decline worldwide. As these trends continue, competition for highly skilled working-age talent will grow.

Canada is not alone in facing these demographic challenges. The population of those under 25 across the globe has likely peaked,2  signalling an impending labour force decline worldwide. As these trends continue, competition for highly skilled working-age talent will grow.

Despite these pressures, 71% of Canadians think there is too much immigration.3 Polls indicate most of those surveyed are not anti-immigrant but concerned with government management of the immigration file.4 Having a constructive conversation about Canada’s immigration policy could get admissions back on track and avoid slipping into the kind of politically charged, counter-productive discourse taking hold in places like the U.S. and Europe.
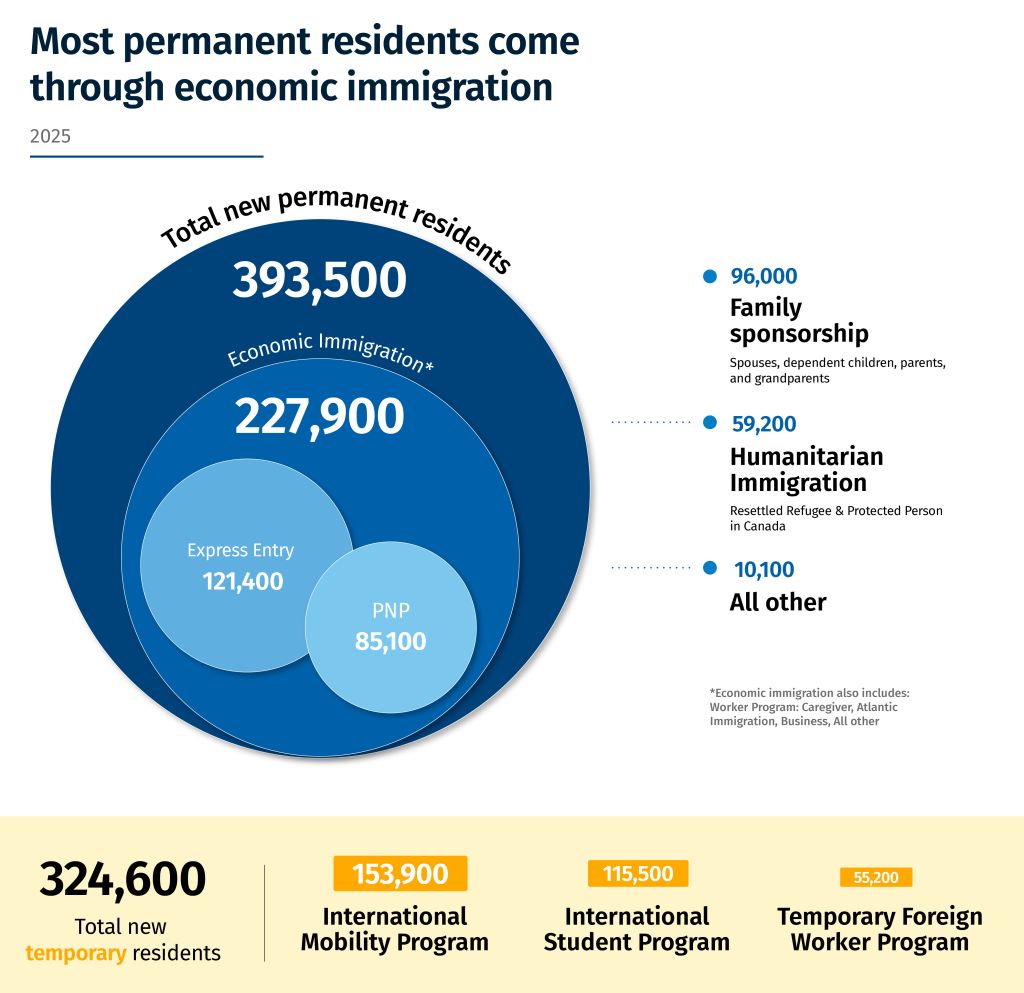
Most permanent residents come through economic immigration. In 2025, there were 393,500 total new permanent residents. 227,900 from Economic Immigration, 121,400 from Express Entry, 85,100 from PNP.

Over the past six months, we consulted more than 60 experts—economists, demographers, pollsters, industry representatives and policy makers—to understand what went wrong with Canada’s economic immigration policy in recent years, and to capture ideas and insights for a better path forward. These interviews and roundtable discussions, along with our own research and data analysis, have surfaced five questions Canadian policymakers must grapple with, urgently and transparently, as part of reimagining a smarter strategic path for immigration.

1. Is there a magic number?

In the decades leading up to the pandemic, Canada’s population growth was relatively steady, averaging 1.1% and ramping up gradually to 1.5% in 2019 (above the 0.6% OECD average at the time, but our population density is lower). This stability allowed Canada to add people without overwhelming infrastructure or services.

Post-pandemic population shocks, by contrast, created strain and uncertainty. Canada added a decade worth of immigration (about three million migrants) in just three years post-lockdown. The rapid population growth, driven by low-skilled temporary migration, overwhelmed infrastructure and services and masked a softening economy; temporary residents grew from less than 3% of the total population leading up to the pandemic to 7.6% in 2024;5 rental prices in major cities like Vancouver and Toronto soared; and per capita GDP fell for two consecutive years.6 In 2023, public sentiment toward immigration turned negative for the first time in 20-plus years.7

Recognizing the need to rebalance, Canada instituted a cap on the temporary resident population (working toward 5% of total population) and added guardrails to prevent abuse of temporary programs by employers and education providers. But these measures generated shockwaves, too. For example, there were more than 25 rule changes affecting international students in roughly two years,8 and more than 20,000 job losses in the postsecondary sector.9 And last year, Canada’s population declined for the first time since the 1950s.

Canadian communities, businesses, and prospective skilled immigrants need more stability and predictability to make realistic plans.

What’s the Levels Plan?

Canada’s Levels Plan is released annually by the Minister of Immigration. It sets out how many permanent and (since 2024) temporary residents the country will admit across different categories in the upcoming year, and notional targets for the following two years. It’s essentially the government’s rolling three-year blueprint for immigration volume and composition.

Key considerations

  • Canada could consider reaching and maintaining a stable population growthb target of about 1%, which has worked well historically, and situates immigration policy decisions in the context of other population dynamics, including fertility and longevity.

    • The target could operate within a control range, allowing for modest (e.g., +/- 0.2%) annual adjustments that account for factors such as shifts in economic and labour market trends, to ensure newcomers are set up for success.

  • The balance of admissions—about 60% economic immigration, 15% humanitarian, and 25% family reunification—has been consistent for the past decade. Canada could consider maintaining this balance moving forward.

  • Policy changes and ministerial instructions could be limited to the immigration Levels Plan each year, along with information such as:

    • The logic and evidence behind the plans (e.g., population projections, employment forecasts, infrastructure capacity)

      Formulas and weighting used for provincial allocations and Express Entry scoring.

  • The growth rate should be matched with policies and investments to meet the expected needs of the corresponding population size. Higher growth requires larger investments in public infrastructure like housing and transportation, services like health care and education, and more private capital to ensure a productive workforce. If Canada opts for a lower growth rate, policies need to account for funding and labour shortfalls associated with an aging population, smaller workforce and taxbase, alongside growing care needs. In that scenario, Canada might consider, for example, a greater role for technology in hospitals and long-term care facilities.
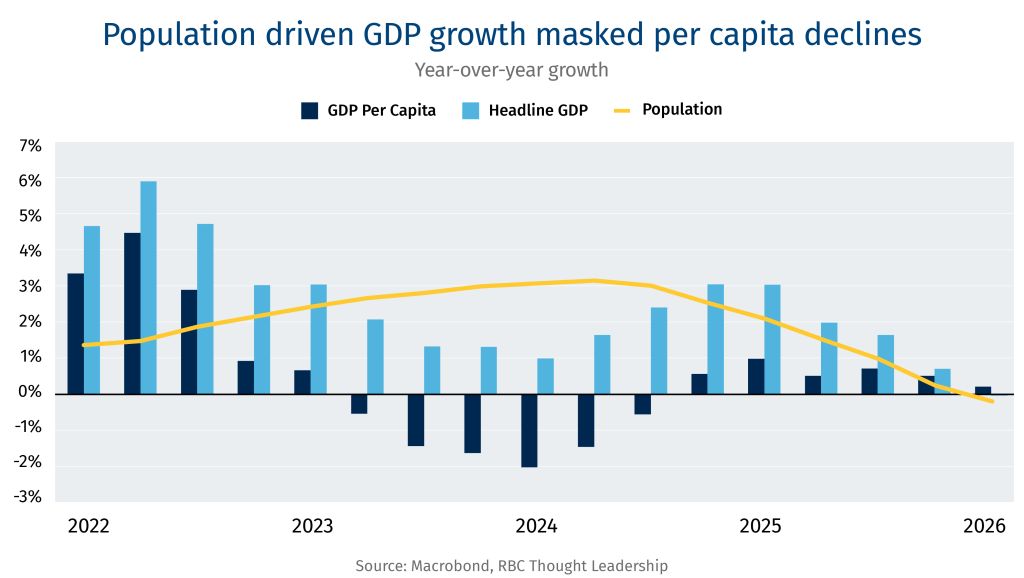
    Population driven GDP growth masked per capita declines. The growth rate should be matched with policies and investments to meet the expected needs of the corresponding population size.

2. How do we select those most likely to succeed?

Canada invented the immigration points system in 1967. Bureaucrats assigned scores across nine categories, including education and training, occupational demand and language ability—a minimum of 50 points out of a possible 100 were required for admission.10 The system helped reduce bias in Canada’s immigration selection and drive both economic growth and our country’s multicultural vibrancy.

What’s the points system?

Canada’s points system is a tool for admitting immigrants based on their earning potential. Since 2015, the points system, or Comprehensive Ranking System, has been run through the Express Entry program. It assigns each applicant a score based on a series of factors, including education, language skills, work experience and age.

The modern version of the points system, the Express Entry program introduced in 2015, uses evidence of who thrived in the past to identify applicants most likely to succeed in the future—and admit them first.

And it does a good job; top scorers tend to see higher earnings. Immigrants coming through the Canadian Experience Class—the Express Entry category with the highest cut off score—have consistently out-earned arrivals from other pathways with median earnings of $92,100 after 10 years compared with $67,400 for economic immigrants, and $47,600 for Canadians overall.11 Even three years out, median incomes for the full group of principal applicants through Express Entry are considerably higher (see chart below).
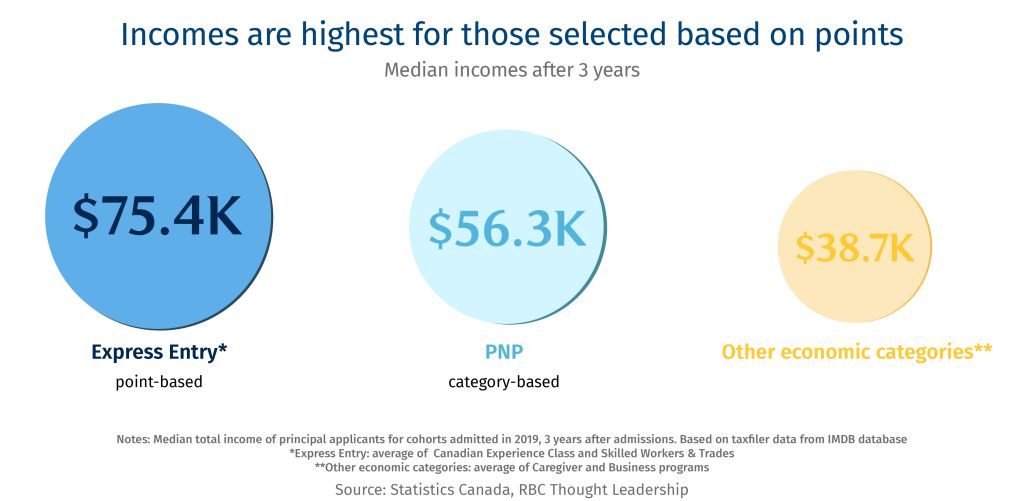
Incomes are highest for those selected based on points. The modern version of the points system, the Express Entry program introduced in 2015, uses evidence of who thrived in the past to identify applicants most likely to succeed in the future—and admit them first.

But a recent policy focus on admitting newcomers through Express Entry categories, tied to a specific occupation, is undermining the program. Legislation introduced in 2022 allows Canada to add Express Entry categories (beyond the original threec) that advance specific priorities. The categories rank a subset of candidates within the pool against others who meet specific criteria.12 Teaching assistants, for example, are scored against others in the educational occupations category—including teachers and early childhood educators—and may leapfrog higher scoring candidates in another category, maybe engineers or nurse practitioners, that are also in line for admission. In effect, competition among people lining up in the Canadian Experience Class category is getting steeper, while new categories create lower bars for entry; admission through the Canadian Experience Class requires over 100 points more, on average, than it does through other categories.

Express Entry categories are undermining the point system. The categories rank a subset of candidates within the pool against others who meet specific criteria.

The list of Express Entry categories has changed multiple times since 2022, illustrating how quickly skill demands change and the futility of designing permanent immigration around them at a national level.

The Express Entry program also lost the original points system’s minimum threshold; cut off scores dropped from the mid-400s pre-pandemic to as low as 75 in 2021 as Canada sought to meet permanent residency targets amid travel restrictions.13 And it has been losing ground: in 2000, almost 80% of economic immigrants were admitted through federally managed point-based selection; lately that percentage is closer to 30%.14

Re-focusing federal admissions on top scorers, rather than trying to predict and meet demands for specific skills or occupations (which vary by region), could restore the Express Entry program to its intended purpose.

Key considerations

  • Canada could consider whether setting a minimum proportion of permanent economic immigration for admission through Express Entry would help boost prosperity and public confidence. Policymakers might also consider re-introducing a minimum cut-off score of core selection factorsd.

  • Express Entry draws should see the highest-ranking candidates admitted. To ensure this happens, Canada could refrain from leveraging the Express Entry program to advance short-term aims by adding sub-categories within it or other federal economic immigration categories alongside it.

    • The federal government has signalled that it plans to streamline Express Entry categories. It could potentially go further by reversing the 2022 legislation allowing additional category-based draws.  

  • Canada could commit to regular reviews to recalibrate and help keep the scoring mechanism current, ensuring the points system reflects changing labour dynamics (for example, reflecting the skills that prove resilient as the impacts of AI plays out in the market).

3. What about Canada’s skills gaps?

One could argue that all of Canada’s economic immigration should come through Express Entry; that admitting highest scorers is the surest way to raise average earnings and living standards. But this would ignore talent shortages in communities across the country.

As the Canadian population ages, the demand for healthcare workers is growing faster than we can train domestic workers. Between 2016 and 2024, the proportion of unfilled jobs in health care nearly tripled,15 and grew five times for licensed practical nurses.16

Skilled trades are also being squeezed. British Columbia, for example, will need to grow its non-residential construction workforce by 10% to complete projects, including the Richmond Hospital Expansion and work at St. Paul’s and Surrey Hospitals.17 The federal government estimates more than 1.4 million new trades workers will be needed by 203318 as a wave of retirements hits. Predicted shortages vary by region: cooks and welders top the list for in Ontario, while Yukon’s greatest future needs include plumbers and construction electricians.19

Category-based selection through pathways like the Provincial Nominee Program (PNP) admit people based on specific skill needs and help distribute immigration across the country. When the PNP was introduced in 1998, 11% of economic immigrants settled outside of Ontario, Quebec, and B.C.; by 2024, that proportion was up to 37%. 

PNP categories distribute immigration benefits across Canada. Category-based selection through pathways like the Provincial Nominee Program (PNP) admit people based on specific skill needs and help distribute immigration across the country. When the PNP was introduced in 1998, 11% of economic immigrants settled outside of Ontario, Quebec, and B.C.; by 2024, that proportion was up to 37%. 

But Canada needs to be careful with the proliferation of categories, which vary significantly across provinces, despite addressing similar needs, and overlap with categories at the federal level. All provinces, for example, have different pathways targeting entrepreneurs, skilled workers, and international graduates of Canadian postsecondary institutions.20 Imagine evaluating this maze of about 80 provincial pathways21 as a prospective immigrant.

Another major challenge with the PNP is retention—certain provinces, and rural regions of most provinces, have a hard time enticing skilled newcomers to stay. Five-year retention rates range from 39% in Prince Edward Island and 61% in New Brunswick to about 94% in Ontario and Alberta for cohorts landing between 2010 and 2015.22

Canada needs some category-based immigration pathways to help address talent shortages that the points system may not prioritize, but federal and provincial goverments need to be strategic about how they are managed.

Key considerations:   

  • Situating immigration categories with provinces and territories, and reducing the number at the federal level, would move targeted admissions closer to regional labour markets and allow the federal government to focus on admitting candidates with the highest projected earnings.

  • Provinces involved with the Provincial Nominee Program (PNP) could coordinate to reduce system complexity, aiming for fewer, more stable categories (potentially with adjustable criteria to allow for nimbleness).

  • Provinces could leverage labour market information to align categories with proven opportunities. They could also aim to select and nominate more provincial applicants from the Express Entry pool, who tend to see earnings about 30% higher than other cohorts after three years.23

  • Retention rates improve when newcomers are employed and see earnings growth.24 Provinces could experiment with different ways of setting newcomers up for successful careers, including, for example, practice-ready assessment pilotse to credential the skills newcomers arrive with.f

  • Provinces could also build stronger evaluation frameworks. Research organizations in B.C., Manitoba, Ontario, and New Brunswickg  have data sharing agreements with the federal government that link immigration records and provincial datasets and provide faster, more detailed insight into who is staying in the province. Other provinces could follow suit.

4. How do we fix the temporary talent pipeline?

Even when immigrants arrive with qualifications Canada needs, it can often take years for their credentials to be recognized and supplemented with local experience needed to succeed in the Canadian labour market. This is what the two-step model Canada has been embracing for more than two decades solves for.

What’s two-step immigration

Two-step immigration refers to the path to permanent residency taken by a growing share of immigrants Canada. It’s a process where individuals first enter Canada as temporary residents—such as foreign workers or international students—and later transition to permanent residency through programs like Express Entry or the Provincial Nominee Program.

With two-step immigration, skilled newcomers arrive with study or work permits, earn recognized credentials, and/or build experience and networks that translate into higher earnings.  Those who came through the two-step Federal Skilled Worker program earned an average of $18,000 more than one-step participants 10 years after arrival;25  and permanent residents who previously studied in Canada earned about 30% more than similarly credentialed arrivals.26 In fact, temporary resident earnings are the strongest predictor of earnings as a permanent resident.27

But these earnings gains, over and above one-step immigrants, are lost when temporary residents arrive with a low level of skill or enter low-quality postsecondary programs.

Canada started to see these gains diminishing before the pandemic as colleges and universities grew international enrolments; many colleges did so with the help of private partners and makeshift satellite campuses, without guardrails to ensure students were entering quality programs.

Then the pandemic hit. Businesses and postsecondary institutions emerging from lockdowns called for more temporary workers and students, and government responded. International student enrolments exploded — then-Immigration Minister likened colleges to “puppy mills”28 — while businesses filled gaps in low-wage work brought about by factors like the so called “CERB effect,” which disincentivized minimum wage workers from returning to their roles.29

Between 2019 (pre-pandemic) and 2023:

  • Study permit approvals increased 102%30

  • Post-graduate work permits increased 154%31

  • Temporary foreign worker permits rose 88%

  • Permits through the international mobility program, an expedited version of the temporary worker program, increased 126%.32

By 2023, the median entry wage for two-step immigrants had fallen to its lowest level since 2017.33

The policy response has since moved in the opposite direction: towards tighter selection and fewer temporary entrants. In 2024, for example, Canada introduced guardrails on the international student program, including Provincial Attestation Letters to allocate capped student spaces across the country. It also tightly restricted new study permits (the approval rate in September 2025 was 38%, down from 58% in 2023 when application volumes were much higher).34

Both pendulum swings—the surge in low-skilled temporary inflows and the tight restrictions on students entering quality programs—undermine the logic of the two-step strategy the country continues to embrace as it transitions record numbers of temporary residents to permanent status.

Key considerations

  • International graduates of high quality, labour market aligned postsecondary programs are good candidates for permanent residency if they wish to stay, and good ambassadors for Canada if they don’t. But that’s not how colleges and universities were incentivized to think about international students. Updating provincial funding models, so that public institutions are not reliant on international tuition to fund domestic seats, could protect the sustainability of a world-class education system and the integrity of the two-step talent pipeline.

  • Once the 5% temporary resident target is met, Canada could evaluate returning to demand-driven international student admissions (perhaps with a pilot at the graduate level, which is already exempt from Provincial Attestation Letter caps) to assess the impact on temporary immigration levels and skills composition. Canada might also pilot a temporary entrepreneurship pathway as a way of attracting investors and job creators with a track record.h

  • Including earnings as a temporary worker and earnings associated with specific post-secondary programs in Canada’s scoring mechanism could improve outcomes, especially if it was transparent to applicants (i.e., if Canada illustrated how postsecondary program selection may affect scores, it could drive applicants to programs with proven labour market success).

5. Why don’t the numbers add up?

The information available to guide Canada’s immigration policy decisions is not as complete or timely as it could be. While Canada has decent sightlines into immigration’s economic impacts through the Longitudinal Immigration Database (IMDB)—which draws on tax filing data—a two-year reporting lag undermines its utility.

New Zealand’s Migrant Employment Data has a reporting lag of only three months, combining immigration data with monthly tax information.35  Canada’s ePayroll project, which aims to standardize and centralize employer payroll submissions, could lend itself to reporting capability comparable to New Zealand’s if it goes ahead.

In the meantime, the Labour Force Survey (LFS) provides faster insights than the IMDB. The LFS generates employment estimates and other labour market information every month, with a lag of only 10 days between collection and release.36 However, the data is less detailed and reliable than the IMDB, and temporary residents are underrepresented. LFS data does not paint a picture of where specific groups of temporary residents, like post-graduate work permit holders, end up.

Until recently, Canada has also lacked adequate compliance data. A 2026 auditor general report found Immigration, Refugees and Citizenship Canada (IRCC) “did not know whether students were leaving Canada after their permits expired;” the Canada Border Services Agency (CBSA) was only able to confirm departures for about 40% of almost 40,000 expired study permit holders.37 In response, the IRCC and CBSA launched a pilot program that tracks exits.

Beyond data gaps, decision-making opacity poses its own challenges for public confidence. The permanent resident target of 380,000 in the 2026-2028 Immigration Levels Plan represented a modest increase from the previous year’s projection but was framed as a contraction—presented alongside 2024 figures and failing to account for one-time initiatives to rebalance the temporary resident population (i.e., transitioning 148,000 to permanent status). This obfuscation only raises public skepticism. Meanwhile, the IRCC publishes the nominations each province receives through the PNP in the Levels Plan each year, but the specific formula and weighting factors used to make allocation decisions remain undisclosed.

Improving timeliness, completeness and transparency around immigration data collection and reporting could help improve immigration policy decisions and public confidence in them.

Key Considerations

  • Advancing the ePayroll Project with input from departments including Statistics Canada could enable faster insights on key metrics. This could be part of a multi-tiered data approach that also includes:

    • Integrating ePayroll data with the IMDB to ensure policy makers also have access to a more detailed longitudinal picture provided by tax and immigration data linkages.

    • Gathering more nuanced data from temporary residents in the LFS questionnaire, and publishing departure estimates by permit type (for example, for post-graduate work permit holders).i

    • Connecting and using data that is already being routinely collected to improve the understanding of immigrant outcomes like mobility. The Longitudinal Immigration Statistical Environment, for example, combines administrative health and education data with information from the Census and IMDB; it has been created on an ad hoc basis, but is not a regular product.

  • Canada could improve transparency and accountability by:

    • Publishing clear Levels Plan targets and the policy rationale behind them, avoiding ambiguity that erodes public confidence;

    • Standardizing provincial PNP reporting (format and frequency) and publishing consolidated national data showing provincial allocations, uptake rates, and the proportion of nominations drawn from Express Entry

    • Separately reporting the share of economic immigrants who are principal applicants, versus spouses and dependents.

The questions in this report are ultimately about navigating difficult tradeoffs.

Canada’s Levels Plan sets targets for permanent and temporary admissions, meaning there are limited spaces available — one person’s admission is effectively another’s refusal.

Admitting highly skilled newcomers can help raise economic wellbeing for the average person living in Canada; admitting newcomers with skills that are less valued in the Canadian labour market can have the opposite effect, creating competition for low-wage jobs, pulling down both average wages and economic prosperity.

In theory, Canada could rely solely on the points system to admit the economic immigrants most likely to secure well-paying jobs (and make bigger contributions to the tax base). Those high scorers, however, might all choose corporate jobs in Toronto, which would do little to address the long wait lists for family physicians in places like Prince Edward Island.

Category-based selection can help Canada address specific, urgent skills shortages. Canada might achieve the best of both worlds–category — and point-based selection — without having one undermine the other, by focusing federal selection on high prospective earners selected through the points system, and situating categories in the provincial and territorial policy domain. Provinces could work in coordination with the professional bodies and training providers they regulate to ensure newcomers are selected and supported to address regional talent shortages in rewarding careers.

Taking two-steps to permanent residency, by first gaining Canadian work or study experience, can improve newcomers’ odds of securing those successful careers. Not all temporary programs should lead to permanent residency, however. Canada could strengthen outcomes and transparency by using earnings metrics to identify which temporary pathways can work as stepping-stones and set clearer expectations about which ones do not. This would require improvements to the speed and completeness of Canada’s data collection and reporting.

Navigating these tradeoffs strategically and transparently — with clear targets and supporting logic outlined in Canada’s Levels Plan — can help restore and maintain public confidence in immigration policymaking. As can stabilizing population growth.

Growing at a steady, predictable rate allows policymakers and businesses to plan for the infrastructure, services, and supports newcomers and their families need—from healthcare and housing to transportation and education — while building public trust that immigration strengthens rather than strains Canada’s communities and economy.

Rebuilding this trust is urgent. Canada’s success in attracting world-class talent depends on restoring our reputation as a stable destination with a welcoming public and predictable pathways for newcomers to thrive. By refocusing policy trade-offs on boosting prosperity across the country with steady, skilled economic immigration, Canada can restore support for a long-term immigration strategy, where humanitarian and family reunification objectives are advanced alongside economic ones.
Download the Report

1 Janzen, N., & Zheng, A. (2026). Canada’s looming labour squeeze: The impact of retirements and immigration https://www.rbc.com/en/economics/canadian-analysis/featured-analysis/insights/canadas-looming-labour-squeeze-the-impact-of-retirements-and-immigration-policy/

2 United Nations Department of Economic and Social Affairs, Population Division. (2024). World Population Prospects: Demographic Profiles. https://population.un.org/wpp/graphs?loc=900&type=Demographic%20Profiles&category=Line%20Charts

3 Environics Institute for Survey Research. (2026). Canadian Perspectives on Multiculturalism and Diversity. https://environicsinstitute.org/wp-content/uploads/2026/06/ENV_BD_Canadian-Perspectives-on-Multiculturalism-and-Diversity.pdf

4 Environics Institute for Survey Research. (2025). Canadian Public Opinion about Immigration and Refugees. https://environicsinstitute.org/wp-content/uploads/2025/11/ENV_FC_Canadian-public-opinion-about-immigration-and-refugees.pdf

5 McGoey, M., & Nicol, C. (2026). Demographic Implications of the 2026–2028 Immigration Levels Plan. Office of the Parliamentary Budget Officer. https://www.pbo-dpb.ca/en/publications/RP-2526-025-S–demographic-implications-2026-2028-immigration-levels-plan–implications-demographiques-plan-niveaux-immigration-2026-2028

6 McCormack, C., & Wang, W. (2024). Canada’s gross domestic product per capita: Perspectives on the return to trend. Statistics Canada. https://www150.statcan.gc.ca/n1/pub/36-28-0001/2024004/article/00001-eng.htm

7 Environics Institute for Survey Research. (2025). Canadian Public Opinion about Immigration and Refugees. https://environicsinstitute.org/wp-content/uploads/2025/11/ENV_FC_Canadian-public-opinion-about-immigration-and-refugees.pdf

8 Atique, A., & Nagari, D. (2025). Broken immigration promises are based on false narratives. The Conversation. https://theconversation.com/broken-immigration-promises-are-based-on-false-narratives-285970

9 Steele, K. (n.d.). CDN PSE dashboards: Jobs impacted.Eduvation. https://circles.eduvation.ca/posts/cdnpse-dashboards-jobs-impacted

10 Canadian Museum of Immigration at Pier 21. (n.d.). Immigration Regulations, Order-in-Council PC 1967-1616, 1967.  https://pier21.ca/research/immigration-history/immigration-regulations-order-in-council-pc-1967-1616-1967

11 Immigration, Refugees and Citizenship Canada. (2026). Immigrant outcomes. https://www.canada.ca/en/immigration-refugees-citizenship/corporate/transparency/transition-binders/deputy-minister-2026/immigrant-outcomes.html

12 Immigration, Refugees and Citizenship Canada. (2025). 2024–25 Report to Parliament on Immigration. https://www.canada.ca/en/immigration-refugees-citizenship/corporate/publications-manuals/report-parliament-cbs-2024-25.html#toc-3

13 Immigration, Refugees and Citizenship Canada. (2022). Express Entry Year-End Report 2021. https://www.canada.ca/en/immigration-refugees-citizenship/corporate/publications-manuals/express-entry-year-end-report-2021.html

14 Statistics Canada. (2024). Chart 1: Share of new economic immigrants by admission program, Canada, 2000 to 2023. https://www150.statcan.gc.ca/n1/daily-quotidien/240327/cg-e001-eng.htm

15 Statistics Canada. (2025). Canada’s health workforce: Regional vacancy trends, 2024. https://www150.statcan.gc.ca/n1/daily-quotidien/251201/dq251201b-eng.htm

16 Masoud, H., Sayle, Z., & Yang, H. (2025). Regional dynamics of vacancies in health-related occupations in Canada, 2024. Statistics Canada

17 BuildForce Canada. (2026). Construction and Maintenance Looking Forward 2026–2035: Non-residential.  https://www.buildforce.ca/wp-content/uploads/2026/07/Construction-Maintenance-Looking-Forward-2026-2035-non-residential.pdf

18 Employment and Social Development Canada. (n.d.). Skilled trades https://www.canada.ca/en/employment-social-development/campaigns/skilled-trades.html

19 Ibid.

20 Picot, G., Hou, F., & Crossman, E. (2024). The Provincial Nominee Program: Provincial differences. Statistics Canada. https://www150.statcan.gc.ca/n1/pub/36-28-0001/2024003/article/00003-eng.htm

21 Picot, G., Hou, F., & Crossman, E. (2023). The Provincial Nominee Program: Its expansion in Canada. Statistics Canada. https://www150.statcan.gc.ca/n1/pub/36-28-0001/2023007/article/00004-eng.htm

22 Picot, G., Crossman, E., & Hou, F. (2023). The Provincial Nominee Program: Retention in province of landing. Statistics Canada.  https://www150.statcan.gc.ca/n1/pub/36-28-0001/2023011/article/00002-eng.htm

23 Stick, M., Hou, F., & Picot, G. (2026). Economic outcomes of provincial nominees: Differences between Express Entry and non-Express Entry. Statistics Canada. https://www150.statcan.gc.ca/n1/pub/36-28-0001/2026002/article/00005-eng.htm

24 Institute For Canadian Citizenship. (2025). Highly skilled immigrants twice as likely to leave Canada. https://forcitizenship.ca/article/highly-skilled-immigrants-twice-as-likely-to-leave-canada/

25 Hou, F., & Picot, G. (2024). Earnings of one-step and two-step economic immigrants: Comparisons from the arrival year. Statistics Canada. https://www150.statcan.gc.ca/n1/pub/36-28-0001/2024001/article/00006-eng.htm

26 Skuterud, M., & Chen, Z. (2018). Comparing Outcomes: The Relative Job-Market Performance of Former International Students. C.D Howe Institute. https://cdhowe.org/wp-content/uploads/2024/12/Final20Commentary_518.pdf

27 Picot, G., & Xu, L. (2020). Which immigration selection factors best predict the earnings of economic principal applicants? Immigration, Refugees and Citizenship Canada https://www.canada.ca/en/immigration-refugees-citizenship/corporate/reports-statistics/research/immigration-selection-factors-predict-earnings-economic-principal-applicants.html#conclusion

28 Miller, M. (2023). [Post on immigration selection / policy]. X. https://x.com/MarcMillerVM/status/1732901766029582407

29 Godbout, L. (2020). CERB: From Emergency to Recovery. Canadian Tax Foundation. https://www.ctf.ca/EN/EN/Newsletters/Perspectives/2020/3/200308.aspx

30 Immigration, Refugees and Citizenship Canada. (2024). International Student Program at a glance. https://www.canada.ca/en/immigration-refugees-citizenship/corporate/transparency/committees/cimm-feb-28-2024/international-student-program-at-a-glance.html

31 Immigration, Refugees and Citizenship Canada. (2024). Question Period Note: Temporary resident admissions.https://search.open.canada.ca/qpnotes/record/cic%2CIRCC-2024-QP-00031

32 Ibid.

33 Statistics Canada. (2025). The median entry wage of new immigrants decreased by 10.6% in 2023 but remained above its pre-COVID-19 pandemic level. https://www150.statcan.gc.ca/n1/daily-quotidien/251208/dq251208a-eng.htm

34 Office of the Auditor General of Canada. (2026). International Student Program Reforms. https://www.canada.ca/en/auditor-general/our-work/audit-reports/auditor-general-report-2026-international-student-program-reforms.html

35 Ministry of Business, Innovation and Employment. (n.d.). Migrant Employment Data. New Zealand Government. https://www.mbie.govt.nz/immigration-and-tourism/immigration/migration-research-and-evaluation/migrant-employment-data

36 Statistics Canada. (2026). Labour Force Survey. https://www23.statcan.gc.ca/imdb/p2SV.pl?Function=getSurvey&SDDS=3701

37 Office of the Auditor General of Canada. (2026). International Student Program Reforms: Controlled growth fell short of improving integrity. https://www.canada.ca/en/auditor-general/media-room/international-student-program-reforms-controlled-growth-fell-short-improving-integrity.html

a Refers to principal applicants admitted in 2019.

b The population growth rate reflects natural population growth (births – deaths) and net migration (including arrivals and departures of permanent and non-permanent residents).

c Canadian Experience Class for those who have gained at least one year of work experience in Canada as a temporary resident; 2. Skilled Worker Program for those with work experience abroad; 3. and the Skilled Trades Program.

d This would exclude points awarded for provincial nomination.

e Foreign credential recognition has long been a challenge in Canada, but an approach called Practiceready Assessment is showing promise as a new model. For example, rather than relying on a paper trail, the Physician Assessment Centre of Excellence in Halifax pressure tests skills and addresses training gaps for internationally trained doctors in a 12-week apprenticeship-style program.

f Population Data BC, Manitoba Centre for Health Policy, Institutes of Clinical Evaluation Sciences in Ontario and DataNB.

g Canada paused the Start-up Visa Program in January 2026, which granted permanent residency based on capital or local incubator support, regardless of whether the business idea proved genuine or successful. Several OECD peer countries use temporary visas to attract business founders and drive innovation.

h Statistics Canada has supplemental  surveys that compliment the core LFS questionnaire. They could be used in the future to test variations of questions to before adapting the LFS questionnaire.
Language Flag Filename

rbc_language_toggle_menu_flag

After talks between Canada and the U.S. collapsed, U.S. President Donald Trump slapped 50% tariffs on more than 500 Canadian goods—amounting to 5% (~US$20 billion) of total exports to the U.S. Canada’s response:  dollar-for-dollar retaliatory tariffs.

Our colleagues in RBC Economics analyzed the impact of the new U.S. tariffs:

  • 5.5% — The average tariff rate on U.S. imports from Canada, up from ~3%, but still below the average U.S. tariff rate on imports from all countries.  

  • 0.4% —Share of Canadian GDP directly exposed to new tariffs. While more than 80% of exports will remain tariff-free under the rules outlined in the Canada-U.S.-Mexico Agreement (CUSMA), the impact on the sectors that have been targeted will be significant.   

Read the entire RBC Economics report here. 

  • B.C., Quebec, and Ontario are facing the brunt of the impact of the latest tariffs, with ~10-15% of their U.S. exports affected by the new levies.  

  • Electrical equipment, plastics and packaging, and furniture and lighting make up the bulk of the affected goods.  

  • The Prairies and Atlantic provinces, which largely export key goods that the U.S. relies on such as energy, potash and grains, are largely spared. 

Many of Canada’s primary agri-food exports, such as grains, oilseeds, major protein and livestock, and processed goods were excluded from the Section 338 list.  

However, several important sectors are impacted: 

  • Dairy: The sector was targeted meaningfully, but unevenly. The schedule applies to dozens of products most aimed at whey, milk/cream concentrates, and several milk-protein ingredient products. The most significant product family affected is whey, of which more than $100 million worth of products were sold to the U.S. in 2025. Of note, yogurt, butter, and cheese are not included in the latest tariffs. 

  • Honey, Sugars, Syrups: Natural honey was targeted, which could have severe impacts for beekeepers. Approximately $30 million worth of honey—more than 50% of its exports—went to the U.S. last year. Other syrup and sugar products such as glucose and glucose syrup ($100 million exported to U.S.) are included, but maple syrup ($540 million), was spared.  

  • Horticulture, Botanicals, Essential Oils: Most bulbs, cut flowers, and other live plants are impacted, along with a comprehensive inclusion of essential oils. These are consequential, as $155 million worth of cut flower and flower buds were exported to the U.S. in 2025, and $52 million of bulbs and tubers. The value of essential oil exports to the U.S. was around $55 million, with 80% of exports going south of the border.   

  • Alcoholic beverages: The tariff schedule contains 63 lines classified as alcoholic beverages and is a substantial, broad sectoral hit. It covers more than $1.2 billion of the major beer, wine, other fermented beverages and distilled spirits families.  

With more than 60% ($60 billion) of Canadian agri-food sector exports reaching the U.S. annually, Americans have come to depend on Canada for food security and affordability. While these tariffs are severe for the sectors impacted, and will drive up prices for U.S. consumers, they do not change the macroeconomic picture for Canadian agriculture. 

On Monday, Trump announced that he will double the tariffs on the Canadian auto industry to 50%, levying the punishing rate on cars, trucks, and parts, in addition to steel. In his post, the president said that Americans don’t need Canada.  

The North American auto industry is highly integrated; parts cross borders across North America up to eight times before a vehicle is assembled. Such tariffs would devastate Canada’s auto industry more than reciprocal tariffs would hurt the U.S. sector—but in absolute terms, the auto sectors on both sides of the border will be damaged by an escalating trade war.  

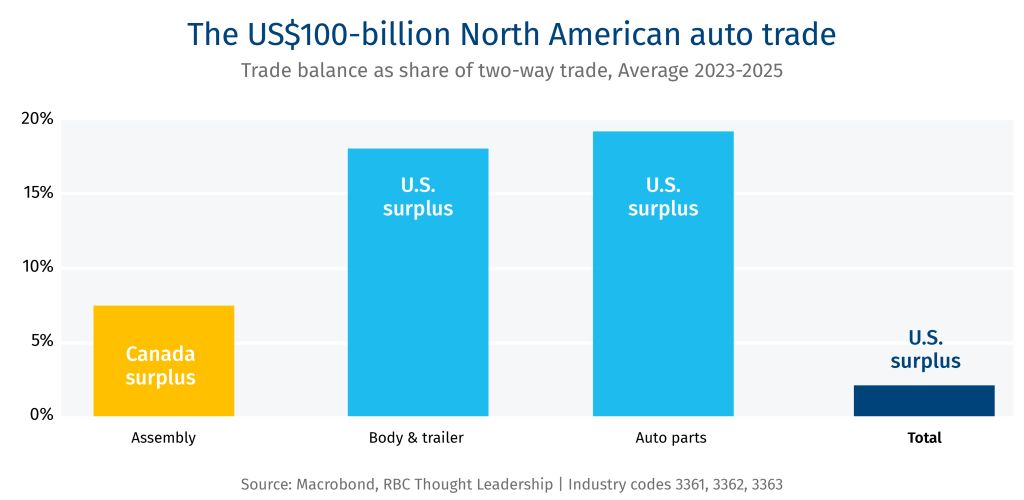
  • The breakdown: Auto trade between Canada and the U.S. is $100 billion (across assembly, parts, and body & trailer). The U.S. runs a $3 billion surplus. Whatever trade is forfeited with Americans, they stand to lose as well.  

  • Production hit in the U.S.: While most of the 10-11 million vehicles that are assembled in the U.S. are sold domestically, about 15% are exported, with Canada serving as the largest export market by far—more than the next 10 export markets combined. Closing the door on American imports would hit a channel equal to 7-10% of annual U.S. production. 

  • Canadians are big car buyers: Only Americans buy more cars than Canadians on a per-capita basis. Canadians spend nearly $110 billion annually on cars, with 90% of those vehicles built abroad. Canadians also have a penchant for heavier, higher-value vehicles. The Ford F-Series have been the best-selling vehicle in Canada for 15 consecutive years.  

  • Tariffs make vehicles more expensive: Auto tariffs on Canada and Mexico alone totalled $1,600 for every vehicle assembled in the U.S.—and that doesn’t account for steel and aluminum tariffs. Tariffs against Canada and Mexico cost North American automakers and suppliers $12.5 billion in the past year. 

  • The U.S. is losing market share: While the Canadian market is small relative to the U.S., it is still the largest global buyer of American-made cars and trucks. In the decade before Trump imposed tariffs on the Canadian auto industry, 49% of vehicles imported to Canada were manufactured in the U.S. In the first 10 months of 2025, that number dropped to 36%, with South Korean and Mexican-made vehicles gaining share. If even higher tariffs come into effect, that trend may continue.  

Language Flag Filename

rbc_language_toggle_menu_flag

As debate continues over the costs of building Alberta’s proposed West Coast Oil Pipeline (WCOP), there is a question of how Canadian heavy crude can compete with the Persian Gulf and ever-rising Venezuelan grades that already serve the Asian market. There are several key elements that need to hold for the economics of the proposed pipeline to work—and none are guaranteed.

A Canadian barrel costs roughly twice what a Gulf barrel costs to land at the same refinery—the arithmetic of being 1,200 kilometres from tidewater. On delivered cost alone, any case for the pipeline must explain what offsets a gap that wide.

A Competitive Oil Market

Heavy sour crude delivered to Northeast Asia (C$/per barrel)

WCSArab HeavyMerey
Delivered costs (C$/b)(CA)(Gulf)(VZ)
Field to tidewater$9-$11$2-$3$4-$6
Freight to NE Asia$4-$6$3-$4$4-$5
Delivered, all-in cost$13-$17$5-$7$8-$11

Notes: Persian Gulf and Venezuelan field-to-tidewater costs are RBC Thought Leadership estimates. Western Canadian Select (WCS) costs are modelled off Trans Mountain’s shipping costs to China from its Westridge Marine Terminal.  Freight rates are mid-cycle estimates.

The new pipeline does not need to follow the same path that unfolded for the Trans Mountain Expansion Project (TMX), i.e., cost overruns that were part passed onto shippers.

Pipeline Economics

West Coast Oil Pipeline (WCOP) vs. Trans Mountain (TMX) financial metrics

WCOPWCOPTMX
Pipeline Metrics (C$)LowHighActual
Capacity, 000 bpd1,0001,000890
Capital cost, $ billion$35.2$43.7$35.3
Capital cost, $ per bpd$35,200$43,700$59,831
Pipeline toll, $/bTBDTBD$9-$11
Freight to Asia, $/b$2-$3$2-$3$4-$6

Notes: The TMX toll reflects the revised rates as disclosed in the July 7 submission to the Canada Energy Regulator ($9.20-$11.05 per barrel). The TMX capital cost per barrel is calculated based on expansion volumes only (590,000 bpd). Freight rates are mid-cycle (normalized). All dollar figures are quoted in Canadian dollars.

The West Coast Oil Pipeline’s transportation costs should hopefully be less expensive than TMX, given the use of a larger line along a ‘de-risked’ corridor, and loading supertankers (Very Large Crude Carriers) directly rather than the mid-sized Aframaxes. The challenge would be to keep the project on budget. The $35-$44 billion estimated price tag for the project excludes escalation and financing—key concerns from a competitiveness standpoint.

Western Canadian Select (WCS) trades well under global benchmarks, much of it due to captivity (as it’s one and only market is the U.S.) rather than quality. While a cheaper price improves competitiveness (buyers get a similar barrel for less cost), it is less than ideal for producers and getting oil to tidewater lets the barrel escape this structural disadvantage. The Alberta government estimates WCOP could narrow the price gap between WCS and the U.S. benchmark West Texas Intermediate by up to US$3 per barrel. For reference, WCS has historically traded at a US$10-15 discount to WTI, but has at times gone in excess of US$20 per barrel.

Buyers are hoping Canadian crude is more reliable. Cheap Persian Gulf barrels carry a Strait of Hormuz risk, while Venezuelan barrels are dependent upon an extended economic reconstruction. Canada’s oil carries neither risk, with Asian buyers willing to pay for that security.

Producer commitments are less a question of Asian demand—TMX’s fill rate suggests the demand is clearly there, but cost overrun concerns need to be alleviated to ensure the West Coast project’s competitiveness.

The trade case rests on several conditions: the project is built on time and on budget, with a discount that is more structural in nature rather than subject to periodic events, and a reliability premium outlast recent disruptions. If these conditions hold, the prize is significant: roughly $20 billion in incremental annual exports (based on 1 million barrels per day at 90% utilization, and a WCS price of $60 per barrel), along with a potential US$3-per-barrel tightening in a spread across future bitumen production of between 4.5 and 5 million barrels per day by 2035, worth about $5 billion annually. Whether Canada should make this bet with public money is a fiscal judgment, particularly given the country’s recent history with pipeline development, but one that seems increasingly likely with each passing day.

–By Shaz Merwat, Energy Policy Lead

RBC brought together more than 500 business, government and policy leaders last month for the U.S.-Canada Summit, in partnership with the Eurasia Group. Ministers, governors, ambassadors, economists, investors—and an astronaut—gathered in one room to talk about the future of the world’s most prosperous relationship.

Donald Trump threatens to cut off trade to Spain

  • The U.S. President issued the threat over the European country’s refusal to increase defence spending to 5% of GDP by 2035. The U.S. administration is now preparing a list of Spanish goods to potentially embargo.

Canada tells the UAE it’s not ready for an inflow of cash

  • The federal government’s Major Projects Office told an official UAE delegation that it was too soon to inject billions of dollars into Canada, as projects are still in early stages. Prime Minister Mark Carney landed a $70 billion investment commitment from the UAE last year, but that capital has yet to be deployed.

Brussels launches probe into imports of Chinese duck

  • The European Commission has launched an anti-dumping investigation targeting Chinese Pekin duck, the breed used to make the iconic Peking duck dish. The latest dispute highlights growing trade tensions between the EU and China.

Global trade and economic groups warn of uncertainty

  • The heads of major global organizations—the International Energy Agency (IEA), International Monetary Fund (IMF), World Bank Group (WBG) and World Trade Organization (WTO)—met to discuss the impact of the war in the Middle East. While they noted that the global economy has been “broadly resilient,” they warned that uncertainty remains high and that the impacts of the war may linger.

U.S. trade deficit widens, as does Canada’s surplus

  • The U.S. trade deficit increased sharply in May, ballooning to a 14-month high despite tariffs on imports. Canada, meanwhile, saw its trade surplus widen to a four-year high in May, with exports of metals and energy increasing during the war in the Middle East.

Language Flag Filename

rbc_language_toggle_menu_flag

U.S. President Donald Trump’s refusal to renew the Canada-United States-Mexico (CUSMA) agreement by the July 1st deadline came as no surprise. But it did usher in a new era for the agreement, one that will include more talks—and even more uncertainty.

What does the no deal by the deadline really mean?

  • For starters, the deal is not dead: The agreement will require annual reviews for the next decade. So little changes in the near term, as tariff carve outs for Canadian and Mexican goods that comply with CUSMA remain in place. If, however, the three parties do not reach an extension agreement by 2036, the deal expires.

  • Will the U.S. withdraw before then? Trump has threatened to do so. But he would need to provide six-months written notice—and, according to the U.S. Senate’s finance committee, requires approval from Congress. As our colleagues in RBC Economics pointed out in their latest report, “We continue to view outright termination of CUSMA as unlikely if economic reasoning holds. Exporters/importers on both sides of the border have a strong incentive to maintain the deal.”

  • What about side deals? The U.S. is expected to push for separate “protocols” with Canada and Mexico. Canada-U.S. Trade Minister Dominic LeBlanc said his government is open to this path.

The roadblocks:

The U.S. has a long list of irritants, outlined in the 2026 National Trade Estimate report released by the U.S. Trade Representative (USTR) earlier this year. That includes a few often-cited issues—Canada’s supply management system; a lack of market access for American wine, beer and spirits; and the federal government’s Buy Canadian policy.

But that’s not all:

  • Improved access to Alberta’s power market: The USTR believes there’s been little progress in improving points of access to Alberta’s energy market for Montana energy producers, and that equally priced power generated in Montana is being deprioritized to benefit Alberta power producers.

  • Aircraft regulatory approvals take too long: The U.S. said stakeholders raised concerns about the regulatory process and timelines associated with aircraft validation in Canada.

  • ‘Cumbersome’ seed regulations: Canada’s system for importing of seeds, claims the USTR, is “slow and cumbersome and disadvantages U.S. seed and grain exports to Canada.”

  • A lack of IP protection: The USTR put Canada on its Watch List for intellectual property protection and enforcement. It also flagged the poor enforcement of counterfeit or pirated goods at the border and within Canada as a concern, referring specifically to the Pacific Mall in Toronto.

What’s next:

  • Negotiations will continue through the summer: The U.S. is meeting with Mexico the week of July 20 for a third round of bilateral negotiations. Mexico may be willing to make concessions, as Claudia Sheinbaum’s government has made the U.S. its top trade priority. Washington and Ottawa have yet to start negotiations.

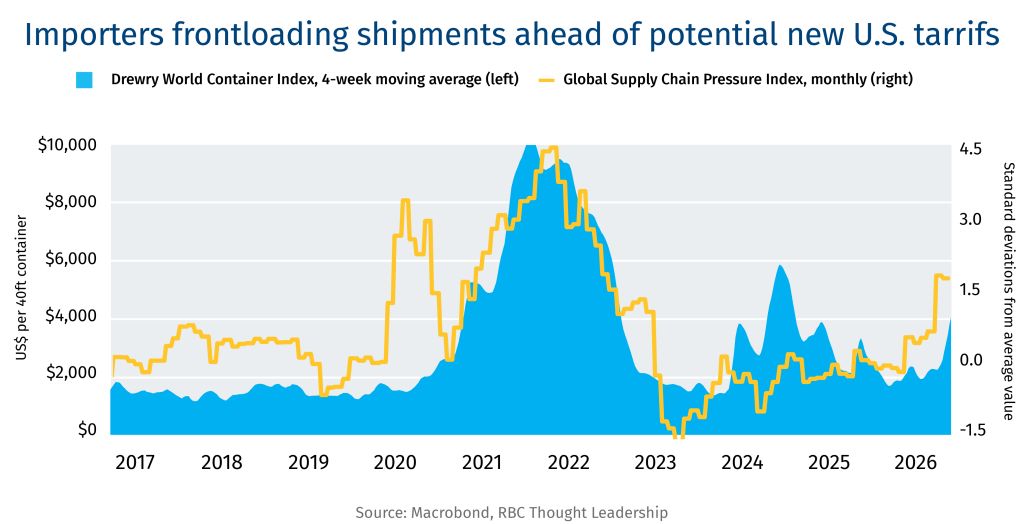
  • Another deadline looms: Section 122 tariffs will expire on July 24 unless Congress extends them, which is unlikely. It’s expected that the Trump administration will instead introduce a new set of tariffs. That’s already spurred an increase in shipping—and shipping rates—as businesses try to get ahead of a fresh batch of tariffs.

    Importers frontloaidng shipments ahead of potential new U.S. tarrifs
  • Investment uncertainty will dominate: Although the agreement is still in place, the annual reviews will prolong the business uncertainty that is already weighing on investment. Without clarity, businesses are likely to hold off on making critical long-term investment decisions. As Mexico’s economic minister Marcelo Ebrard recently said, “if you drag us into a constant review process, you’re going to choke off investment.”

The urgency to feed 10 billion people by 2050 has long been a central concern in agri-food research and policy. But with fertility rates down and global populations beginning to stabilize, a new S&P Global Energy study reframes the long-term question for the ag sector: what if supply outpaces demand?

For certain crop commodities, the rate of demand growth is predicted to slow through 2050, with feed crops especially exposed as growth in per capita meat consumption decelerates toward 0.1% annually.

Meanwhile, crop yields and food production continue to increase. That story rings true for Canada, which has boosted its yields and overall production of most crops considerably since the turn of the millennium. For instance, between 2000 and 2012 annual wheat production did not exceed 30 million tonnes, but had reached nearly 40 million in 2025.

Type of cropAverage annual yield growth (percent), 2000-2025
Canola (rapeseed)3.4
Corn for grain2.1
Wheat, all types3.0
Barley3.3

Source: Statistics Canada. Table 32-10-0359-01  Estimated areas, yield, production, average farm price and total farm value of principal field crops, in metric and imperial units

If such annual yield increases continue from 2026 to 2050 — and seeded acres remain constant —wheat and canola output would grow by tens of million tonnes.

Although an absolute reduction in food consumption is not expected, when slowing population growth contrasts with continued gains in ag outputs, a gap could pose structural challenges for the export market’s long-term health and profitability. Rising demand for biofuels and alternative markets may take some of that surplus, but Canada will need to continue enhancing its efficiency while working to differentiate itself from other major crop exporting countries. Emphasizing the quality of Canada’s exports and its dependability as a trade partner can help preserve its reputation as a preferred supplier.


Contributors: Alicja Siekierska, Farhad Panahov, Wilson Fink

Language Flag Filename

rbc_language_toggle_menu_flag

Also in this edition: 10 numbers that define Brexit’s impact on the U.K. 10 years later 

Expertise, not electrons, could be Canada’s critical energy export 

  • Ottawa’s electricity trade debate keeps circling east-west interties and cross-border electricity flows, but Canadian expertise could be an understated export asset. One such example, called out during Canada’s National Electricity Summit in Ottawa this week, was Manitoba Hydro International (revived in 2024 by the provincial utility following a three-year closure), which started selling Canadian utility expertise to more than 120 clients around the world in 1998. 

Canada needs to remove barriers to trade and to investment 

  • A big takeaway from a C.D. Howe Institute roundtable this week was that while trade diversification is important, lowering barriers to foreign investment is just as urgent. Holistically reforming the country’s corporate income tax system was one of the ideas that was floated.  

Next week, North America will cross a threshold in the Canada-U.S.-Mexico trade relationship.  

It’s not a cliff, but it will start a new chapter in what has been the world’s most successful trade pact. 

To assess what may come next, RBC’s John Stackhouse joined a Brookings Institution virtual roundtable this week, with policy thinkers from all three countries. One thing seemed certain: no matter how a revised CUSMA looks, the spirit of North American trade is likely to bring more elbows and fewer handshakes. 

Some other takeaways: 

1. There will be a deal: “Reason for optimism” was a refrain, although the costs of that deal will be felt in all three countries. So, too, is timing, especially if negotiations continue after the U.S. mid-terms and into a more fractious Washington.  

2. Get used to tariffs: Beyond the July 1 trigger for a CUSMA review, the current regime of Section 122 tariffs will expire on July 24, when we should expect the Trump administration to create another regime. Canadians need to think through a range of tariffs that could follow, from a “heavy hand” option of 15-25% tariffs (unlikely), to a variation of the status quo, which could carry greater border measures on digital trade. A safe bet is some form of “market access” price, perhaps in the 5% range, with plenty of exemptions. 

3. Side letters will be key: The general agreement may stay largely in place, with a host of side agreements that don’t require legislation. That can be good news, as such letters can be changed more easily than a full agreement. But that risk can also apply to safeguards that Canada and Mexico may seek in side deals.  

4. Mexico is willing to make concessions: Claudia Sheinbaum’s government—more overtly than Canada—has made the U.S. its top trade priority, and is adopting policies to align with Washington’s asks. That could include stricter rules of origin for the auto sector. Mexico is also interested in a broader framework, to address border, energy and food security  issues as well as trade. 

5. Canada needs to manage internal divisions: There’s no single Canadian economy when it comes to trade. The current 232 tariffs cover 36-37% of Canadian exports to the U.S.—but 58% for Ontario and 55% for Quebec. The Maritimes, Saskatchewan and Alberta face hits of less than 10%. Canadian opinion has also hardened against a deal at any cost, in part because Canadian trust in U.S. commitments has declined.  

6. Uncertainty is hurting investment and growth: In all three countries, businesses are hedging the borders, diversifying production to get ahead of new tariff and non-tariff measures. For Canada, there also may be some investments taking place to serve non-U.S. export markets, notably Europe and China.  

This week marked the 10-year anniversary of the referendum that resulted in the United Kingdom leaving the European Union. A decade after the seismic vote, the ramifications are still being calculated and realized. 

  • ↓ 14% – The decline in U.K.’s exports of goods to the EU in 2025 compared to 2019, before the two partners signed a new trade deal. During the same period, U.K. exports to non-EU countries were down 8%.   

  • ↑ 28% – The jump in U.K.’s services exports to the EU compared to 2019. Exports to non-EU countries were up 26% from 2019. However, the Centre for European Reform estimates that service exports are still 7% lower than they would have been if the U.K. had stayed in the EU. 

  • ↓  6-8% – The decline in the U.K.’s GDP growth by the end of 2025 due to Brexit, according to a study from the National Bureau of Economic Research.  


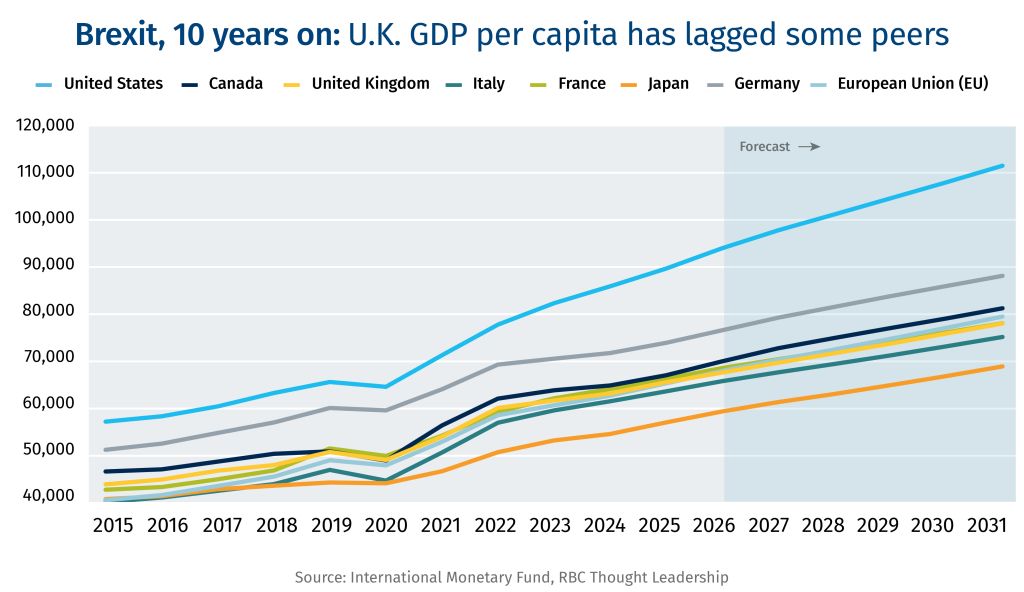
    Brexit, 10 years on: U.K. GDP per capita has lagged some peers

  • ↓  5-10% – The U.K.’s GDP per capita growth was between 5% and 10% less than other similar countries between Brexit and the end of 2025, NBER also estimates.

  • ↓  13% – The decline in the U.K. business investment. Another study suggested U.K. firms invest just 11.1% cent of GDP, with only Canada lower in the G7.

  • 16% – The share of businesses reporting that Brexit was an important source of uncertainty as of Sept. 2025. It was as high as 40% shortly after the U.K. left the EU. 

  • 39 – The number of trade deals Britain has signed covering 72 countries since Brexit. Still, while the U.K.’s trading relationship with the EU fundamentally changed post-Brexit, the bloc remains the U.K’s largest trading partner.  


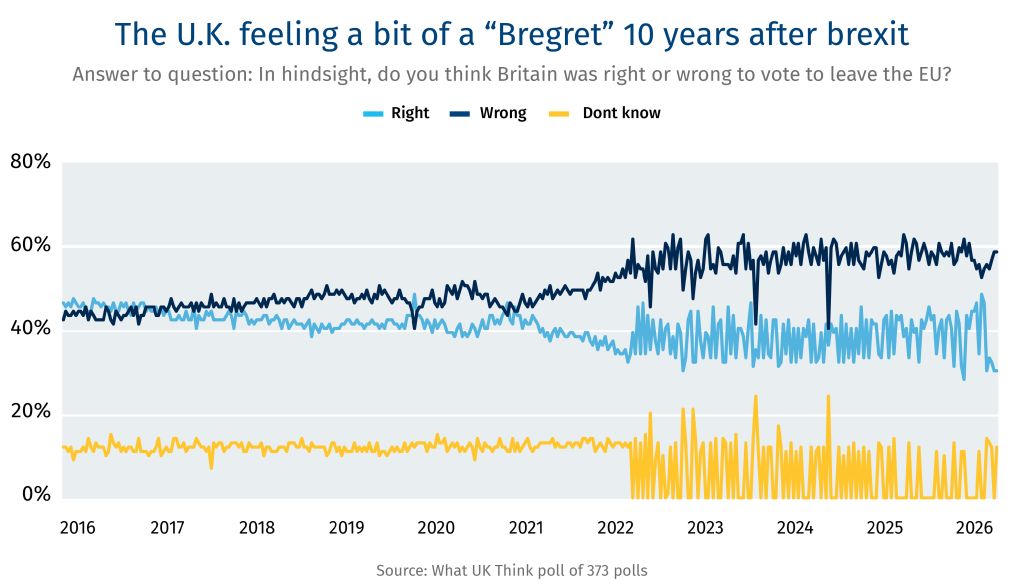
    The U.K. feeling a bit of "Bregret" 10 years after Brexit - chart

  • 57% – Of respondents said Britain was wrong to leave the EU in a recent poll.  

  • 41% – The EU accounted for 41% of the U.K.’s exports, and 50% of the U.K.’s imports.  

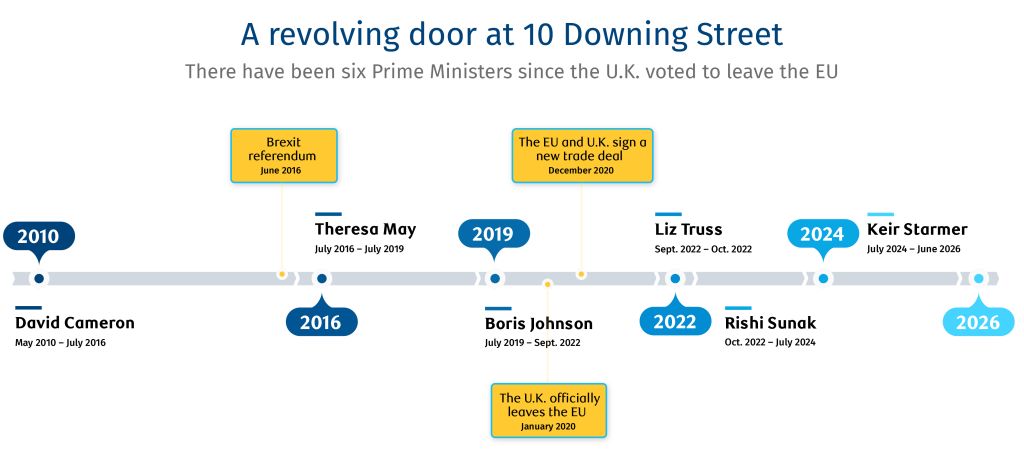
  • 6 – The number of Prime Ministers the U.K. has had since the referendum. Former Greater Manchester major Andy Burnham is expected to become the seventh PM since Brexit. 


    A revolving door at 10 downing street

Language Flag Filename

rbc_language_toggle_menu_flag

U.S.-Mexico trade talks have worsened over security issues  

  • While talks between the U.S. and Mexico appear to be progressing, impasses have surfaced over security concerns, particularly extraterritorial U.S. operations to combat drug cartels.  

Chinese EVs remain a major irritant for the U.S. in trade talks with Canada 

  • It was no mistake that Prime Minister Mark Carney used his moment with President Donald Trump at the G7 Summit to explain the cap on the deal. Behind closed doors, a group of American policymakers remain highly concerned about the entry of China into strategic areas of the North American economy.  

Government continues to align foreign and trade policies 

  • Foreign Minister Anita Anand will take Türkiye’s foreign minister to a nuclear SMR facility in Darlington next week. Another sign that energy is increasingly a pillar of foreign policy.  

How energy markets could shape up post-Hormuz 

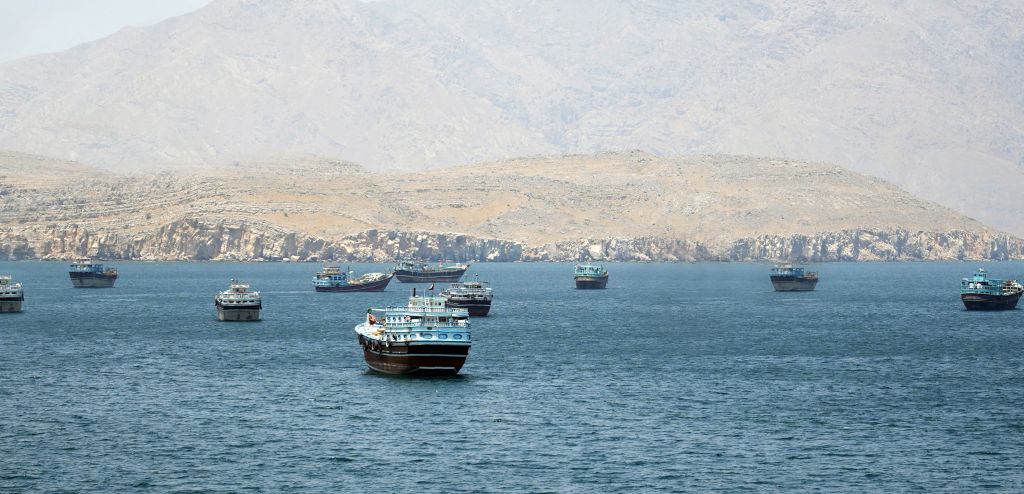
While hostilities between Iran and the U.S. appear to be subsiding, the re-opening of the Strait of Hormuz will continue to shape trade flows in the days, months, and years ahead. 

Why it matters—an MoU is signed, but the Strait isn’t solved 

The Washington-Tehran memorandum of understanding guarantees toll-free passage for 60 days only, followed by negotiations with Oman to define the future administration of the waterway. 

The Red Sea serves as a cautionary tale. In July 2024, a deal was struck with the Houthis, and Bab el-Mandeb Strait traffic—in the Arabian Peninsula—has not returned to early 2024 levels. Reopening of the Hormuz will be a difficult logistical process regardless of when it starts; with more than 500 vessels stranded in the Persian Gulf, mines to clear, and insurers to convince. Peak Hormuz flows may be behind us. “The vase is broken,” said IEA Executive Director Fatih Birol. “Now all actors know that the Strait of Hormuz was closed once and it can be shut down again.” 

By the numbers — resilience, and its limits 

The oil market proved more resilient than most forecasts. Brent peaked at roughly US$126 per barrel—a significant shock, but far below the US$200 worst-case scenarios circulated at the height of the crisis.  

The reason was adaptation, with a parallel logistics system emerging in real time. 

  • U.S. crude exports surged to more than 6 million barrels per day (bpd) 

  • Dark-tanker transits climbed to roughly 3 million bpd by early June, with cargoes shuttled by ship-to-ship transfer in the Gulf of Oman  

  • Alternative Saudi and UAE pipelines absorbed what they could, which was meaningful even though short of pre-crisis Hormuz volumes 

  • Kpler estimates more than 90 million barrels of non-Iranian crude and a further 70 million barrels of Iranian crude are now waiting to leave the region—a significant near-term overhang as the Strait reopens. 

But even resilience has a limit, and it is grade. Asian refiners, built for heavy sour Middle Eastern crude, spent the quarter force-feeding light sweet American barrels as a stopgap. The Hormuz gap was more around heavy oil and LNG shipments. 

The bigger picture—buyers won’t unlearn concentration risk 

Concerns are shifting to a near-term supply glut as trapped Gulf barrels flood the market. The IEA expects a significant crude overhang by 2027 if peace holds. Still, a key learning is that oil markets remain remarkably resilient. When the system was under genuine stress, it adapted through shadow infrastructure, bypass routing, and emergency substitution. Some of this was ad-hoc, but some was planned years, if not decades, ago (such as Chinese strategic reserves, and the Saudi East-West pipeline).  

These themes were discussed at RBC’s Global Energy, Power and Infrastructure Conference in New York this month, where access to global markets was the biggest topic among Canadian producers and importers—with buyers in Asia, and one in Germany cited as anchors for Canadian LNG projects in both the Atlantic and Pacific basins. Importing nations are chasing supply security and portfolio diversification, with a willingness to sew up new contracts running well ahead of the industry’s willingness to sanction new supply. 

Bottom line — a ceasefire changes the headline, not the lesson 

Canada, with one proposed cross-border crude pipeline targeting a mid-2027 final investment decision, TMX volumes already moving west, and West Coast LNG coming online, has meaningful volumes in the near to mid-term. The market will watch the Strait, but the next generation of trade will come from future agreements, which could increasingly include Canada. 

—Shaz Merwat, Energy Policy Lead 

New research out of Purdue University illustrates the benefits to food prices of the trade deal now known as the United States-Canada-Mexico agreement and the costs if its dismantled. The USMCA Affordability Study: The Effect of North American Trade on U.S. Food Prices aims to quantify the effect of North American free trade agreements on U.S. food prices, and outlines a scenario where NAFTA was not implemented and historical tariff rates remained fixed. It concludes: 

  • For every percentage point in reduced tariff rates, there was a cumulative food price reduction of 2.8% over a 10-year period.  

  • Food prices were 12% lower by 2014 than they would have been in the no-NAFTA scenario, saving average households at the time approximately US$500 a year. 

  • Reversing the trade agreements would unwind those gains. And since U.S. agri-food imports from Canada and Mexico have grown significantly since the studied period, American consumers could be hit with much higher grocery bills at a time when budgets are already strained.  

Following the tariff reductions, key U.S. export commodities such as wheat, corn, and beef products did not see a rise in domestic prices that stronger export demand would normally predict. This is suggestive of how interconnected the North American food supply chains have become. 

Food affordability is already weighing heavily on household budgets in Canada and the U.S. New tariffs or trade restrictions emerging out of the upcoming negotiations could undo decades of food supply chain integrations and deepen pressure on consumers. 

—Wilson Fink, Agriculture Policy Lead 

On the hunt for domestic investment, Mélanie Joly was in China this week pressing Chinese automakers to build in Canada, not just sell. Shoring up investment in Canada’s battered auto industry is necessary, but there are multiple crises on the horizon.   

Trapped between two auto giants 

Canada is in a tight squeeze in CUSMA negotiations. Section 232 tariffs aim to make Canadian assembly too expensive, threatening one of Canada’s largest export industries unless removed. Meanwhile, China eyes Canada as its North American beachhead—BYD already secured quota approval, with Chery and Geely racing for their slice of the 49,000-unit imports. 

The dynamics are stark: China wants Canadian consumers, America wants Canadian assembly jobs. Canada’s 125,000-strong auto workforce is caught in the crosshairs. 

But here’s what everyone’s missing in this tug-of-war: while Canada struggles to secure its share of North American assembly, rising vehicle prices are pushing more consumers out of the new vehicle market altogether, compressing demand while the global auto industry is facing over-capacity issues.  

The affordability trap no one’s watching

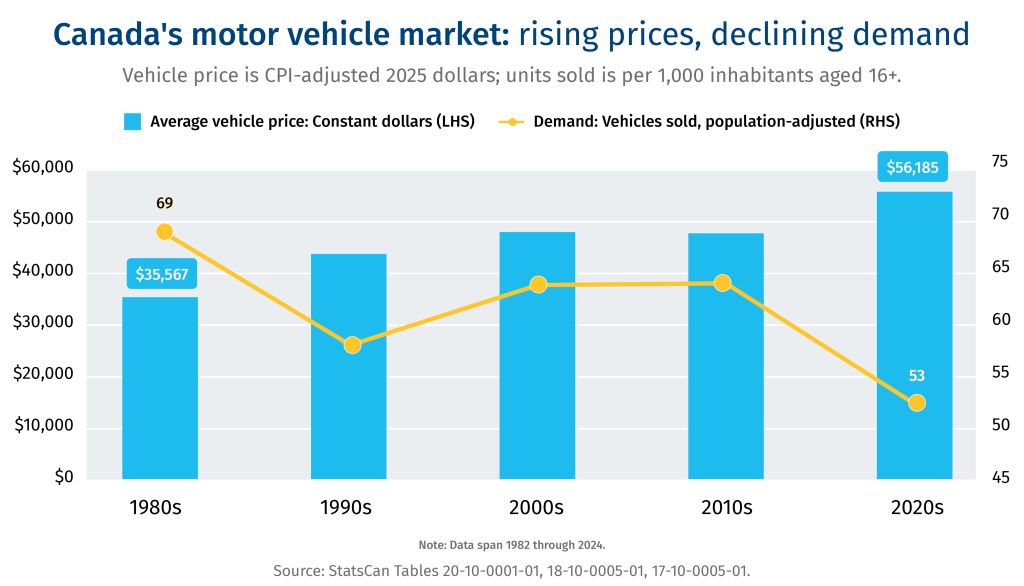
Canada's motor vehicle market: rising prices, declining demand

Vehicle prices have structural headwinds that make tariffs particularly dangerous. SUVs and pickups, which are more expensive than sedans and compact vehicles, already dominate sales. Ever-more tech features also pump up the price tag. When we layer tariffs on vehicles, steel, and aluminum, affordability doesn’t just suffer—it tanks. 

The Canadian numbers illustrate the trend: 1.92 million new vehicles sold in 2024, down 160,000 units from 2017 despite 4.3 million more driving-age residents in Canada. Population-adjusted sales have collapsed more than 20% since the 1980s while average vehicle prices have cruised 60% higher after inflation.  

The pattern repeats stateside—there are 20 million more Americans today than 10 years ago, but vehicle sales fell from 17.4 million units in 2015 to 16.4 million in 2025. As the price of vehicles rise, buyers will be pushed into the resale market.  

Bottom line 

Higher prices don’t just hurt consumers—they kill the very jobs these policies aim to protect. Fewer purchases mean reduced demand, worsening oversupply, and ultimately eliminating assembly positions across North America.  

(For more on North America’s auto industry, read our latest report: Steering Through Uncertainty) 

—Jordan Brennan, Managing Director, RBC Thought Leadership

Language Flag Filename

rbc_language_toggle_menu_flag

More than 500 business, government, policy, and community leaders, along with policy thinkers and academics, came together for the annual U.S.-Canada Summit, hosted by RBC and the Eurasia Group in Toronto on June 11, to discuss where the world’s most prosperous relationship is at—and where it might go.


Here’s some of what emerged:

Tone matters—and this year’s summit carried none of last year’s hostility. Both countries’ ambassadors spoke of hope, although with different expectations, and both sides spoke of tariffs as a new normal, again with different expectations. The fundamentals are too large to ignore: $1.3 trillion in annual two-way trade, 120-million border crossings per year, and a relationship woven through shared IP, talent, capital, and innovation. Trump’s former trade czar Robert Lighthizer acknowledged Canada is not the main problem—America’s real frustration is with China, Germany, and Japan. But Canada isn’t exempt, and he was blunt: tariffs aren’t going anywhere for a generation.

That’s not to suggest there’s rapprochement. Business leaders agreed the damage to Canada-U.S. relations is not irreparable—but there is damage, and it will take time to heal. Trust comes back slowly. Uncertainty recedes slowly, too. But the economic logic of closer Canada-U.S. ties remains strong. One Canadian portfolio manager said that no matter how they run their risk models, they end up with a 50-60% allocation to the U.S. The two governments now have the summer, and likely part of the fall, to find a way forward on trade. They’ll also have to recognize how much their economies are changing at the same time. This isn’t your parents’ trade zone anymore.

As hopes for free trade fade, a new age of state capital is evolving. Both Washington and Ottawa are now explicitly using government spending, tariffs, procurement, and regulation as tools of economic strategy—and the era of assuming that politics would leave globalization alone is over. Daleep Singh of asset manager PGIM put it plainly: we are in a world of fiscal dominance, with industrial policy in the midst of renaissance. Every cross-border linkage—trade, capital, energy, technology—is now at risk of being weaponized for geopolitical leverage. The result is more government debt, higher trend inflation, more political risk and a stronger case for physical assets connected to economic security.

Will this also mean a return to mercantilism? If governments try to gain economic favour by diminishing and constraining others—competitive strength over comparative advantage—Canada will need to play its many cards more assertively: low-carbon natural gas, critical minerals, food and fertilizer, nuclear fuel, and a stable rule-of-law environment that capital increasingly prizes. It presents material opportunities for business, too, as governments create incentives to reshore economic sectors and underwrite the scaling of companies, from AI to life sciences. Annesley Wallace of pension manager HOOPP captured the investor mood: Canada now has the attention of global investors in a way it didn’t a few years ago. But capital wants to see execution and policy certainty, not just ambition.

Data centres are the new factories—the physical infrastructure of the AI economy. And Canada is largely absent from the map. Hamid Moghadam of Prologis, one of the world’s leading logistics companies with $5 billion invested in Canada, was direct: companies building data centres go where it is easiest. Canada is not on that list. Prologis currently has no AI data centre capacity in Canada, with the Netherlands and the United States dominating. The culprit is a “quirky provision” in Canadian tax law that imposes a 15% burden on U.S. tax-exempt capital invested in Canadian properties—a friction that doesn’t apply in reverse. That could be the greatest cross-border risk as enterprise users (unlike the hyperscalers) turn more to inference models that can use low-latency infrastructure. Bell Canada is seizing on that with a new data centre in Regina that is, initially at least, expected to rely on U.S. users.

The slower pace of AI adoption in Canada—fewer than one in five companies, and fewer public sector users have deployed the technology—is starting to show up in economic and business performance. Canada is trying to catch up with a new national AI strategy that aims to invest in AI awareness and skills, as well as business adoption. Jenny Johnson of investment management firm Franklin Templeton put it starkly: the pace of AI is moving so quickly that companies that get it right will leave others in their sector behind permanently. She told her own executives: if you aren’t building agents yourself, you’re already behind. Trouble is, citizens in both countries are increasingly anxious and skeptical about AI. That’s leading to more grassroots pressure, including in this year’s mid-term election campaigns in the U.S., to regulate AI. 

Both Canada and the United States are navigating a crisis of public trust in technology—but they are responding in ways that could put them on a collision course over regulation, data, and digital trade. In the U.S., the AI boom is turbocharged by private capital, hyper-scalers, and a permissive regulatory culture. The concern is less about governance and more about falling behind China in the AI arms race, although local resistance to data centres, especially over their use of electricity and water, could change the conversation. Canada, by contrast, is pursuing a more rights-based, sovereignty-first approach. 

In both countries, and across their borders, the AI revolution is moving so quickly that governments seem destined to react. Ian Bremmer, Eurasia Group’s founder and president, warned of a deepening crisis in which no political leader could overcome a structural gap between technological transformation and outdated governance systems. Technology companies, he said, increasingly act as functional sovereigns in their own domains—and the absence of governance around AI is one of the most urgent risks on the horizon. Canada’s AI Minister Evan Solomon acknowledged the paradox: Canada’s best and biggest AI partner remains the United States, and access to frontier models, compute, and capital still flows primarily north-south. But as Canada builds its own AI sovereignty framework—and as the Safe Social Media Act, new privacy rules, and the AI for All strategy take shape—conflicts over data flows, platform regulation, and digital trade are increasingly likely. 

Defence is again central to the relationship, and central to emerging divisions. One big one: what technologies will dominate the battlefields and defensive lines of tomorrow? Case in point: Three days before the summit, an Iranian drone shot down a U.S. Apache helicopter, and then an American sea drone rescued the two downed airmen. The U.S. is investing heavily in AI systems, robotics and autonomous war machines, as well as bio- and cyber-weaponry. Canada is trying to catch up on advanced military technology, and at the same time restore and restock bigger hardware like fighter jets and submarines. The Canadian strategy is driven by economic policy as much as defence strategy, to build trade ties with European and Asian allies.

The wars in Ukraine and the Middle East have rewritten defence doctrine. Scalable production and resilient supply chains have proven as decisive as firepower. MDA Space CEO Mike Greenley put it this way: defence and space remain areas of full collaboration and full integration, even amid trade tensions. “The stronger we are, the better partner we are.”

That may require an intricate matrix of supply chains and partnerships in which Canada could continue to play a role in the F-35 fighter jet program while also building the GlobalEye partnership between Sweden’s Saab with Bombardier to make surveillance aircraft for Arctic defence. Energy and critical minerals will be a critical component of this new chapter. Vivek Lall of defence firm General Atomics identified a technology triad linking AI, nuclear energy, and autonomy as the defining framework for the next generation of defence capability—and argued Canada-U.S. collaboration has significant potential across all three.

The Arctic is no longer a remote policy afterthought. It has become a global economic, geopolitical, and strategic battleground—and one where Canada and the United States have no choice but to work together, and quickly. Olafur Grimsson, former President of Iceland, framed the challenge: the past decade has seen a flood of new arrivals into the Arctic, as China, Russia, and a constellation of Asian economies sought access. The old notion of sovereignty, where lines on a map settled the question, no longer applies in an environment that is rapidly becoming both economically accessible and strategically contested.

Thomas Dans, Chairman of the U.S. Arctic Research Commission, was direct about Washington’s view: both countries have “a lot of room both to catch up, but also to surpass and to really lead.”

He said North America needs to look over the North Pole and also toward the North Star. First challenge is Russia. Even though there may be room for cooperation over fisheries and shared resources with the Kremlin, Grimsson warned the West risks losing sight of what Moscow is doing in its own Arctic, particularly as Russia deepens energy, pipeline, and mining links with China, India, and other Asian powers. The same sort of resource development is possible on the North American side. Then there’s the skyward trajectory. Continental defence may rest in the ionosphere, but it doesn’t stay up there. The two countries need to develop land and sea-based systems in the Arctic to connect with their growing space-based defence operations.

Canada has always punched above its weight in space—but largely as a junior partner to NASA. That posture is shifting. Canada is now trying to carve out a distinct space identity, rooted in its own strengths and connected to a broader set of international partners, while remaining deeply integrated with the U.S. It may pose the greatest challenge to continental cooperation. Canadian astronaut Jeremy Hansen said the two countries will find the most opportunity by playing to their strengths, rather than for diplomatic reasons. For Canada, those strengths include Earth observation, space-based communications, and robotics, as well as onboard computing.

Countries are increasing spending rapidly, creating a 2.5x economic multiplier for space manufacturing and technology. But leaving the so-called final frontier to commercial firms may underestimate the geopolitical tensions up there. In the race to return to the moon, China is partnering with 11 nations, the U.S. with 60. Canada is in the latter coalition and contributing meaningfully. Hansen compared the challenge to the ethos of a space crew: “People who can point out what’s broken and stop there is not acceptable in our space culture.” Canada’s space ambition requires the same discipline—specific proposals, not just aspirations.

Canada is seeking to diversify its economic and security relationships, without undermining its integral relationship with the U.S. Industry Minister Mélanie Joly said Canada has trade agreements with 52 countries. Discussions with the EU are deepening—not just as a response to tariffs, but to create genuinely integrated Canadian-European companies, and align industrial policies. Michael Sabia, Clerk of the Privy Council, was equally clear: Canada’s U.S. strategy and its broader global strategy are mutually reinforcing. “We are not decoupling. We are diversifying.” On China, his framing echoed U.S. language precisely—de-risking, not decoupling—with clear guardrails defining where Canada can and cannot engage.

But diversification is not free, and the infrastructure required to redirect Canadian trade is largely not built yet. West Coast pipeline capacity remains critically constrained, limiting Canada’s ability to sell oil and gas at premium prices in Asian markets. Port infrastructure in Vancouver and other Pacific gateways—rail connections, bridge capacity, terminal throughput—lags badly behind the ambition of a serious Pacific trade strategy. And permitting timelines for new infrastructure projects remain a systemic bottleneck. Those are solvable problems. Sabia’s closing argument was that Canada holds a genuinely strong hand—low-carbon gas, food, fertilizer, critical minerals, AI capabilities, and a trust premium that flows from values and history. “This is not a time for national anxiety. This is a time for confidence.” 

Download the Report

Language Flag Filename

rbc_language_toggle_menu_flag

Also in this edition: Breaking down six under-the-radar trade themes and a deep dive on four strategically significant industries that could drive U.S.-Canada relationship going forward

With the CUSMA deadline looming and rhetoric heating up (“We don’t need anything Canada has,” President Donald Trump told reporters earlier this week) more than 300 senior business and government leaders from both sides of the border gathered in Toronto for the RBC and Eurasia Group’s US-Canada Summit.

Here are some highlights:

  • Robert Lighthizer, the 18th United States Trade Representative, argued why 50 years of trade deficits left the U.S. no choice but to impose tariffs. And why, despite not being the worst offender, Canada was a target. In a democratic political system, a government doesn’t have years to address an issue, he said. It needs to act quickly. As for where things go with tariffs from here, Lighthizer didn’t mince words: “Nobody here has a grandchild in whose lifetime America is going to be free trade.”

  • Regardless, it’s up to Canada to put on its “sales hat” said Pete Hoekstra. Though the U.S. Ambassador to Canada said potash is about the only thing the U.S. needs from Canada, the U.S. is open to offers. Hoekstra pointed to autos and oil, and even offered some points to help make Canada’s case: the countries have similar pay scales, labour standards, and a thoroughly integrated ecosystem.

  • “America First doesn’t mean America Alone,” said Mark Wiseman, Canada’s Ambassador to the U.S., who added that Canadians are not always good at reminding Americans about the importance of Canada. Remind them of what exactly? For starters: Canada is the largest buyer of U.S. cars, outside the U.S. The No. 1 export market for 30 states. And in the top 3 for almost every state. And Canadians, on per capita basis, buy 40x more American goods than the EU, China and India.

  • Dominic LeBlanc, Minister for Canada-U.S. Trade, noted that the Canadian government has put some proposals forward to the Trump administration—but is also building a Canadian economy that is strong and resilient. Canada is not an “idle spectator.”

  • Wiseman, along with Michael Sabia, the Clerk of the Privy Council and Secretary to the Cabinet, were clear that the government’s diversification efforts do not equate to decoupling from its largest trade partner. It’s ‘and’ not ‘or’. A stronger Canada, they both noted, is a stronger partner for the U.S.

  • Hoekstra didn’t disagree, noting that if Canada is a rich country, maybe a few of those dollars could flow south—maybe to Michigan (“in the summer”), Florida and Arizona. He also joked about Kentucky bourbon, which has been removed by several provinces amid the trade war: “If you need some, I’ll see that you get some.”

After decades of economic co-operation comes a trade shock from the U.S. side. In a report in the runup to the U.S.-Canada Summit, Frances Donald, Senior Vice President and Chief Economist at RBC Economics, notes that the bruised U.S.-Canada ties have uncovered several under-the-radar trade themes. Here are a few worth highlighting:

  • Global trade growth rate doubled without the U.S. Rather than break the global economy, the rest of the world is re-orienting around the U.S. market.

  • The year of Canada’s trade divergence. Higher gold prices helped Canada boost exports to other markets, even as shipments to the U.S. fell 6% in 2025.

  • Canadians have taken economic protection into their own hands. Cutting U.S. travel, boycotting American-made liquor, and seeking out domestic products showed Canadian resolve.

  • Canada added more jobs than the U.S. in 2025. While 68% of Canadian exports are headed for the U.S., only 12% of jobs are dependent on U.S. demand.

Canadian employment rose in 2025 despite trade shock. Annual percent change.

Read Frances Donald’s full briefing here.

It’s the world’s largest bilateral trade relationship—but it’s now under strain. Jordan Brennan, RBC Thought Leadership’s Managing Director, identified four strategically significant industries, which could drive U.S.-Canada relationship going forward.

Auto Manufacturing: Build on the already-integrated nature of the industry by harnessing Canadian clean power, aluminum, and critical minerals with American capital markets, OEM headquarters, and consumer demand.

Critical Minerals: Tie Canadian geology and mining with American financing and manufacturing demand, to deepen supply chain resilience and dependence on China-controlled minerals.

China has a tight grip on minerals, but Canada offers and alternative. The U.S. demand for minerals is projected to grow significantly into 2035.

Oil and Gas: Match Canada’s significant oil and gas resources, pipeline infrastructure, and tidewater access with U.S. refining capacity and capital markets to deliver affordable energy domestically—and to the world.

Defence: Combine American capital depth, technological sophistication, and R&D expenditure, with Canada’s geographic depth and world-class capabilities in sensors, avionics, satellite technology, and training and simulation to surveil and defend the continent.

Read Jordan Brennan’s full briefing here.

Language Flag Filename

rbc_language_toggle_menu_flag

It’s more than a year into the historic U.S.-Canada trade shock, and the two economies suddenly find themselves at another nexus—the future of CUSMA, and a next chapter where precedents don’t necessarily hold. 

In some ways, it’s a moment of relief. What initially seemed like a monumental disruptive trade shock became a watered-down version of threats, and a growing list of exemptions for traded goods for many trading partners. Canada’s list has been the largest, thanks mostly to CUSMA, which makes about 90% of exports to the U.S. tariff-free. As a result, the trade schism between the two countries has been quite narrow, albeit deep.  

But there’s also hesitation. The U.S.-Canada ties seem to be bruised, not broken, but the outcome of the trade negotiations remains far from certain, and adjustments to this new relationship are still in play. Trade-related jobs have still bled on both sides of the border, and Americans are beginning to see the rise in tariff-related inflation. 

The trade war has turned out to be a slow leak—a disruption and transformation in slow motion. Slow leaks buy time to maneuver, but they can also produce some complacency. And they have a way of revealing cracks in the foundation that had been papered over before. This trade shock has uncovered under-the-radar stories about global trade, and the U.S.-Canada trade relationship. Here are six worth highlighting:  

  1. Global trade growth doubled without the U.S. 

    A big Liberation Day concern was that mass tariffs would spark a global recession, given the U.S.’s importance in the world economy. Instead, global trade, excluding the U.S., doubled, growing 4.4% year-over-year.

    A North American centric view of the world would, perhaps, have missed that outside of Mexico and Canada, American trade partners are far less exposed to the U.S. consumer market. Prior to 2025 tariffs, exports to the U.S. ranged from 30% in Vietnam to 15% in China, and 9% for the Euro area.

    Indeed, rather than break the global economy, the rest of the world is adapting to re-orient around the U.S. market. In a world focused on trade leverage, the jump in trade amongst global partners would suggest the U.S., perhaps, has less than initially appears. 

  2. The year of Canada’s trade divergence 

    Canada also re-oriented trade away from the U.S. in 2025—the U.S. share of total Canadian exports went from 76% in the fourth quarter of 2024 to 68% in the same period in 2025. While exports to the U.S. fell 6% year-over-year, or by about $35 billion, this was offset by a hefty $29 billion increase in exports to the rest of the world.

    Diversification didn’t come from finding new buyers for tariffed products. The increase, instead, came thanks to a surge in gold prices, which rose more than 60% in 2025. The result: gold exports to the U.K. alone spiked by $17 billion, or 76%, last year, making gold Canada’s second-largest export after crude oil. This significantly cushioned declines in other goods. 

    Gold also provided a big lift to the Canadian stock market, boosting Canadians’ financial wealth. The gold rally accounted for an estimated third of the TSX’s 28% gain and was the biggest driver behind the index outperforming the S&P 500 last year.  

  3. The U.S.-Canada trade war has been more narrowly impactful 

    Coupled with the energy shock, the trade shock is creating more distinct regionalization across Canada with some provinces and local economies disproportionately bearing the brunt of the breakdown. Though, none have been entirely immune.   

    Thanks to CUSMA, a narrower subset of industries, and therefore geographies, experienced the bulk of the trade shock. While the trade war became a national fixation, it hit manufacturing-heavy provinces of Quebec and Ontario the hardest. Steel, motor vehicles and parts saw the largest export losses, creating particularly acute challenges for regions like southwestern Ontario. Cities like Windsor, Ont., saw unemployment rates rise as high as 11.1%, while the national average peaked at 7.1%.  

    Outside of Ontario and parts of Quebec, the rest of Canada—particularly energy and agricultural-producing provinces—felt minimal direct impacts from the trade war. They benefitted from having very little trade being exposed to U.S. tariffs, and greater overall trade diversification. B.C., for instance, didn’t find itself at the heart of the conversation in 2025, but is likely to feel some pain in 2026 from the knock-on effects of lumber duties, which jumped in October 2025.  

    Coupled with the energy shock, the trade shock is creating broader economic divergence across the country, with several implications worth exploring for policymakers at all levels of government.   

  4. The U.S. trade deficit was redistributed 

    Tariffs were justified by the U.S. administration, in part, as a method to reduce the U.S. trade deficit. One year on, however, the deficit has moved in the wrong direction. Overall, the goods and services deficit widened by US$47 billion in 2025 compared to 2024. The goods trade deficit alone hit a record US$1.26 trillion in 2025.  

    Beneath the surface lies a clear trade policy shift: While the total deficit grew, its mix changed meaningfully. Tariffs successfully reduced imports from primary targets (especially China), while ramping up from other Asian countries, including Vietnam, Taiwan, India, Thailand, and Malaysia. 

    Some other targets, including Mexico, saw exports to the U.S. rise. The U.S. deficit with Mexico grew significantly by US$25 billion despite being subject to 25-35% tariffs at various points in 2025, but with significant exemptions. Some trade goals are a poor match for deeply integrated manufacturing supply chains. 

    Ultimately, the geography shifted substantially, but the aggregate scale of trade did not.  

  5. Canadians have taken economic protection, and damage, into their own hands

    Retaliatory measures were put in place by governments, but Canadians took the trade war personally, particularly with travel. And, it had an impact on Canada, and a key sector in the U.S. 

    Limited retaliatory measures from the Canadian government minimized the impact of the trade war on consumer prices at home, but consumer behaviour, especially in travel, still changed. 

    The federal government’s initial tariff retaliation only covered about a third of U.S. imports before being repealed by September, except those on steel, aluminum, and autos. This kept consumer prices down and gave the Bank of Canada flexibility to further lower interest rates. Meanwhile, provincial governments have exercised product boycotts, notably around American-made liquor, while federal and provincial governments now have “Buy Canada” procurement policies. 

    Still, the country responded in less official, more targeted ways. Travel is the most notable example. Canadian returns from the U.S. shrank 25% year-over-year in 2025.

    Instead, travel to the rest of the world was up 9.2% compared to 2024. And Canadians spent more at home with a 2.7% bump in domestic tourism, raising spending to 11% above its pre-pandemic average. This has been a positive driver for increased domestic consumption. 

  6. Canada added more jobs than the U.S. in 2025 as both sides suffered from the shock 

    Jobs data tells a surprising story. Canada’s Labour Force Survey showed 211,000 jobs were added in 2025, up 1%. Meanwhile, the American Nonfarm Payroll survey showed a 116,000 increase, a 0.07% bump to the employed number. 

    What’s even more interesting is what happened beneath the surface. In the U.S., about 275,000 jobs were lost last year in trade-exposed sectors, including manufacturing, wholesale, retail, transportation and warehousing, and temporary help services. Out of all trade-exposed sectors, transportation and warehousing were hit the hardest with the magnitude of job losses reminiscent of COVID era cuts. Nearly 430,000 jobs were added on net in all other sectors combined.  

    In Canada, jobs dependent on U.S. demand fell by 2%. The silver lining, at least for Canada, is that while the country’s exports (~68%) are heavily dependent on the U.S., only ~12% of jobs are dependent on U.S. demand, helping to stem the bleeding from the trade shock.  

    The bottom line: Workers in both economies have suffered and would benefit from improving trade relations over deterioration.  

Language Flag Filename

rbc_language_toggle_menu_flag

Canada and the United States are bound by the world’s largest bilateral trade relationship—one now under unprecedented strain. In what follows, we focus on four strategically significant industries: critical minerals, energy, automotive, and defence, which sit at the intersection of that relationship. We explore how deepened strategic alignment can enhance North American security, competitiveness, and resilience—and how that could be achieved.

The Challenge: The Canada-U.S. auto trade is under pressure on several fronts

  • U.S. Section 232 tariffs introduced friction at precisely the moment the industry needed continental coordination.

  • The deep structural threat to the US$100-billion Canada-U.S. auto trade is China, which produced 33 million vehicles in 2025—more than a third of the global total. China’s rising dominance is underwritten by scale, superior technology, development speed, and vehicle affordability. 

  • Four other mega forces compound that challenge:

    • Electrification is stalling in North America, even as Chinese-led propulsion electrification is accelerating everywhere else;

    • Vehicles are becoming software-defined platforms, with value increasingly concentrated in chips, sensors, and software rather than mechanical hardware;

    • Industry 4.0 is transforming manufacturing operations and reducing labour demand;

    • Market maturity, as slowing population dynamics and the rise of shared mobility platforms are changing ownership patterns among urban consumers.1

Collective Strengths

  • The U.S. brings the scale, capital, and market demand. American manufacturing expertise, R&D infrastructure, and domestic policy levers shape where investment flows across the North American system.

  • Canada brings complementary assets: award-winning assembly plants, global calibre parts-makers (e.g., Magna, Linamar), and a tech cluster with capabilities in sensors, AI, lightweight materials, and autonomy. BlackBerry QNX software, for instance, is already embedded in more than 250 million vehicles worldwide.2

    The US$100-billion North American auto trade. Trade balance as share of two-way trade, Average 2023-2025.
  • Both countries have strengths in AI and autonomy, but trail China in battery chemistry, primary extraction and refinement of battery elements, and the manufacturing scale that drives efficiency.

  • Canada’s power grid is clean and more competitively priced than comparable auto jurisdictions like Michigan and Ohio. This is becoming more strategically significant as electrification, onboard computing, and autonomous systems raise the power load per vehicle.

  • Canada’s critical minerals are a hedge against dependence on China. The mining and refining of copper, cobalt, lithium, and graphite would strengthen integrated battery, EV, and smart car supply chains. From mine to finished vehicle, the entire value chain can be completed within North America—much of it within a day’s drive to assembly plants.

  • Batteries are expensive and dangerous to transport (owing to their chemical composition), which makes Canada’s rail, Great Lakes shipping, and cross-border trucking a competitive advantage.

The Obstacles

  • Tariff uncertainty is the most immediate obstacle to growth and innovation. For Canada, the threat is existential. More than 90% of Canadian vehicles are shipped to the U.S. Even with a relatively low effective tariff rate, plant margins would be compressed, changing the calculus for investment committees in Detroit and Tokyo.

  • For the U.S., retaliatory tariffs are damaging but not fatal. Canada’s consumer market is large and lucrative—on a per capita basis, Canadians buy more vehicles than any other country. save the U.S. Canada is not only the largest export market for U.S. vehicles—it’s larger than the next 10 countries combined.

  • Relocating assembly within the U.S. would make vehicles more expensive for American consumers. Canadian aluminum is produced using clean, low-cost hydro and nuclear power and is a critical input for lightweighting vehicles. The Ford F-Series is North America’s top selling vehicle and contains some 850 pounds of aluminum. Canada supplies more than half of the total U.S. aluminum consumption. Reshoring production with tariffed aluminum could cost U.S. auto consumers US$1 to US$2 billion.3 Vehicle affordability has already deteriorated on both sides of the border. The average transaction price for a new vehicle now exceeds $50,000 in the U.S. and $60,000 in Canada, putting new vehicles out of reach for many consumers.4 The result is an aging vehicle fleet, as households stretch replacement cycles or exit the market entirely. Tariffs, onshoring mandates, and the cost premium associated with electrification threaten to compound the affordability challenge.

  • The EV retreat is stranding capital without solving the competitiveness problem. Detroit automakers US$53 billion in write-downs reflects a genuine misread of consumer behaviour and policy stability.5 Industry forecasters project North American vehicle production will remain below the 2016 record of 18 million light vehicles through the end of the decade.6 The pivot back to ICE and hybrid platforms buys time, but Chinese OEMs continue to build technological and scale advantages on the platforms—electrified, software-defined—that will dominate the coming decades.

The Path Forward

  • Trade Policy Reforms. Washington’s goal—repatriating manufacturing—reflects a legitimate industrial concern, but the production the U.S. seeks to recover did not migrate to Canada. Since 2000, both Canada (-1.7 million units) and the U.S. (-2.6M units) saw assembly volumes shrink as the continental assembly footprint migrated to Mexico (+2.2M units). Canada, the U.S., and Mexico could align and strengthen the Rules of Origin and reform Most Favoured National tariff policy, which would incent global OEMs to locate production within the bloc, while jointly levying tariffs on EVs, parts, steel and aluminum from outside the bloc—hedging Chinese dumping. Reforms to the Labour Value Content provisions such as raising the content share and the wage rate would help rebalance investment and production within the bloc, which has long been biased toward Mexico.7

  • Critical Minerals Auto Pact. Cooperation on an end-to-end supply chain would tie Canada’s world-class geology and mining expertise with American capital markets industrial demand. In exchange for duty-free access to the U.S. market, Ottawa and the provinces could formalize free trade for steel, aluminum, and copper, and off-take agreements, stockpiling arrangements, and price floors for cobalt, lithium, graphite, and rare earths—commercially de-risking private investment and converting Canada’s processing infrastructure into implicit U.S. supply chain security with no net new capital cost to either government. Extraction and refinement could utilize Canada’s vast capabilities in clean power.

  • Cooperation in Skills and Research. North American OEMs are pivoting toward extended-range electric vehicles (EREVs) and hybrids as the bridge between ICE and full electrification. Co-investment in testing facilities, SR&ED reform to cover autonomy, connectivity, and cybersecurity mandates, and immigration reform to attract engineering and AI talent would deepen the skills density needed to compete with China.

The Potential Outcome: Canada and the U.S. could be better prepared for an electrified, autonomous, and increasingly software-defined auto future by building on a bilateral partnership that ties Canadian aluminum, clean power, critical minerals, and advanced manufacturing capability to American capital markets, OEM headquarters, and consumer demand. Preserving market access for both parties could help keep vehicle prices competitive for consumers while excluding Chinese content from continental supply chains.

The Challenge: China’s Structural Dominance

  • Chinese dominance in the refining and manufacture of critical minerals is the most direct threat to industrial sovereignty in North America. China dominates processing for 19 of the 20 most critical minerals, commanding, on average, 70% of market share. For tech and battery materials like gallium, graphite, and rare earths, its share exceeds 90%.8

  • Questions about the weaponization of supply chain dependence are no longer theoretical. China imposed export controls on gallium, germanium, rare earths, and battery chain technologies during the height of trade tensions with the U.S. In 2025, Ford shut down its Chicago assembly plant for one week following China’s rare earth export restrictions. The U.S. Geological Survey estimates that a 30% supply disruption of gallium could reduce U.S. output by US$600 billion—2% of U.S. GDP.9

Collective Strengths

  • The continental response—who mines, who refines, and who captures the downstream value—will shape North American industrial and defence competitiveness through 2040.

  • Canada and the U.S. are already each other’s largest minerals trading partner—approximately $150 billion in bilateral minerals trade annually.10 Canada is the top source for U.S. critical mineral imports, supplying 20%.11 But the current system is fractured: Canada mines, China refines, and the U.S. manufactures. Closing the gap is the defining industrial policy challenge of the coming decade.

  • Canada has world-class geology across cobalt, copper, gallium, germanium, graphite, lithium, nickel, tungsten and rare earths, with a seven-fold supply potential by 2040.12 Canada also has mature or developing refining infrastructure, including Anglo Teck’s Trail Operation (germanium), Neo Performance Materials’ Rare Earth Metals Facility (gallium), the Sudbury corridor (copper, nickel, cobalt), and the Bécancour mineral processing ecosystem, which connects Quebec’s mines with processing plants and downstream battery manufacturing.

    China has a tight grip on minerals, but Canada offers an alternative. The U.S. demand for minerals is projected to grow significantly into 2035.
  • Canada has clean, affordable power and abundant water. The U.S. has manufacturing scale, dominant capital markets, and the political will to strengthen supply chains.

The Obstacles

  • China has access to nearly unlimited, state-subsidized capital to finance mines and processing plants.

  • The talent and R&D gap with China has widened. China has 39 university degree programs to train engineers and technologists in critical minerals—Canada has none.13

  • For many critical minerals, North American demand is too thin to anchor the market. In 2024, the U.S. accounted for less than 2% of rare earth consumption—far below the threshold needed to make offtake agreements commercially viable.

  • Investment cycles in mining are long. In a world where capital is flowing into short-cycle AI, attracting investment into the refining of low-volume minerals is economically challenging.

  • High labour and environmental standards are strategic advantages in the long run, but they generate permitting timelines that extend well beyond those in China. Processing facilities face additional environmental impact assessments.

  • Supply chains will form around demand, not supply, but most demand will come from renewables and EVs, not defence. Battery chemistry is evolving rapidly, and with it, mineral intensity. Until recently, cobalt was considered essential. Lithium iron phosphate chemistry has since displaced it as the dominant cell technology. Sodium-ion and solid-state could similarly disrupt lithium demand.

  • Canada cannot pursue a strategy across all 34 critical minerals simultaneously. Capital, talent, permitting bandwidth, and infrastructure are finite. A more credible strategy would concentrate investment in minerals where Canada has refining infrastructure already in place and where Canada’s clean power advantage is most decisive. The strategy could also be geared toward minerals with demand that is technology-path-independent and is supported by multiple end uses beyond EV batteries.

  • While states have a role to play in creating and supporting markets, regulatory capture by a few anchor firms is a threat to the public good.

The Path Forward

  • Canada’s supply infrastructure and U.S. demand architecture are symbiotic. A formal Critical Minerals Partnership would tie Canadian geology, clean power, and mining expertise with American capital markets and North American manufacturing demand in a pairing that no other allied combination could match.

  • Long-term demand for critical minerals is expected to be strong. The IEA projects demand growth to 2040 for copper (30%), cobalt (50%), graphite (130%), lithium (350%), nickel (70%), and magnet rare earth elements (65%), driven by renewable energy, EV adoption, grid battery storage, and electricity network expansion. Defence layers on top of these, reinforcing the strategic case to build these supply chains now. Demand aggregation across the U.S., Canada, the European Union, the U.K., Australia, India, Japan and Korea could expand the market beyond 2.5 billion people.14

  • Project Vault works better with Canada. Canada’s federal strategy targets the same six minerals—lithium, graphite, nickel, cobalt, copper, and rare earths—mirroring Project Vault’s key focus areas. Ontario’s $500 million Critical Minerals Processing Fund is building the midstream refining capacity that U.S. OEMs need as a Vault counterparty. Explicit Canadian rules-of-origin eligibility under Vault—so that minerals refined at these facilities qualify as U.S. domestic supply—would convert existing Canadian processing facilities into implicit U.S. industrial capability with no net new capital cost to either government.

  • Allied demand aggregation works better if the U.S.-Canada bilateral partnership is the foundation. The Forum on Resource Geostrategic Engagement (FORGE) could be recast along NATO-like lines, wherein allies commit to procuring refined minerals from other allies as part of their NATO spending targets.15

  • China’s price manipulation is the shared threat that makes bilateral price stabilization essential. Use of a contract-for-difference (CFD), price floors, and volume guarantees could be applied bilaterally to Canadian processors, which would insulate North America’s supply chains against Chinese price manipulation.

  • Sustained investments in R&D, processing chemistry, and engineering talent are needed. Joint investment, shared technical training programs, and co-location of processing and end-use manufacturing could help build the skills density that neither country could develop on its own.16

The Potential Outcome: A North American supply chain could lead to reduced dependence on Chinese refining, tying Canadian geology and mining with American financing and manufacturing demand, deepening supply chain resilience and strategic capabilities simultaneously.

The Challenge: Security, Affordability, and Optionality

  • In 2024, Canada exported $170 billion worth of hydrocarbons to the U.S.—crude oil, natural gas, natural gas liquids, and refined products—accounting for 22% of Canadian exports. Canada supplies more than 60% of U.S. crude oil imports and virtually all natural gas imports. Two-way energy trade sits at $215 billion, underpinned by over 100 transboundary pipelines and transmission lines.17

  • Three imperatives define the relationship:

    • Energy security and sovereignty: Canada’s export dependence on a single buyer exposes both countries to disruption risk—political, logistical, or geopolitical. For oil, future demand growth is in Asia. For natural gas, demand growth is both Asian and North American.

    • Consumer affordability: Energy price volatility, whether caused by conflict in the Persian Gulf, tariff friction, or infrastructure constraints, passes through to households and industry on both sides of the border.

    • Value Maximization: The WCS-WTI price differential—historically US$10-25 per barrel—represents a structural transfer of value from Canadian producers to American refiners, driven by Alberta’s landlocked geography and insufficient export optionality.18

  • The crisis in the Persian Gulf has tightened heavy crude markets, elevated prices, and sharply illustrated the vulnerability of relying on politically unstable supply. The U.S. and Asian allies are assessing alternatives. Canada is the obvious answer.

Collective Strengths

  • Canada is the world’s fourth-largest oil producer, pumping 5.8 million barrels per day. The oilsands are a distinctive asset: long-lived, capital-intensive, and—unlike U.S. shale—resilient to short-cycle price volatility. U.S. crude production is plateauing: the EIA’s long-run reference case projects peak production in 2030, followed by decline in the 2030s. As the shale boom recedes, Canadian imports become more strategically important.19

  • North American heavy crude demand is structural. U.S. Midwest and Gulf Coast refineries are configured to process heavy, sour Canadian bitumen—the same configuration increasingly common in India and China. U.S. refineries with heavy conversion capacity will require a replacement source. Venezuelan production remains constrained by security, risk, and infrastructure. Canada is the only proximate heavy supplier at scale.20

  • The Trans Mountain Expansion (TMX) has begun to transform Canada’s strategic position. Since it came online in 2024, TMX has tripled capacity to 890,000 bpd to tidewater. The WCS-WTI discount narrowed and stabilized from nearly US$30 per barrel in 2022 to approximately US$10 by 2025. Each additional barrel shipped to Asia rather than into the continental market compresses the differential, improving producer netbacks.21

    Canada's customer base for crude expands helping narrow the spread and volatility. Canada's crude oil exports and price.
  • On natural gas, Canada’s Montney formation in northeastern British Columbia is one of the largest natural gas resource plays in the world, and LNG Canada’s Kitimat facility, which shipped its first cargo on in June 2025, has opened Canada’s first large-scale Pacific LNG export route.

The Obstacles

  • Oil prices: low and volatile prices challenge greenfield expansion and pipeline infrastructure; high prices trigger demand destruction and accelerate the energy transition. Sustained greenfield expansion will require policy stability and expanded export infrastructure.

  • Greenfield investment in the oilsands is limited. Growth from existing facilities is achievable but requires a policy environment that fosters growth and does not disadvantage Canada relative to other jurisdictions. A resolution of the Gulf crisis—returning Saudi, Iraqi, and potentially Iranian heavy sour supply to the market—would loosen the premium that currently benefits Canadian barrels in Asia. Venezuelan production, if rehabilitated under a U.S. policy shift, would compete more directly with Canadian heavy than U.S. shale.22

  • On gas, substitution is a constraint that does not apply to oil. Asian buyers can switch from LNG to coal, nuclear, or renewables. LNG Canada’s competitive position in Asia depends on carbon policy coherence, shipping costs relative to Qatari and Australian exporters, and whether Canadian gas can price below coal.

  • The Pathways Alliance—Canada’s five largest oilsands producers—has committed $16.5 billion for carbon capture and sequestration through 2030. The tension between energy security and climate policy has led to policy volatility on emission management, which compounds the technical and financial challenges associated with CCS projects.

The Path Forward

  • Optionality benefits both countries. The strategic logic for oil and gas runs in opposite directions, and both countries’ energy policy could reflect that asymmetry. For Canadian oil, diversification into Asia is the value-maximizing move: every additional barrel shipped via TMX to Asian buyers narrows the WCS-WTI discount and increases netbacks for Canadian producers. Pushing more heavy oil into the continental U.S. market has the opposite effect. For natural gas, the calculus is reversed: AI-driven electricity demand has elevated Henry Hub pricing, making the U.S. a premium gas market. LNG Canada’s Pacific route remains strategically important for Canada’s long-run diversification. The U.S., likewise, could continue to seek optionality for its refineries, securing Canadian supply while finding new import sources.

  • A formal Energy Security Partnership. One with harmonized pipeline permitting and regulatory timelines, joint strategic reserve coordination, bilateral CCS and methane abatement collaboration, and a common framework for infrastructure investment that treats Canadian production as implicit U.S. supply security without requiring government capital from either side. This could be expanded to include the G7 and NATO allies.

  • Oil is a market that works. The continental oil and gas system—hundreds of pipelines, integrated refining, established commercial flows—functions efficiently when policy does not distort it. Tariffs on Canadian energy raise prices for U.S. consumers, widen the WCS discount, and reduce producer revenue without repatriating any production. The U.S. refining system—particularly the heavy conversion capacity—was built for Canadian oil. Disrupting that relationship would require billions in retooling at U.S. refineries or sourcing heavier barrels from less stable suppliers.

  • Gas is complementary, not competing. Henry Hub natural gas prices have spiked with AI-driven electricity consumption in the U.S., making gas sales to the U.S. market economically attractive for Canadian producers. The Montney gas basin and U.S. demand growth reinforce each other. Investment in Montney production infrastructure by U.S. and Canadian investors alike expands the continental gas supply that both countries need for power generation, industrial use, and LNG export.  

The Potential Outcome: A bilateral energy partnership could link Canada’s world-class oil and gas resources, pipeline infrastructure, and Pacific tidewater access with U.S. refining capacity, capital markets, and continental demand to deliver affordable, secure energy to consumers while expanding strategic optionality in global markets for both.

The Challenge: Heightened threat environment, fraying alliances

  • World military expenditure reached US$2.9 trillion in 2025—the ninth consecutive annual increase. The U.S., China and Russia accounted for roughly half of that—unchanged from 2000. However, the relative share changed dramatically: in 2000, Russia and China combined to spend a tenth of U.S. expenditure; today, they spend more than half that of the U.S.23

  • Russia’s invasion of Ukraine broke the security calculus for Europe. NATO responded with a historic commitment: at the 2025 Hague Summit, all 32 allies met the 2% GDP target for the first time since the 2014 Wales pledge. And NATO Allies agreed to a new benchmark of 5% of GDP by 2035.24

  • Russian and Chinese exercises and probes around the Arctic illustrate the rising threat level for North America.25 The Canada–U.S. defence partnership faces four frictions:

    • Defence Expenditure: Canada increased its military spending by nearly 70% from 2022 to 2025—hitting the 2% NATO target for the first time since the 1980s.26 Despite pledging to reach 5% of GDP by 2035, Canada has yet to produce a roadmap Washington finds convincing, prompting the U.S. to suspend the Permanent Joint Board on Defence.27

    • F-35 Procurement: Canada’s review of the program comes amid deepening trade tensions. The U.S. frames the delay not merely as a procurement decision but as a test of whether Canada intends to remain operationally relevant in an era of fifth-generation air and missile defence. The trade tensions also call into question whether Canada will continue to buy the most sophisticated U.S. hardware. 

    • The Golden Dome: Designed to provide continental defence, the Congressional Budget Office has pegged the cost at US$1.2 trillion over 20 years.28 Canada’s role remains undetermined.

      NATO defence spending trails Russia's as a share of GDP. Military expenditure as a share of gross domestic product.

Collective Strengths

  • In addition to unmatched platform scale, capital depth, and technological sophistication, the U.S. possesses a dynamic defence innovation economy, R&D density, and an advanced defence industrial base.

  • Canada brings world-class capabilities in domains critical to modern defence, including avionics, aircraft maintenance repair and overhaul, marine sensors, electronic warfare, UAV’s, and training and simulation—all of which are designated as priority sovereign capabilities in Ottawa’s Defence Industrial Strategy (DIS).29 In space, Canada has a six-decade legacy spanning Earth observation, satellite communications, and positioning-navigation-and-timing systems. Canada contributes heavily to the early-warning capabilities via the northern radar networks and operates a portion of the North Warning System (NWS), and maintains Forward Operating Locations in the Arctic.30 Nearly half of Canadian defence output is exported, with 70% to U.S. and Five Eyes partners, underscoring deep interconnection into global markets.31

The Obstacles

  • Over 90% of Canadian defence firms are SMEs. The absence of large defence primes depresses capital formation, posing challenges to the ambition to scale up Canada’s industrial base. Canada’s venture capital pool—roughly $12 billion—is less than 5% of the U.S. equivalent. Collateral assets in defence (specialized facilities, restricted IP) are often illiquid, with persistent mismatch between up-front investment requirements and revenue timing.32

  • Protectionist procurement policies: Both Canada and the U.S. are pushing to buy domestically, increasing trade frictions. For Canada, directing contracts to domestic firms where industrial capacity does not yet exist at scale could increase costs and extend timelines. Outside of space, ocean, and some aircraft, the target of 70% Canadian content in defence acquisitions by 2035 (up from ~40% today) requires building industrial infrastructure that cannot be created quickly.

  • Arctic sovereignty is another tension. Russia and China pose threats to the Arctic, and despite American pressure to invest in Arctic defence, the region remains exposed (current investments in Arctic defence notwithstanding).

  • The U.S.’s defence industrial base is production-constrained, not merely capital-constrained. The conflict in Ukraine and Iran have exposed munitions stockpile gaps while ‘Buy American’ provisions and export controls have restricted supply chain integration with allies.33

The Path Forward

  • Develop distinct but interoperable industrial bases. Canada has set itself on a clear, distinct path to diversify its defence industry from the U.S. and develop its own sovereign manufacturing capacity. This will create divergent capabilities and more Canadian autonomy. However, it will be important for key capabilities, particularly those important to joint commands, to maintain technological and operational interoperability for the long-term functioning of North America’s defence framework.

  • Deepen in areas of mutual operational necessity. NORAD modernization is foundational. Canada’s ~$40 billion, 20-year investment—over-the-horizon radar (including the $6.5 billion Arctic system being co-developed with Australia), space-based surveillance, command and control, and northern infrastructure—signals deep commitment to the partnership. Canada could negotiate its participation in a future Golden Dome: Canadian sensors, Arctic radar infrastructure, and airspace access are genuine contributions that warrant cost-sharing terms, Canadian IP rights over jointly developed systems, and a defined Canadian role in intercept decision-making.34

  • Explore cooperation on space and drone technology. Recent conflicts demonstrate that uncrewed systems are redefining warfare. At the same time, space is a strategic domain that’s increasingly contested. Ukraine has become the “Silicon Valley” of defence innovation and recent NATO exercises have shown the effectiveness of these capabilities against outdated militaries. This phase of rearmament will not take the same form as previous ones. Canada must update its military equipment and infrastructure writ large, and the U.S. is facing depleted stockpiles and asymmetric threats. Therefore, both must re-prioritize what defence technology they need to develop and procure, creating opportunities for collaboration to avoid duplication in areas of shared security interests.

  • Deepen partnership on critical minerals. Canada’s geology, if twinned with refining capacity, could hedge reliance on adversarial powers. Formalizing supply agreements for NATO’s defence-critical minerals—with off-take arrangements, price stabilization mechanisms, and Rules of Origin eligibility that treat Canadian-refined inputs as U.S. domestic supply—would strengthen both countries’ industrial resilience.

  • Diversify on platforms and partnerships. Canada’s $530 million European Space Agency investment, its participation in the European Union’s SAFE initiative, and its emerging bilateral arrangement with Australia reflects Ottawa’s efforts to diversify its defence industrial base. European partners will expect access to Canadian procurement as the price of access to European markets.

The Potential Outcome: The Canada–U.S. defence relationship has historically rested on an implicit bargain: Canada provides geographic depth, on the ground, under the ocean, on the ocean, in the air and in space; the U.S. provides an umbrella of security and protection, reinforced by unmatched platform scale, capital depth, technological sophistication, and R&D expenditure. Ensuring that bargain holds requires Canada to close the gap between financial commitment and operational credibility—delivering on NORAD modernization, resolving the F-35 decision , and building a genuinely capable domestic industrial base. For the U.S., a more reliable long-term partner will be secured by respecting Canadian sovereignty.

Acknowledgments

The authors would like to thank the external experts consulted for this report, some of whom are listed below.

Peter Dawe, BDC

Steve Carlisle, General Motors (Retired)

Robert Johnston, University of Calgary

Frank McKenna, TD Securities and former Canadian Ambassador to the United States

Michael Robinet, S&P Global Mobility

[1] Brennan, J. 2026. Steering Through Uncertainty: Four Future Paths for Canada’s Auto Industry. Toronto: RBC Thought Leadership.

[2] Brennan (2026), Steering Through Uncertainty.

[3] Canada exports ~US$11 billion in aluminum to the U.S., with more than one-third demanded by the transportation sector. At tariff rate at 50%, the impact on auto assembly alone could exceed $1 billion. When auto parts are layered in, the tariff cost moves higher. For economic analysis of tariffed Canadian aluminium, see Aluminum Association. 2025. Powering Up American Aluminum: A Roadmap for Next Generation Supply Chain Resilience. Arlington, VA: The Aluminum Association; Business Data Lab. 2025. How to Undermine U.S. Manufacturing: Debunking Aluminum Tariff Myths. Ottawa: Business Data Lab.; and Livingston, Brian. 2025. Canada’s Aluminum Production and US Tariffs. Intelligence Memos. Toronto: C.D. Howe Institute. September 2.

[4] Brennan (2006). Steering Through Uncertainty.

[5] Markman, J. 2026. ‘How Legacy Automakers Torched $53 Billion on EVs They’ll Never Sell’, Forbes, February 9.

[6] Robinet, M. 2026. New Automotive Geo-economics. S&P Global Mobility. Presented at PMA, May 2026.

[7] See Helper, S. and T. Tucker. 2026. ‘Challenges and Opportunities for the North American Auto Industry in the 2026 USMCA Renegotiation’, March 4. Washington: Brookings Institution; U.S. International Trade Commission. 2025. USMCA Automotive Rules of Origin: Economic Impact and Operation, 2025 Report. Publication no. 5642. Washington: USITC.

[8] IEA. 2025. Global Critical Minerals Outlook. Paris: International Energy Agency.

[9] Baskaran includes this claim in her testimony to the House Natural Resources Subcommittee—a claim we have not been able to independently verify. See: Baskaran, G. 2026. ‘Unleashing America’s Mineral Potential: The Critical Minerals Commodity Supply Chain’, Testimony before the House of Natural Resources Subcommittee on Oversight and Investigations. Washington: Centre for Strategic & International Studies.   

[10] Natural Resources Canada. 2025. Canada-U.S. Minerals Data Dashboard.

[11] Baskaran, G. 2025. ‘Canadian Tariffs Will Undermine U.S. Minerals Security’, Center for Strategic & International Studies, January 29.

[12] Merwat, S. 2026. Mine & Refine: Bridging Canada’s Critical Minerals Capital Gap. Toronto: RBC Thought Leadership.

[13] Merwat, S. 2025. The New Great Game: How the face for critical minerals is shaping tech supremacy. Toronto: RBC Thought Leadership.

[14] See Baskaran (2026).

[15] See Baskaran (2026) for a suite of policy recommendations which integrate extraction, processing, refining, and manufacturing with demand anchors.

[16] Merwat, S. 2026. Critical Minerals Processing: The West’s refining challenge and the technologies closing the gap. Toronto: RBC Thought Leadership.

[17] Canada Energy Regulator. 2025. Market Snapshot: Overview of 2024 Canada-US Energy Trade. Available online at: https://www.cer-rec.gc.ca/en/data-analysis/energy-markets/market-snapshots/2025/market-snapshot-overview-of-2024-canada-us-energy-trade.html. 

[18] Part of the differential reflects quality and transportation cost, but another part is derived from insufficient export diversification. See Alberta Energy Regulator. 2025. Alberta Energy Outlook ST98. Calgary: Government of Alberta.

[19] Energy Information Administration. 2026. Annual Energy Outlook. Washington: U.S. Department of Energy.

[20] Merwat, S. 2026. Six charts that analyze Canadian-U.S. oil ties amid new geopolitical developments in oil markets. Toronto: RBC Thought Leadership.

[21] Johnston, R. 2026. ‘Asia’s Oil Demand Outlook and Geopolitics’, Presented to PwC Canada/School of Public Policy Asia Oil Outlook, May 7.

[22] See the Oil Sands Alliance’s explainer on the Pathways Project: https://oilsandsalliance.ca/pathways-project/.

[23] Author’s calculations based on data from SIPRI Military Expenditures Database (constant 2024 $USD). 

[24] NATO. 2025. Defence Expenditures and NATO’s 5% Commitment. Brussels: North Atlantic Treaty Organization. Available at: https://www.nato.int/en/what-we-do/introduction-to-nato/defence-expenditures-and-natos-5-commitment.

[25] Bingen, K.A. 2026. ‘Orbits of Influence: Emerging Threats to U.S. Space Security and Foreign Policy Implications’. Statement before the House Foreign Affairs Subcommittee on Europe. Washington: Center for Strategic and International Studies, April 29.

[26] NATO data indicates that Canadian defence spending rose from US$26 billion in 2022 to US$44 billion in 2025—an increase of 69% (using current prices and exchange rates). SIRPI data indicates that Canada spent 2.06% of GDP on defence in 1987. 

[27] Some interpret the suspension of the PJBD as a response to Canada’s decision to review the F-35 program (and not as a response to Canada’s planned military expenditures, despite advertisements to the contrary).

[28] May 2026 report from the Congressional Budget Office: https://www.cbo.gov/system/files/2026-05/62379-golden-dome.pdf.

[29] Department of National Defence. 2026. Canada’s Defence Industrial Strategy: Security, Sovereignty and Prosperity. Ottawa: Government of Canada.

[30] See NORAD Backgrounder: https://www.canada.ca/en/department-national-defence/news/2022/06/north-american-aerospace-defense-command-norad.html

[31] See Canada’s (2026) Defence Industrial Strategy.

[32] Ashcroft, T. 2026. Frontline Investments: How to Advance Defence Finance in Canada. Toronto: RBC Thought Leadership.

[33] See reporting from the Associated Press, ‘US Will Need Years to Replenish Stockpiles of Advanced Weapons Used in Iran War, New Analysis Finds’, May 27. Available online at: https://www.usnews.com/news/business/articles/2026-05-27/us-will-need-years-to-replenish-stockpiles-of-advanced-weapons-used-in-iran-war-new-analysis-finds

[34] Department of National Defence. 2025. Fact Sheet: Funding for Continental Defence and NORAD Modernization. Ottawa: Government of Canada. Available at: https://www.canada.ca/en/department-national-defence/services/operations/allies-partners/norad/facesheet-funding-norad-modernization.html.