

 EN


For week of Sept. 21
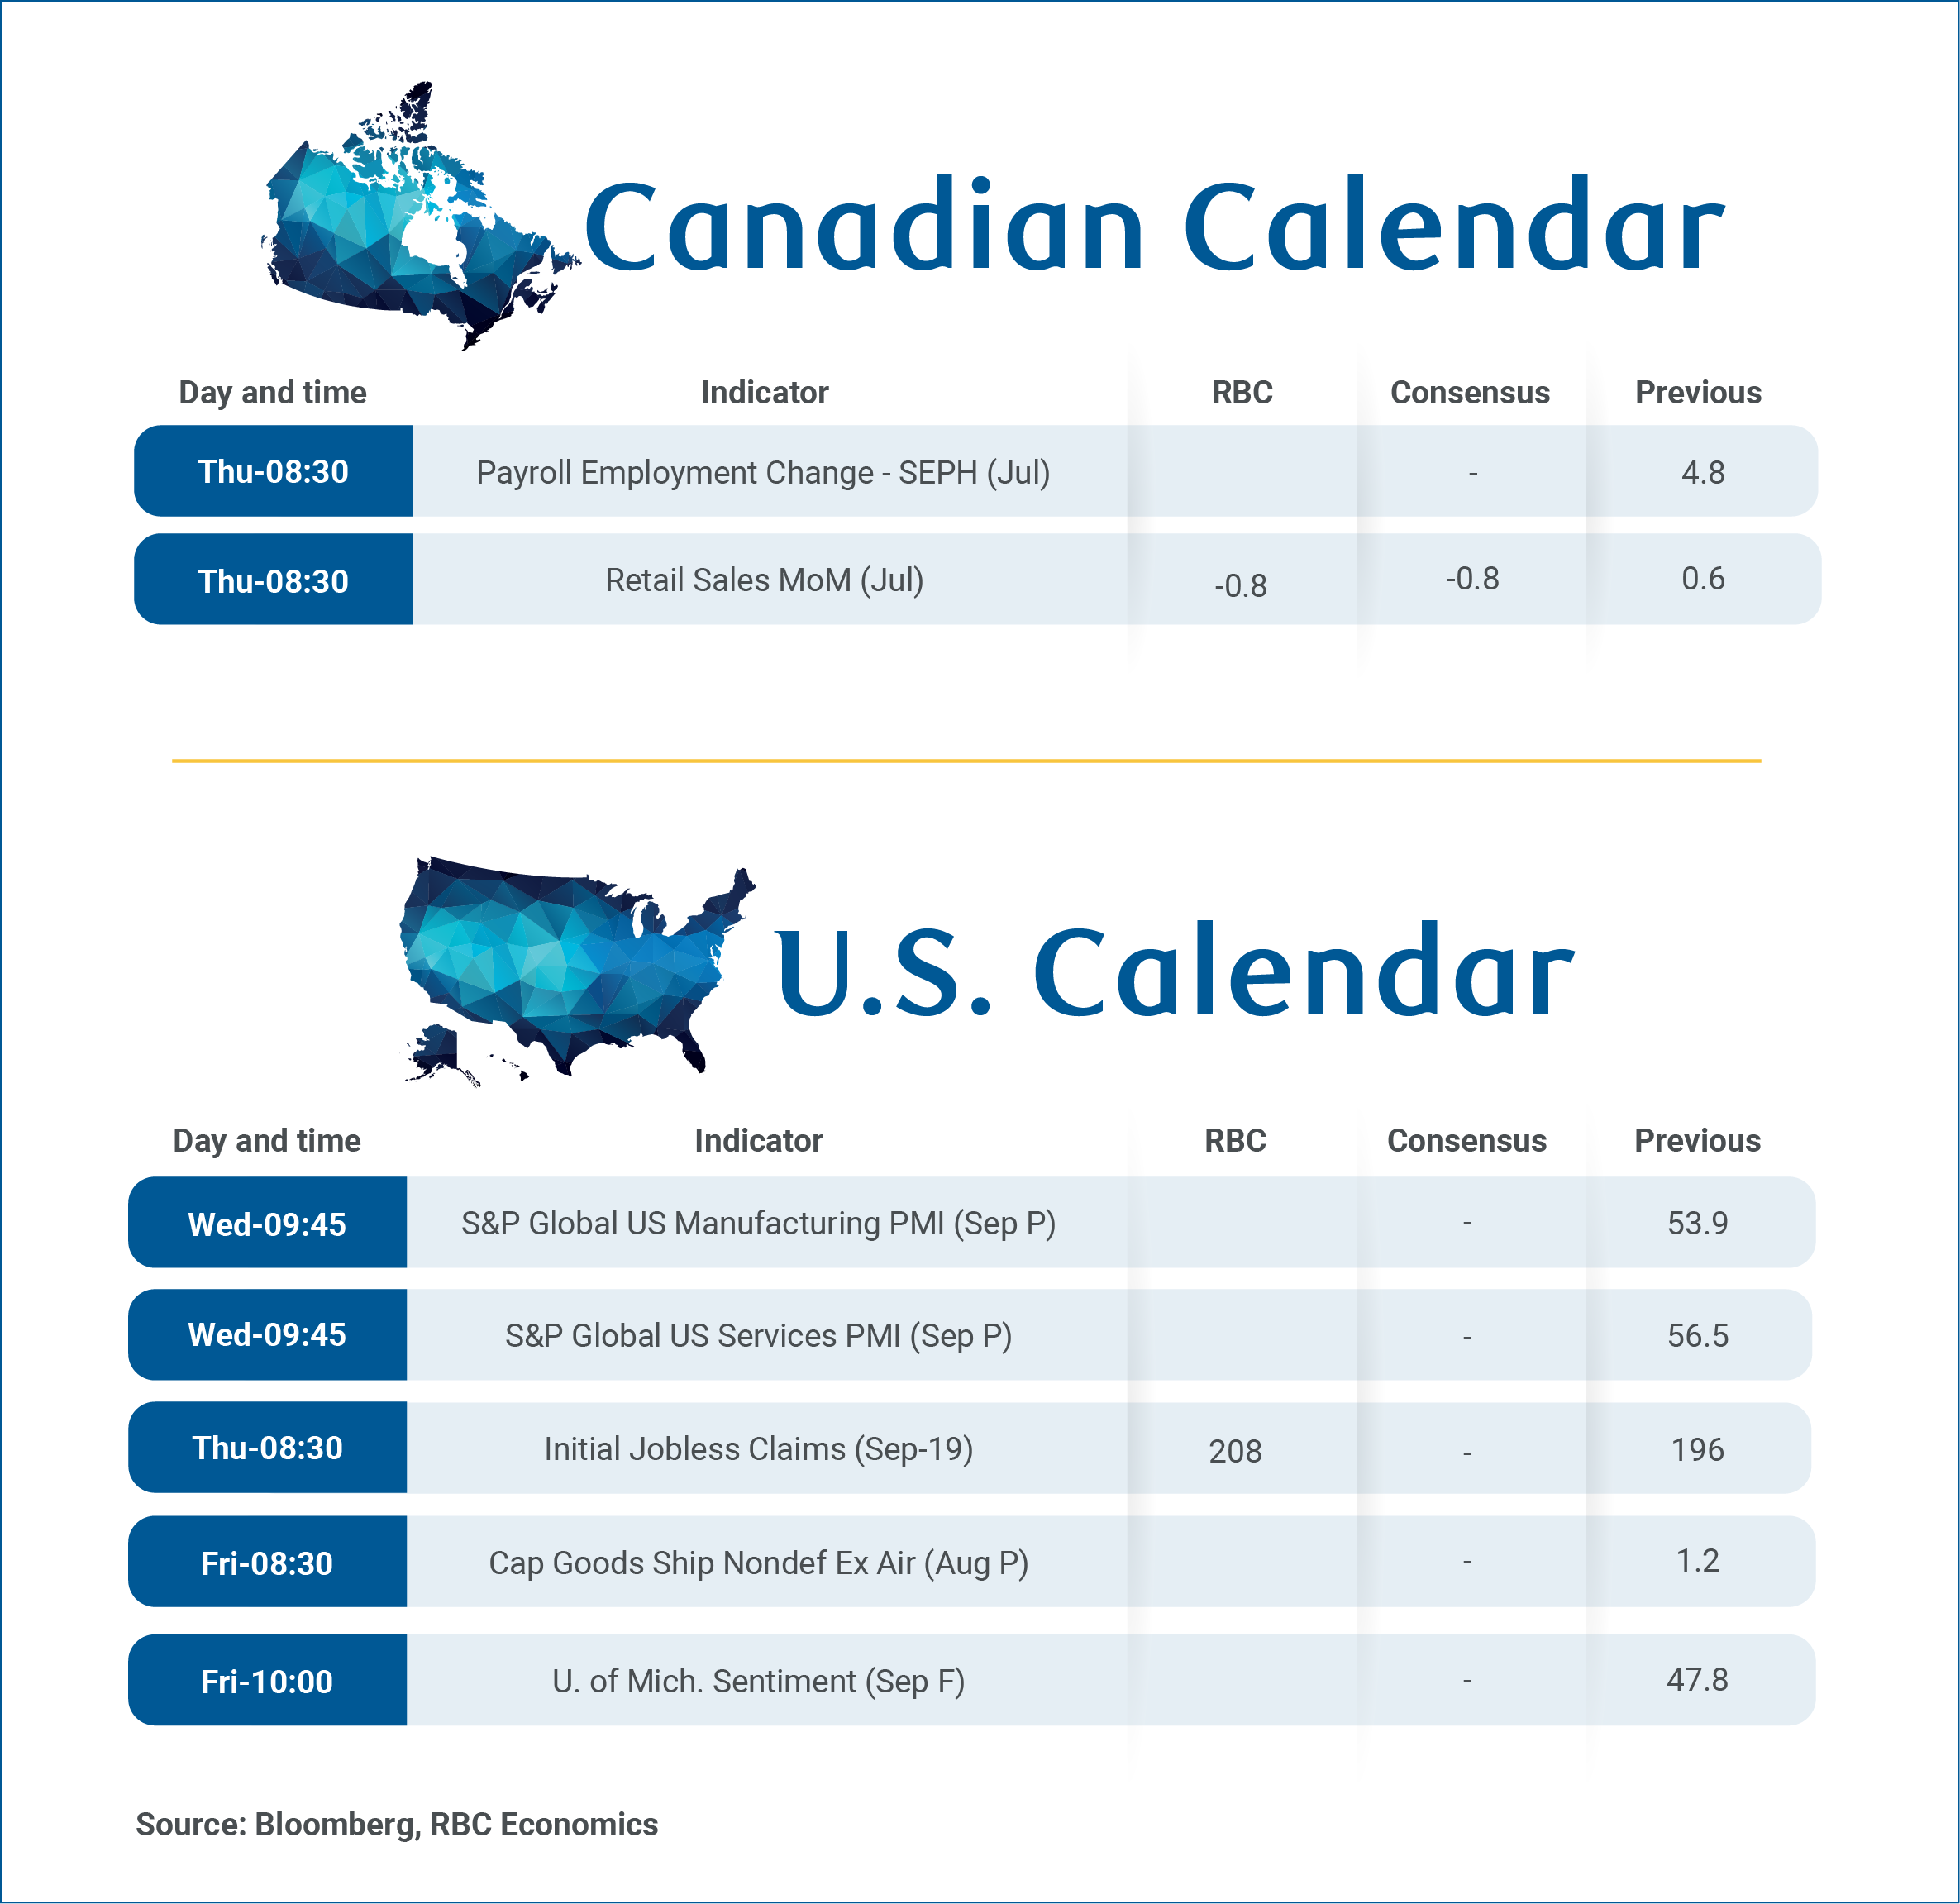
A lighter week of economic data will still be closely watched for signs that Canada’s broad-based growth rebound in Q2 extended to Q3. Key releases include retail sales and Survey of Employment, Payrolls and Hours data, and advanced August manufacturing and wholesale sales on Thursday and Friday.
Bank of Canada Governor Tiff Macklem is scheduled to speak on “economic developments” on Monday in Halifax, which could provide some additional guidance ahead of its interest rate decision on Oct. 28.
Retail sales to add to evidence of slowing growth after Q2 surge
We expect next week’s July retail sales data will be close to the advance estimate that showed a 0.8% decline from June, ending a six-month streak of gains.
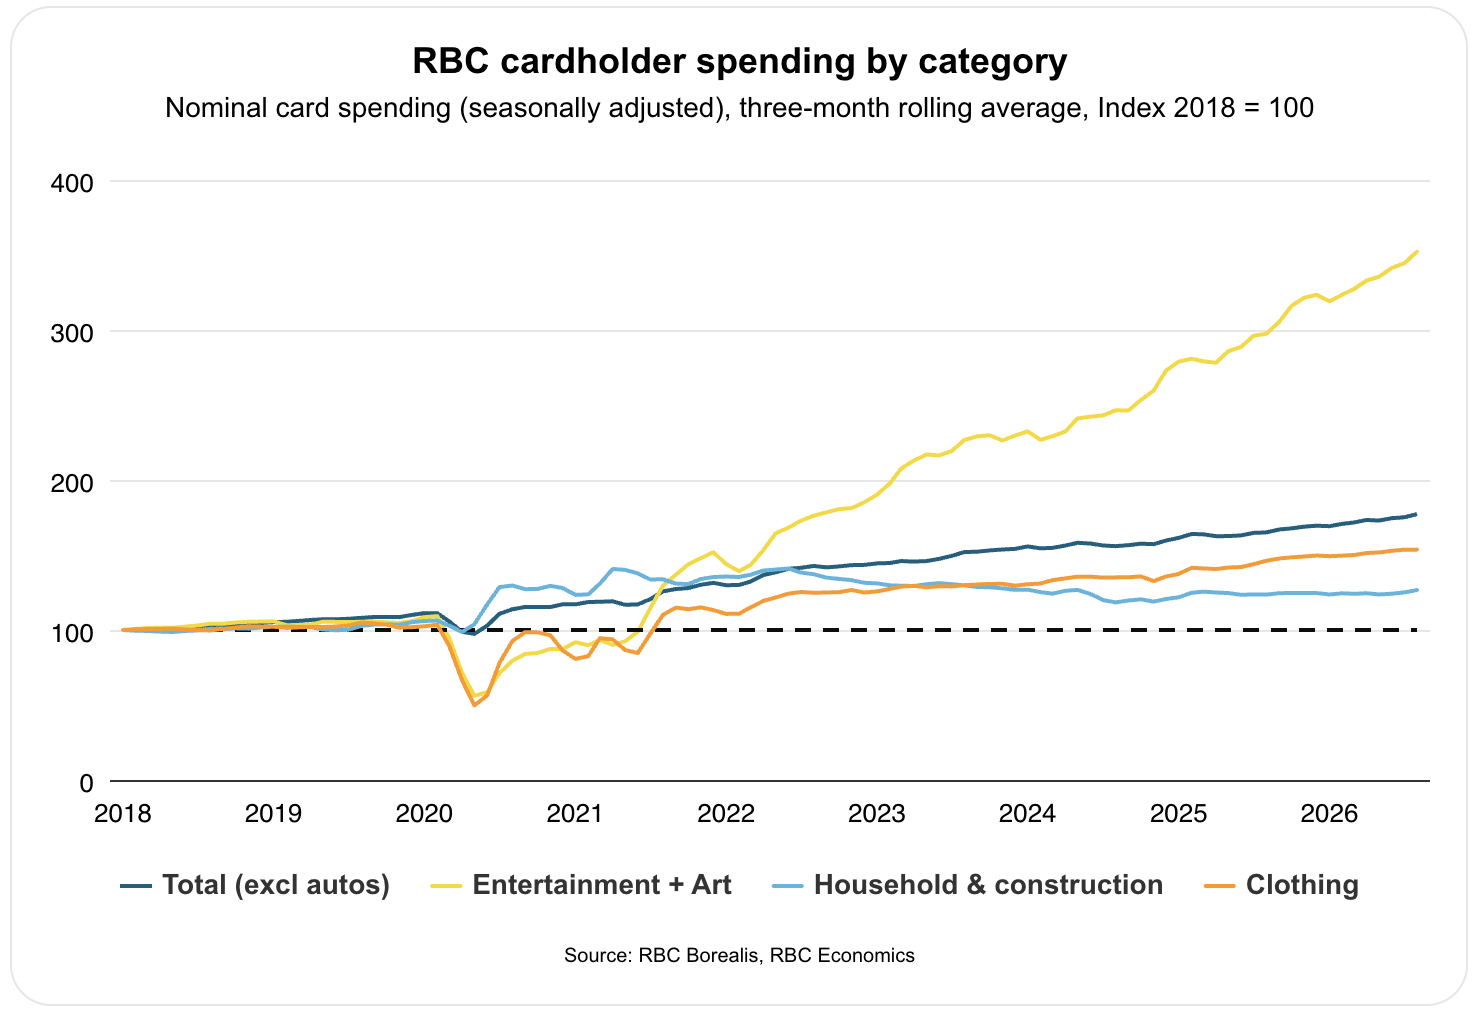
Underlying weakness was likely sharper when adjusted for gasoline price increases, with early industry data showing a big pullback in July vehicle sales. However, strength earlier in the year means volume sales likely remained relatively firm on a year-over-year basis after rising 2% year-over-year as of June. Our tracking of RBC card transactions, and a rebound in auto sales suggest strength partially returned in August.
Early wholesale and manufacturing sales reports also signalled a softer start to Q3—declining (excluding price impacts) 0.6% and 1.4% in July, respectively, after sizable Q2 increases. But labour market data has also held on to earlier improvements with the unemployment rate largely holding at 6.4% in Q3. This aligns with our view of slower, but still positive gross domestic product growth following 3.3% expansion in Q2.
Macklem’s speech to give clues on risk balance
On the central bank calendar, attention has turned to whether the BoC will hike interest rates later in October after the Federal Reserve raised rates for the first time since 2023 this week.
At its last meeting, the BoC flagged concerns about broader inflation implications from higher energy prices. Meeting minutes, however, clarified that policymakers are more focused on passthrough to general inflation than on elevated oil prices themselves, which the central bank cannot influence.
Evidence of passthrough to broader inflation has been limited so far, and we expect the impact in coming months will remain constrained as higher fuel costs erode margins across business supply chains before reaching final consumer prices. However, risks rise if oil prices remain elevated or further increase.
Policymakers will also have more information before October’s policy decision including another month of inflation and labour market data, plus the Q3 Business Outlook Survey showing whether firms’ inflation expectations have shifted in the current environment.
Our base case forecast remains that the BoC will begin gradually hiking rates in early 2027, driven by strength in the economy rather than the global price of oil. Risks to this forecast are tilting toward earlier hikes.
-
Canada’s second quarter population estimates are released next week, where we expect a third consecutive, albeit smaller decline in overall population from a persistent unwinding in the number of non-permanent residents after the government’s pivot on immigration policy. This should leave per-capita GDP growth up again in Q2, and still on a path of recovery after declines in earlier years.
About the authors:
Nathan Janzen is an Assistant Chief Economist, leading the macroeconomic analysis group. His focus is on analysis and forecasting macroeconomic developments in Canada and the United States.
Claire Fan is a Senior Economist at RBC. She focuses on macroeconomic analysis and is responsible for projecting key indicators including GDP, employment and inflation for Canada and the US.
Explore the latest from RBC Economics:
FOMC recap: Tightening into an inflationary supply shock
Spending across the board drove Canadian purchases in August
Road to recovery for Canada’s housing market hits a bump in August
Share these insights with your network:
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

