

 EN


Canada and the EU already shared deep cultural, commercial, and security ties before they brokered the Canada-Europe Trade Agreement (CETA), which came into effect nearly a decade ago. And as both sides pursue a more ambitious alliance in the wake of seismic geopolitical and trade disruptions, the transatlantic collaboration is emerging as a cornerstone of economic, energy and defence on both sides of the Atlantic.
CETA laid the foundation. The deal removed 98% of the tariffs in 2017 and has since vaulted the EU into Canada’s second largest trading partner, behind only the U.S. and ahead of China. Canadian goods exports to the EU have surged 80% over that time, while imports from the EU rose 60%. Once services are factored in, Canada exports $68 billion to the EU and buys back $124 billion.1
But serious challenges persist, holding many Canadian businesses back from exporting more—or at all—to the region. To get a sense of the obstacles and opportunities, RBC conducted a market survey of nearly 1,000 Canadian business owners in September. Here’s a sampling of what we heard:
-
“EU regulations are too complex.”
-
“China sells our products directly to EU countries, there is no room for us pricewise to compete.”
-
“Our service could expand to [the] U.S. fairly easily, but Europe would be more difficult.”
-
“I would sell to Europe if I could make a connection with a customer.”
While CETA has been in effect for nearly a decade, only one in five of the business owners surveyed were familiar with the deal and its benefits. And while there is interest in exporting to Europe, it often remains aspirational due largely to the time required to enter the market, distance and logistics, and a lack of access to expert support. That says nothing of the regulatory and tax burdens.
Still, as Canada focuses on a deeper alliance with Europe—one that will likely hinge on building on CETA—there is a significant opportunity. When it comes to the EU, Canada is massively under indexed on exports, and underweight on imports. If the two traded in accordance with their economic weight, Canadian exports of goods and services to the EU would more than double, rising to more than $150 billion. And EU exports to Canada would rise more than 40%, climbing north of $170 billion.
The gap in investment flows is equally stark. The EU has been exporting around US$360 billion in foreign direct investment (FDI) in recent years.2 The top destination—by far—is to other EU members, who receive 29 cents on every dollar. Canada has received just 1.4 cents on every dollar of the EU’s outward FDI, despite accounting for nearly 4 cents of every dollar globally. Likewise, the EU receives some US$300 billion in FDI, with Canada accounting for less than one cent on every dollar.
There is an abundance of cross-Atlantic opportunities to tap into: from high-tech manufacturing and defence to clean-tech energy and conventional resources as diverse as natural gas, oil and gas, potash, uranium and fertilizers. As Canada casts its net wider for new trade routes, Europe is emerging as a promising port of call.
Manufacturing: Proven ties, but plenty of runway
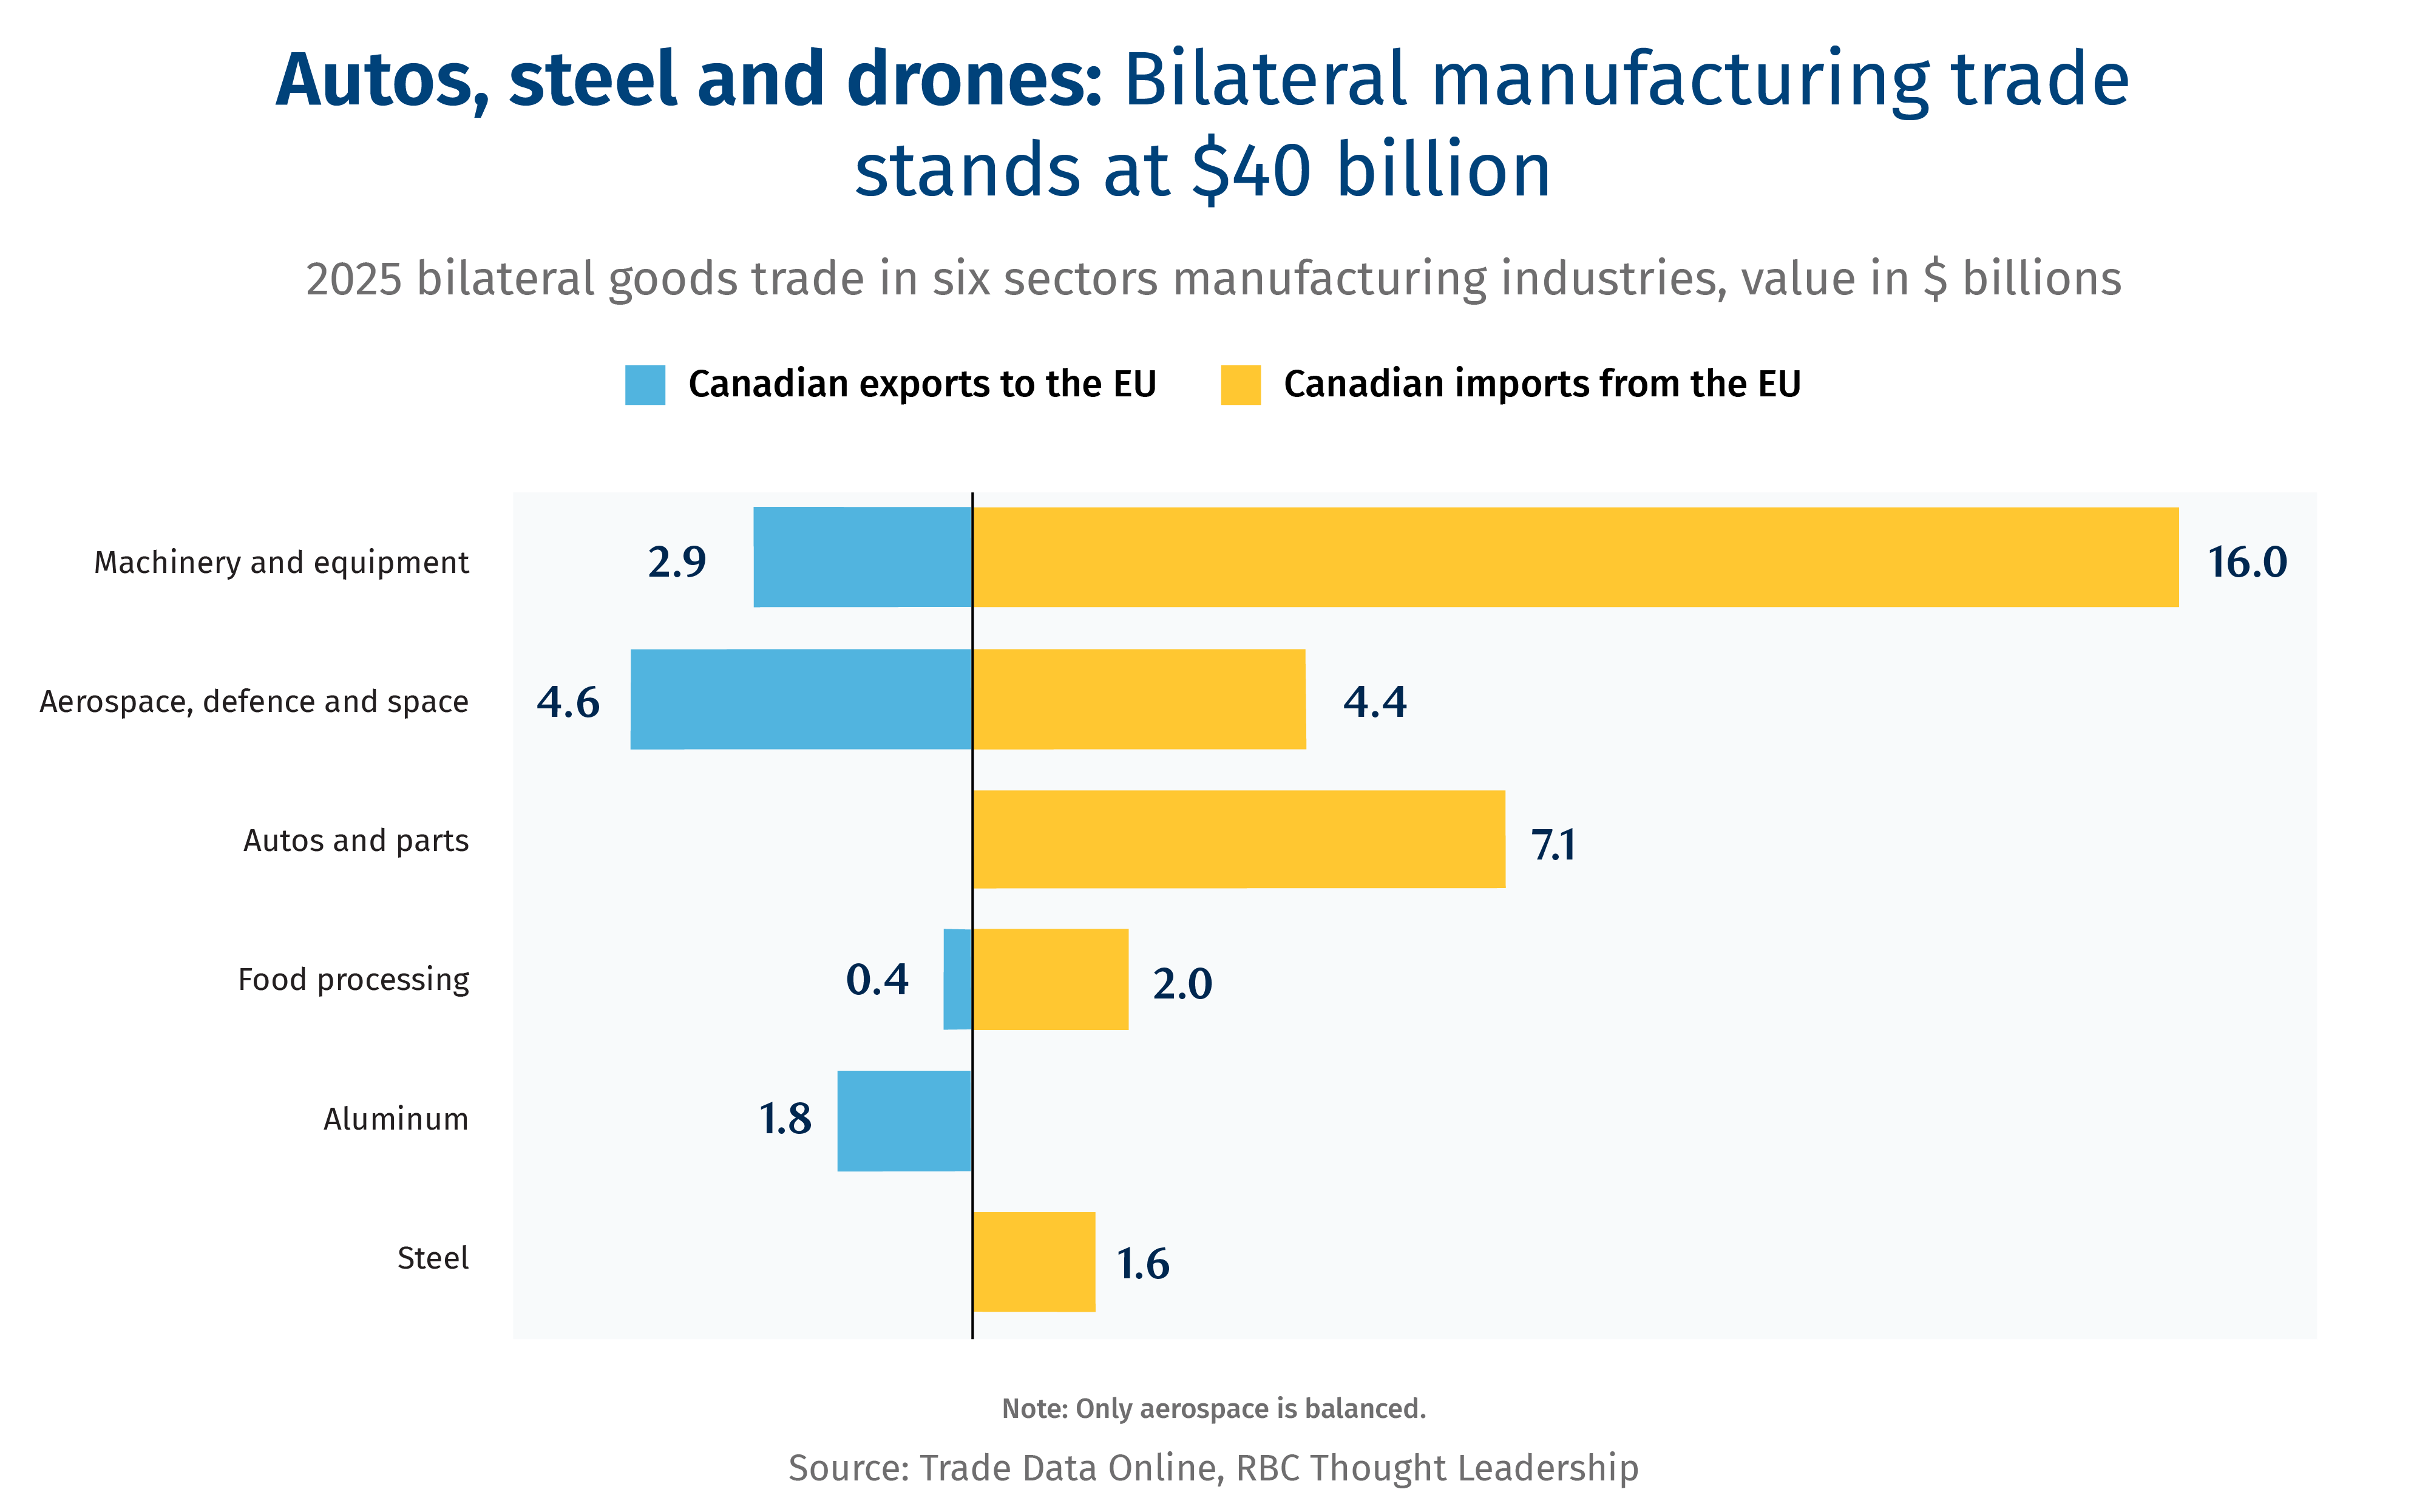
Aerospace shows that two-way manufacturing trade across the Atlantic works, with further opportunity in the steel and aluminum sectors. Auto assembly is likely to remain challenged, until tariffs are lifted and the North American market electrifies.
North American and European manufacturing industries are struggling with excess capacity, weak domestic demand, and heightened competition from China. Global trade tensions complicate an already fragile economic reality. But there are opportunities for coordination in specific parts of advanced manufacturing.
Canada sells the EU raw and semi-processed goods and buys finished products. Manufactured goods are about 65% of Canadian goods exports to the EU (roughly $28 billion) but nearly all of what Canada buys back (roughly $90 billion). That $62 billion shortfall is softened by a $14 billion resource surplus, which leaves the ~$50 billion goods deficit.
The aerospace industry is the exception to that trend, albeit a narrow one. Canada sold the EU $4.6 billion of aerospace products and parts in 2025 and bought $4.4 billion. Exports are up 60% since 2017. It could form a template for further deepening of ties when it comes to advanced manufacturing.
The growth potential
If Canada and the EU traded in accordance with their economic weight, Canadian manufacturing exports would more than double to $65 billion, while EU manufacturing imports would climb past $110 billion.
Aerospace is the template. Extend the same supply-chain model to other areas of advanced manufacturing, including defence aviation, space, electric vehicleassembly, auto parts and build on existing ties for steel and aluminum.
Low-carbon aluminum is an opening. Canada is the world’s fourth-largest primary producer (3.3 million tonnes in 2024) and reports the lowest carbon footprint among major producers. The U.S. took 90% of Canadian exports in 2024.3 The EU’s carbon border levy (CBAM) entered its definitive phase in January 2026, covering iron, steel and aluminum. Under CBAM, carbon intensity becomes a pricing differentiator. Brussels deducts carbon prices paid abroad, but only what is actually paid counts, net of rebates and free allocation, all of which must be independently certified.4
Steel is a smaller prize. Canadian mills sell little to Europe today and quotas are tight. The EU’s regime caps quota volumes at about 18 million tonnes and charges 50% above that threshold. Canada is listed as a free-trade partner but has not secured any quota of its own. The CETA goods committee has a technical meeting on overcapacity and an exchange on Canada’s melt-and-pour rules in train.5 Canada could use it to ask for a country quota, or guaranteed access to the pooled one, and offer reciprocity on Canada’s own quotas.
Autos: capitalize on existing EV investments, position to win new mandates. In Canada, final assembly is dependent on duty-free access to the American market, not CETA. Some 90% of what Canada produces is exported, and 90% of those exports go to the U.S. Parts and battery materials are less constrained. Canada’s goal of 75% EV sales by 2035 could eventually anchor demand, but is hemmed in by U.S. policy. Given the absence of EU-based assembly plants in Canada, and their absence of mention from Canada’s new auto strategy, the possibilities around enhanced partnership are limited.6 Options to catalyze investment include:
-
Co-invest with EU manufacturers. The Strategic Response Fund backed Volvo’s Prevost with $18.5 million on an $87.5 million project. Similar terms could be offered to EU parts, battery, and machinery makers.7
-
Canada’s EV incentive rules. EV incentives cap the price of imports from free-trade partners at $50,000, but not Canadian-made EVs, which face no cap.8
Agriculture: Room to grow
Burdensome regulations have limited Canada’s ability to make Europe a key export market, but there are opportunities ahead in supplying the bloc with critical agriculture commodities, including grains, protein and potash.
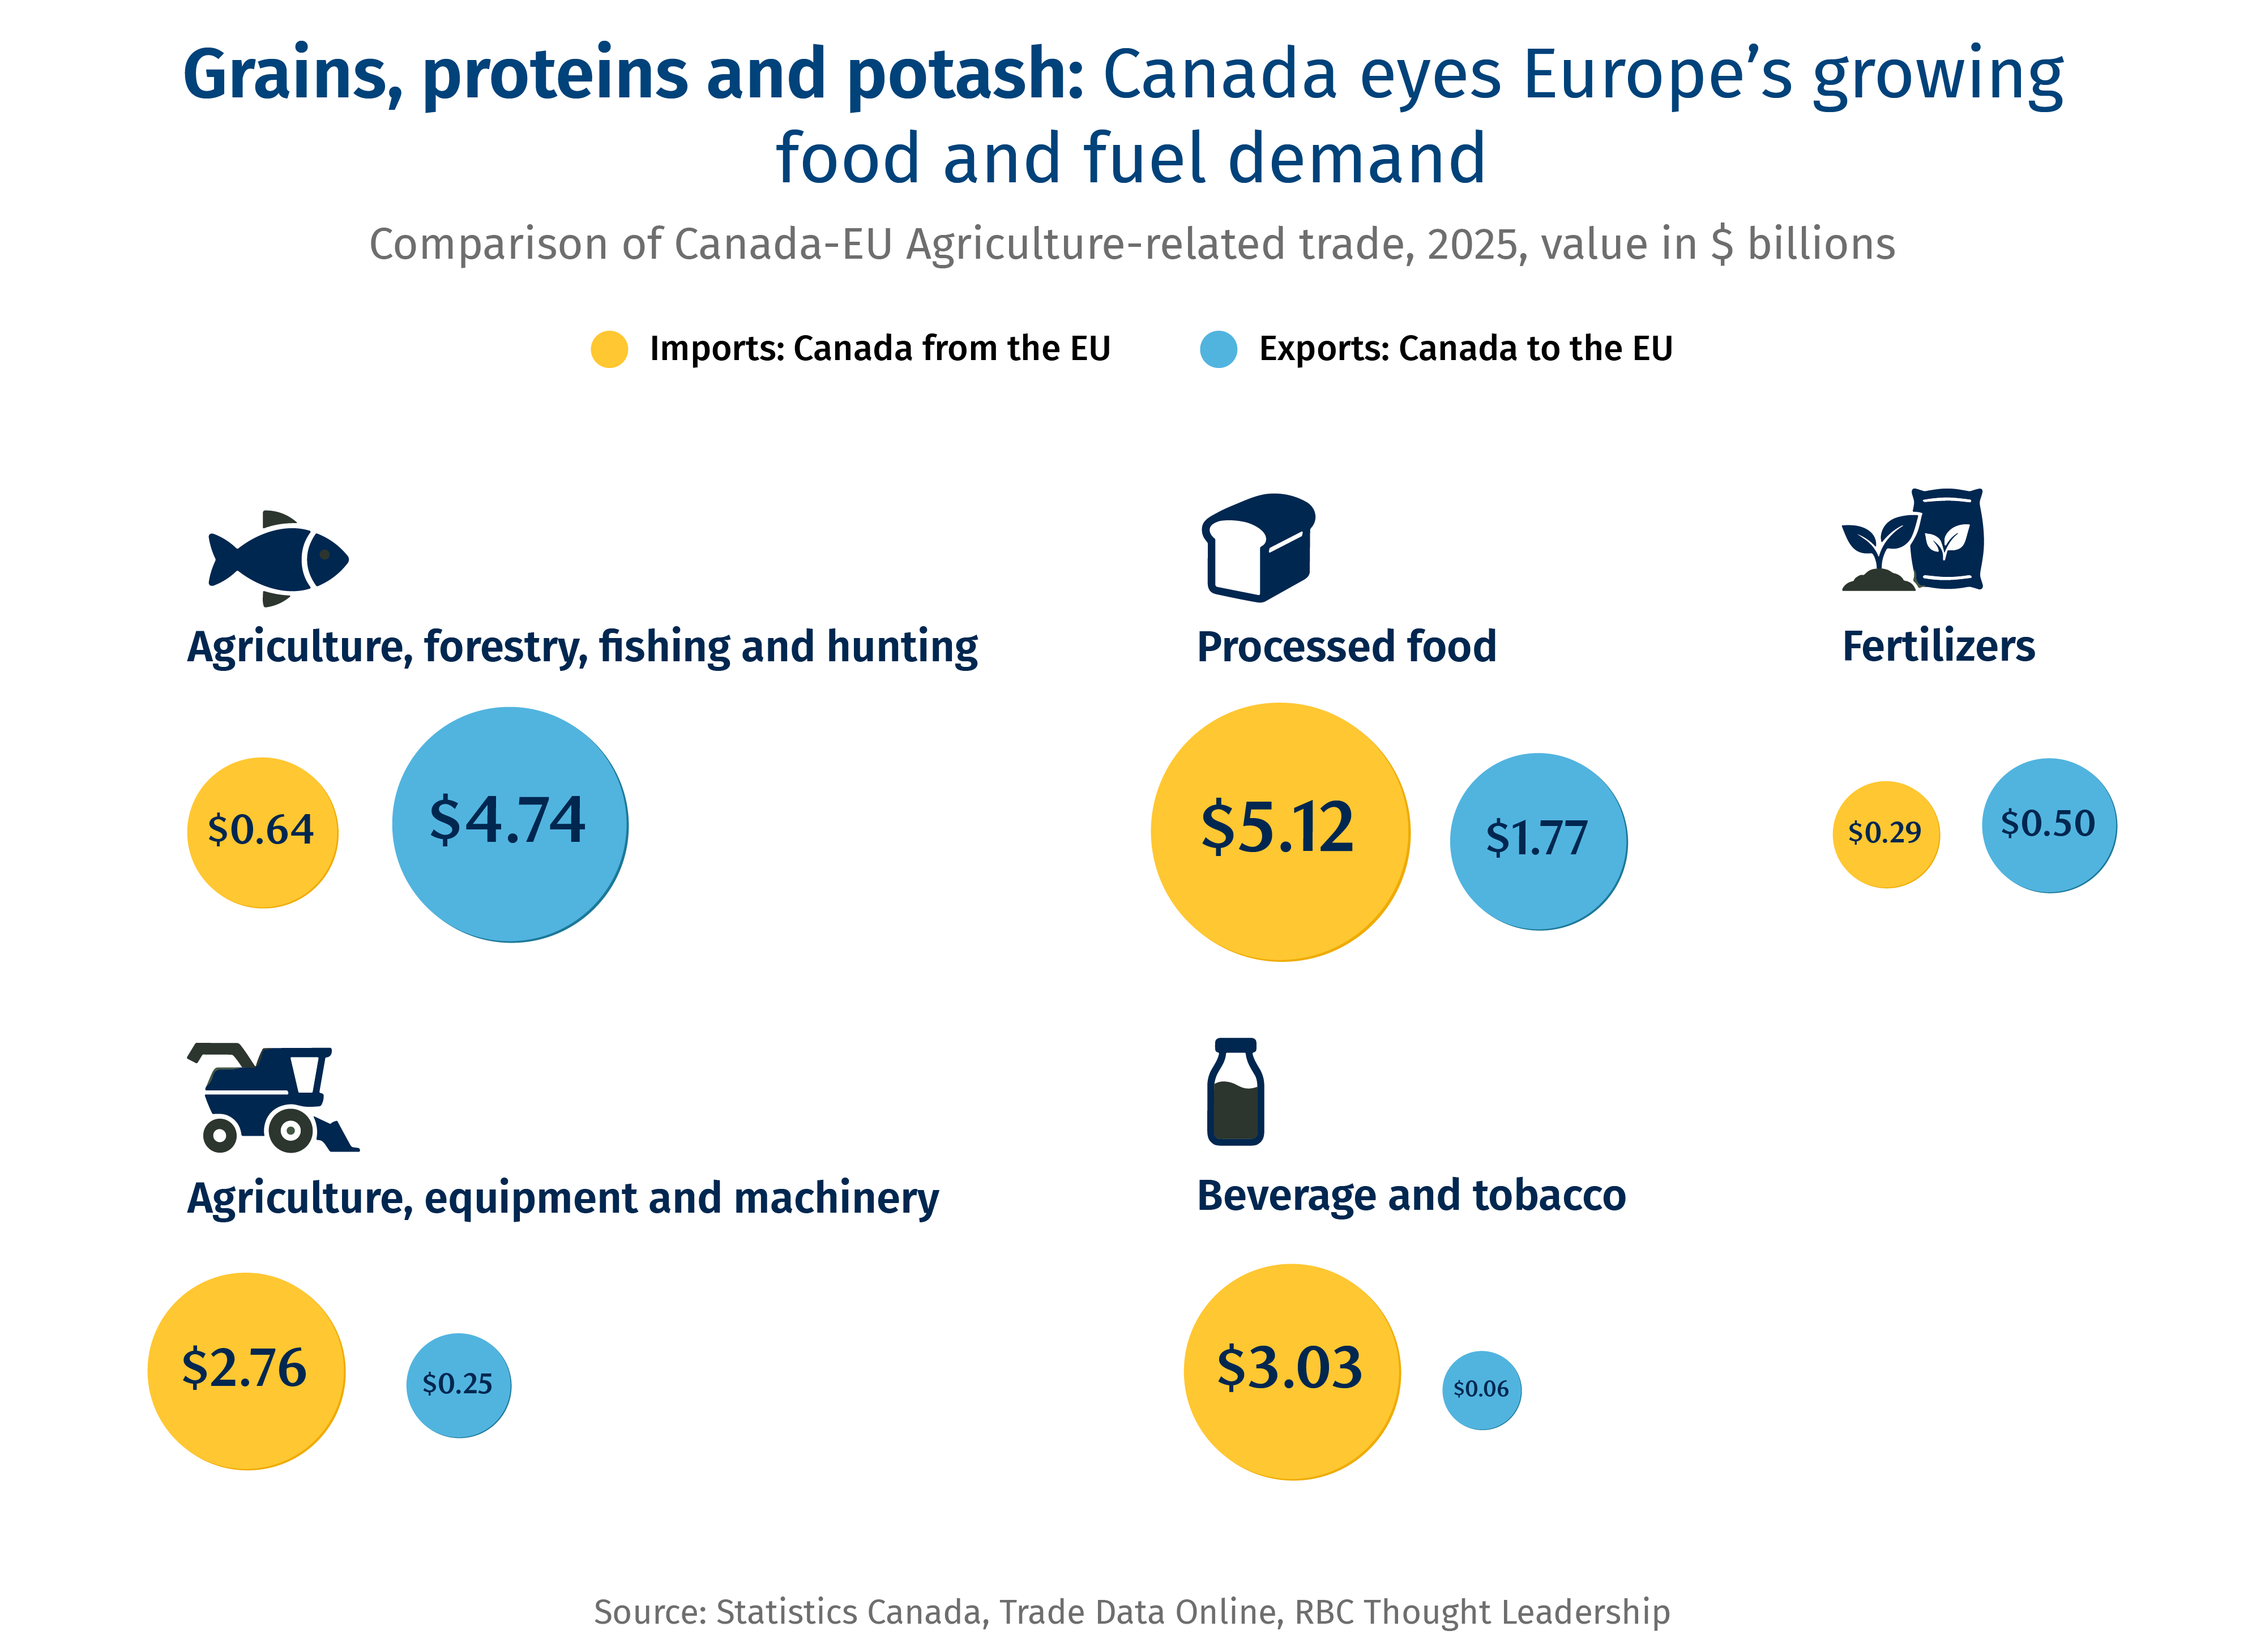
The value of the farm and food trade between Canada and the EU has roughly doubled in both directions since CETA took effect. Yet, the EU still only accounts for a small share of what Canada exports, at just over 6% of its Agri-exports in 2025. Canada sold the EU $7.32 billion of farm, fish, food and agriculture input products in 2025, and bought over $11-billion worth in return.9
The type of agricultural goods Canada and the EU exchange are very different. Europe is a large, wealthy, and mature food market that is already self-sufficient in most staples. The EU exported €238 billion worth of agrifood products last year10, with close to a €50 billion surplus, so its Canadian imports are goods or commodities it doesn’t produce in such large volumes, like primary grains. Canada’s major shipments to Europe are largely bulk grain and oilseeds, including canola, soybeans, wheat and corn, as well as potash fertilizer, while Europe’s food export basket to Canada primarily consists of prepared foods and drinks, such as wine, spirits and cheese, along with farm machinery.
The growth potential
As the EU looks to improve resiliency in its agri-food supply chain, and Canada looks to grow its exports beyond the U.S., there are multiple areas that can benefit both partners.
Protein and oilseeds offer clear room to grow. In 2025, Canada bought $106 million of pork and $71 million of beef from Europe, while selling the EU just $6.5 million of pork and $24 million of beef.11 Growing those sales depends partly on Canada pressing the EU to recognize its food safety and quality standards, which currently limit Canadian exports.
Canada’s low-risk rating under the EU’s new deforestation rules, which cover cattle and soy, gives Canada a modest advantage over countries like Brazil and Argentina. Canola exports to the EU exceeded $1 billion in 2025, most of it seed crushed for biofuel, with meal going into animal feed. The EU is phasing palm oil out of its biofuel schemes by 2030, which leaves more room for sustainably produced Canadian canola.
Fertilizer is another strong opportunity. The EU began phasing in tariffs on Russian and Belarusian fertilizer in 2025, rising to €430 a tonne by 202812, to cut its dependence and Russia’s war revenue. Canada is the world’s largest potash producer, with about a third of global output13, and supplied 39% of world potash exports in 2024, about the same as Russia and Belarus combined.14 Canadian producers could sell more in Europe if they expand output and if rail and port capacity can move it east, or through the seasonal port at Churchill.
Regulations remain an obstacle. CETA did not change the regulatory requirements to access the EU market, limiting its ability to translate into higher Canadian exports. Examples of these requirements include restrictions on growth hormones in livestock, the use of peroxyacetic acid to control bacteria on meat carcasses, and testing for trichinosis, a disease Canada is free of.15 Compliance challenges are a key reason Canadian beef exporters use only about 3% of their EU duty-free quota.16 Most Canadian feedlots use growth hormones on cattle, and Canada’s two largest meat packers use sanitation products not accepted by the EU. Other EU rules, like those governing genetically modified crops, maximum pesticide residue levels, and sustainability requirements like deforestation prevention, further complicate market access and constrain export growth.
However, Canada’s National Food Security Strategy, which aims to strengthen competition in domestic food processing, could create an opportunity to develop a more flexible processing capacity tailored to export markets with distinct regulatory requirements that could help producers reach the EU in a more meaningful way.
Domestic infrastructure investment could open the doors to the EU. The United States is Canada’s largest trading partner, taking over 60% of Canada’s agri-exports in 2025.17 Canadian farms, packers and processors are built into North American supply chains that shared a common set of rules. As it stands, shipping Canadian agri-food products from points of production, which is often the Canadian Prairies, to the eastern ports that serve European markets is expensive – generally even more so than shipping across the ocean. Efficiency enhancements and other domestic infrastructure investments are core to growth in transatlantic trade.
Critical Minerals & Energy: Atlantic alignment
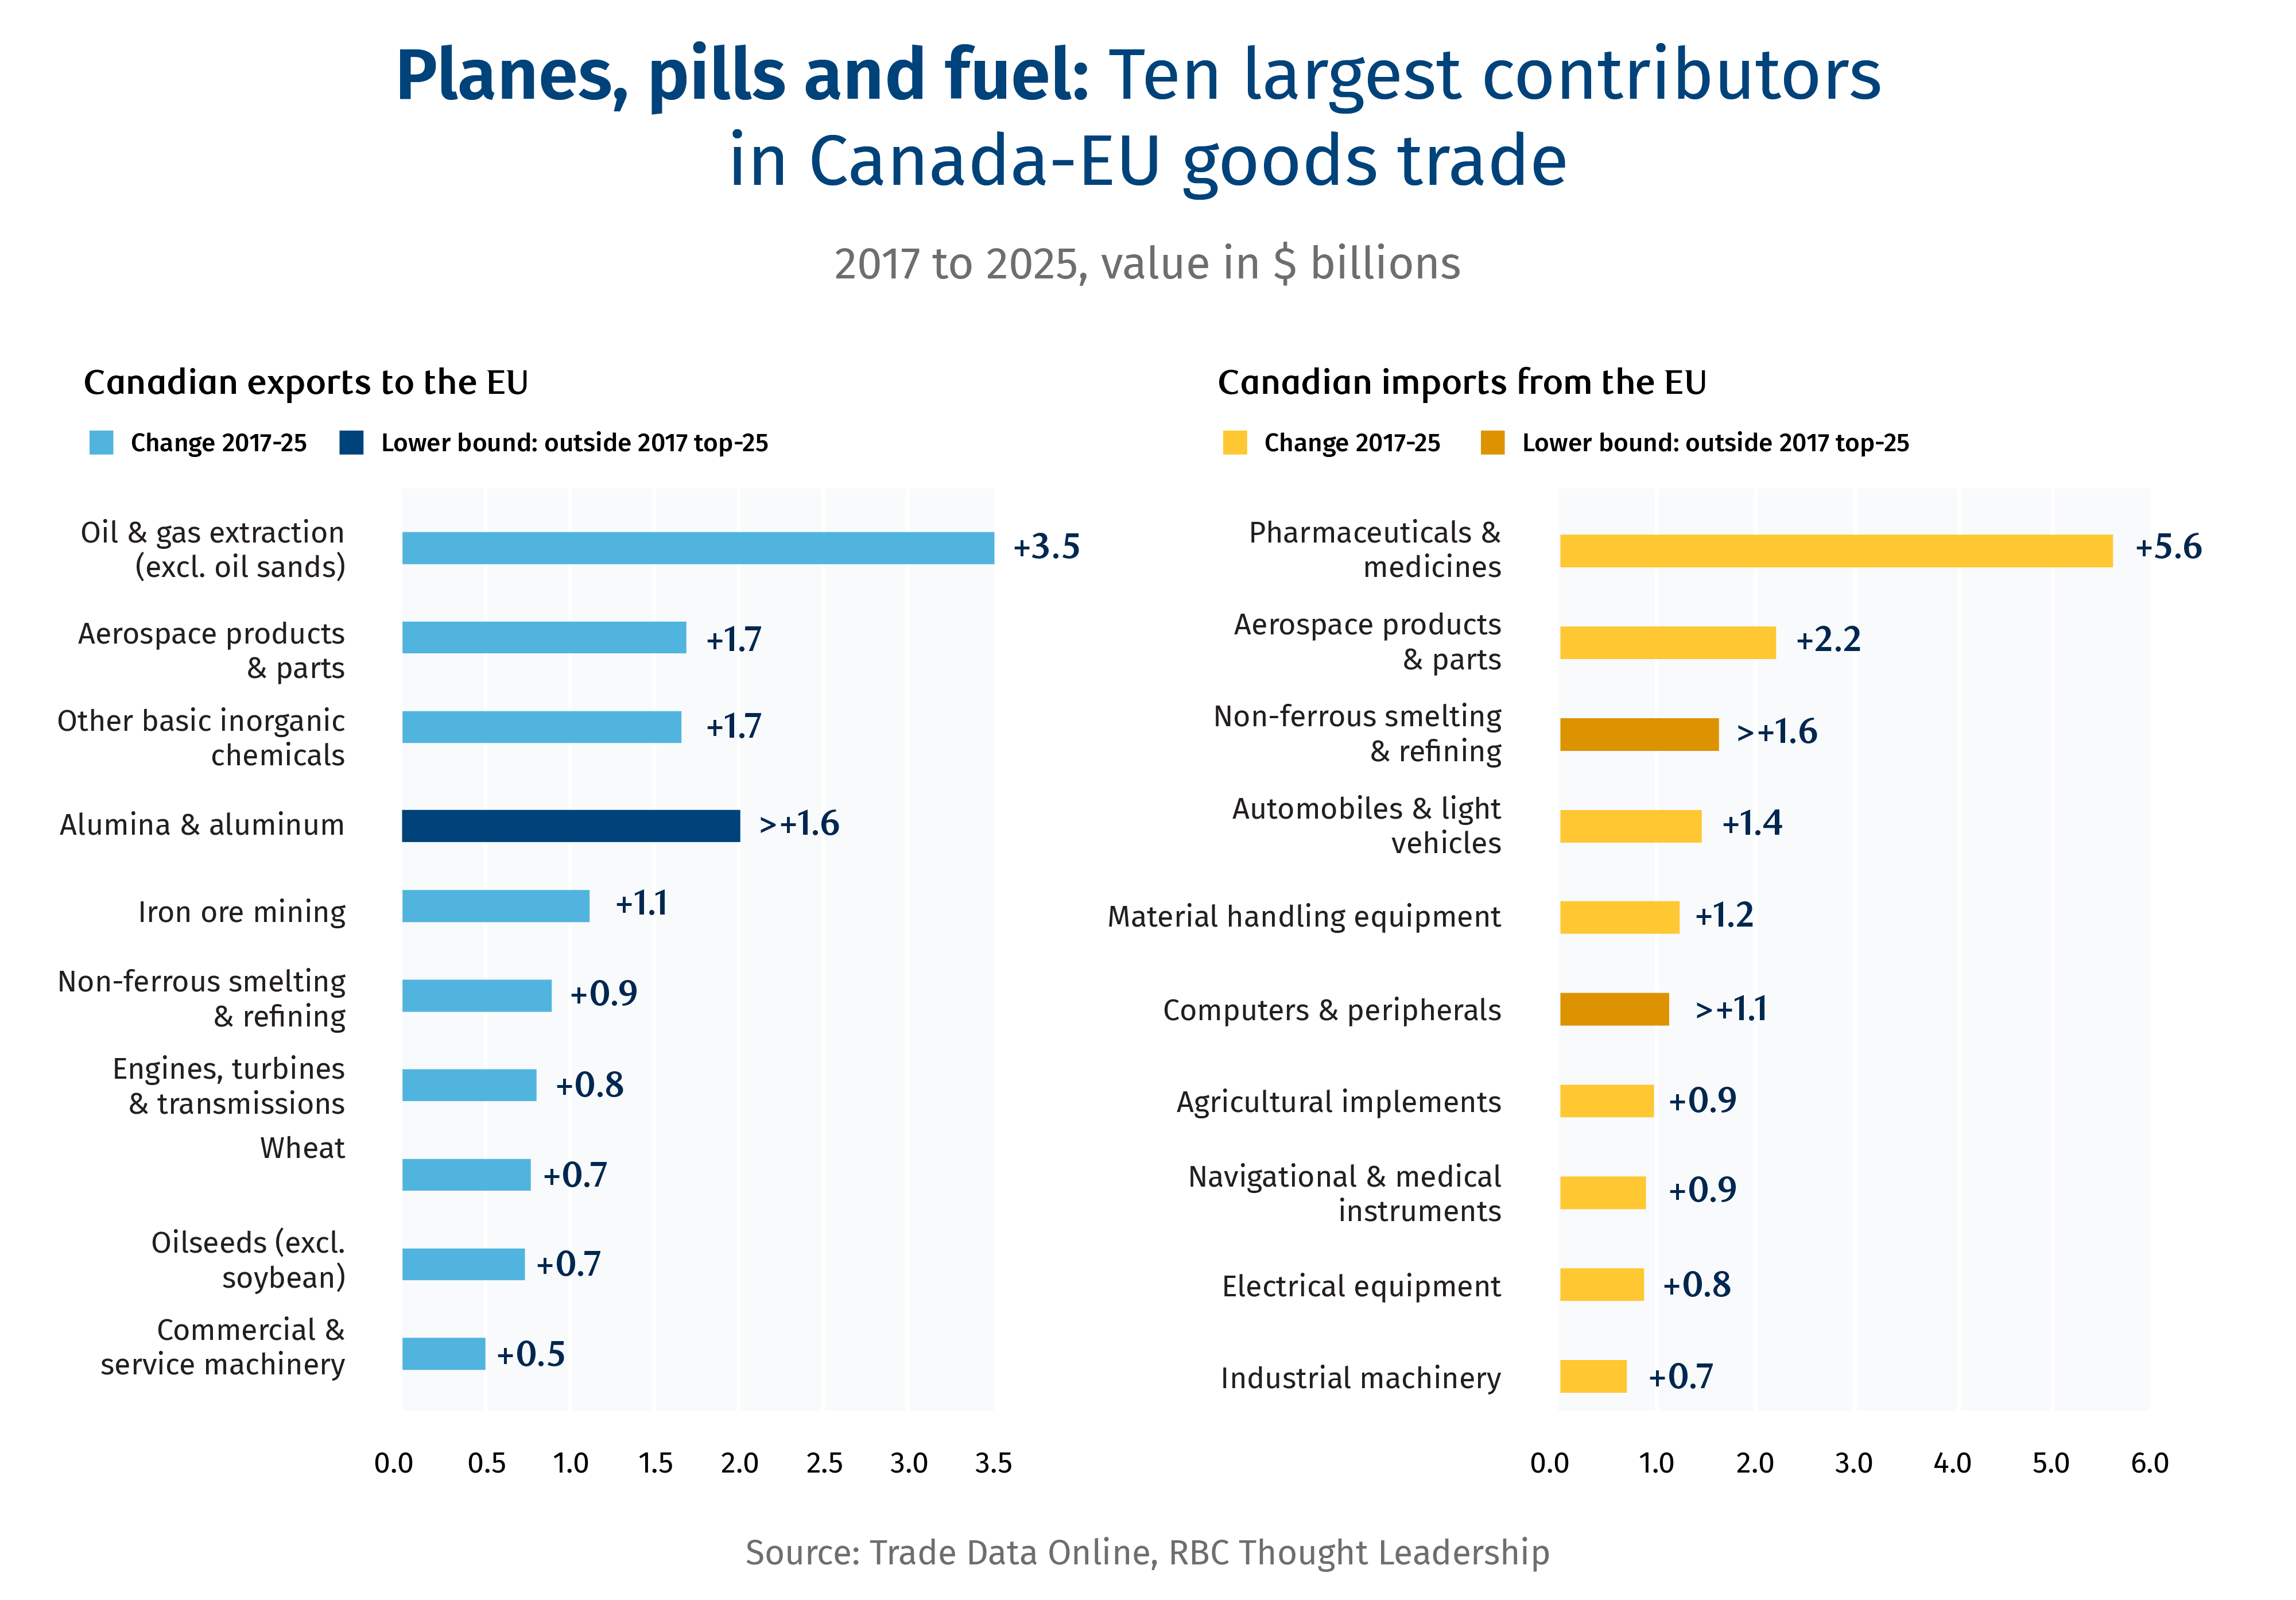
Europe’s greatest need is energy, which is also Canada’s biggest strength, yet the two barely connect. Unlocking energy routes, and supplementing it with rising minerals, nuclear fuel and potash trade, could improve energy security and diversification for both jurisdictions. Canadian oil and minerals are reaching Europe in record volumes, but from a low base. Mineral exports nearly doubled to $10 billion in 2025 from 2017, while energy (oil, gas and uranium) grew six-fold to $6.5 billion. Together, this makes up 38% of what Canada sells to the EU, up from 28% in 2016.
That growth says little about CETA itself. Crude oil was already duty-free, and the agreement removes tariffs only on refined and processed products, at up to 4.7% for non-crude petroleum. Canada’s energy flows are shaped more by geography than tariffs, with its oil and gas organized around the U.S. market.
Geopolitics is changing that. Europe’s hostile relations with Russia, one of its principal energy sources, and turmoil in the Middle East present an opening for resource-rich Canada. Aggressive U.S. trade policy has only added to the urgency on both sides. Europe’s demand for secure, non-Russian and non-Chinese supply is now written into law: the EU is ending Russian pipeline gas by September 30, 2027, and its raw-materials rules push buyers toward diversified suppliers.
Canada runs a goods deficit with the EU of about $49 billion, but energy and minerals enjoy a combined surplus of about $6 billion. Minerals and metals exports stand at $10 billion, with the EU taking 7.4% of Canada’s exports, though the basket is mostly iron ore ($3 billion), aluminum and nickel.
The growth potential
The EU wants to diversify its energy supply, and Canada its market base. The alignment could come from natural gas but also minerals, and nuclear fuel. With meaningful economic, emissions and energy-security gains at stake, resources could prove to be the biggest area of cross-Atlantic collaboration.
Oil demand has limited potential but could still expand. Europe favours the light-sweet grade from the Newfoundland and Labrador offshore; exports hit a high of $3.9 billion (from $2.1 billion in 2024 and $300 million in 2016), partly as U.S. tariffs pushed exporters to find other buyers. Meanwhile, much of Canadian energy infrastructure points south, with the U.S. taking about 90% of its crude, refined product and gas exports. Ironically, Canada is a net importer of refined fuel with the EU, which supplied around $2.2 billion in 2025, (mostly from the Netherlands and Belgium into Quebec and Nova Scotia), with exports at $800 million. Long-term EU demand for fossil fuels is forecast to shrink, which makes it harder to build new Canadian energy infrastructure facing east. The International Energy Agency projects a 730,000 barrel-a-day decline by 2030, while Asia sees a two-million-barrel-per-day increase. EU gas demand is forecast to fall from 275 billion cubic metres to as low as 190, by one estimate.
Canadian gas has a strategic role to play. All of Shell-backed LNG Canada’s 2025 cargoes were destined for East Asia, and its Phase 2 expansion targets Asian customers. There are circuitous routes, however, to get Canadian gas to European customers. Germany’s state-owned SEFE recently signed a conditional agreement for one million tonnes per annum (mtpa) from the First Nations-backed Ksi Lisims LNG project, and Uniper a binding 20-year deal for 2 mtpa, with first deliveries in 2032. But both are destination-flexible, and France’s TotalEnergies, with its own 2 mtpa deal, said it would serve Asian customers. Europe may end being a customer and financier of Canadian LNG, but not always its final destination.
EU’s emissions rules could favour Canadian energy. The EU’s Methane Regulation requires fossil-fuel importers to demonstrate equivalent monitoring, reporting and verification from January 1, 2027, with emissions-intensity limits from 2030. Proposed delays remain under negotiation, reflecting concerns about energy costs and supply security, but structurally this is a win for Canada either way (low intensity and politically stable). Canada’s methane controls could help its LNG suppliers meet these requirements and appeal to European buyers; electric-drive liquefaction powered by B.C.’s low-carbon electricity would place Canada amongst the lowest emissions intensity LNG, globally. This could strengthen Canadian LNG’s appeal through either direct delivery or cargo swaps, subject to EU compliance requirements.
Filling the processed critical minerals refining gap. China dominates processing of most battery minerals, so Canadian nickel or cobalt refined in China does little to reduce Europe’s dependence. The EU’S Critical Raw Materials Act’s 2030 benchmark, which states that no more than 65% of any strategic raw material can come from a single third country, could change that. A 2026 joint statement and non-binding letter of intent between the European Investment Bank and Canada could lay the groundwork, and Quebec’s Dumont nickel project is the one Canadian project the Commission has named a third-country strategic project, which can open access to EU financing. What is missing is offtake and processing: European buyers committing to Canadian nickel, cobalt and aluminum, and refining built in Canada rather than China.
Nuclear fuel is the most direct way to displace Russia. Uranium is the one commodity in which Europe is a major Canadian customer, taking as much as 45% of its uranium exports, according to one estimate. Canada is already the largest uranium supplier to EU utilities, with Saskatchewan-based Orano (25%) and Cameco (21%) providing a sizeable portion of EU’s processing needs. Russia still supplies about a quarter of EU conversion services (Rosatom, 24%) and enrichment (23%), so long-term contracts between Canadian suppliers and EU utilities are the most direct way to displace it. The Commission promised limits on Russian nuclear fuel in 2025, but there is scant evidence of alternative sources being pursued.
Defence & Space: The new allyship
As the only non-European country admitted to the EU’s Security Action for Europe (SAFE) program, Canada is uniquely positioned to build a deeper partnership with its transatlantic allies.
Rising threats from Russia following its 2022 invasion of Ukraine has compelled the EU to bolster its defence industry, with spending set to rise to a record €454 billion ($704 billion) this year, from €418 billion ($648 billion) last year.
In addition to national budgets, the SAFE program lends governments €150 billion at low interest to buy weapons. Normally no more than 35% of a SAFE-funded product’s parts can come from outside Europe, but Canadian parts can make up to 80%.
So far Canada has barely leveraged that advantage: Canada’s exports make up 0.5% of the EU’s defence equipment spending, or about $900 million in 2025. That has gone primarily to Germany ($372 million) and Poland ($217 million).
As global defence needs rise in a more uncertain world, a slew of new opportunities could boost those export numbers. But first, Canada will need to bulk up: Most domestic defence firms are small, and the industry sells 70% of its goods to its Five Eyes intelligence partners: the U.S., U.K., Australia and New Zealand.
The growth potential
Embedding themselves in Europe’s defence supply chains would help Canadian companies advance Ottawa-Brussels efforts to boost security cooperation.
Canadian aerospace could fill an immediate European need. Canada supplied 8.9% of the aircraft, spacecraft and parts imported by the EU in 2025. Germany recently strengthened its independent intelligence capabilities with the procurement of at least three additional Pegasus signals-intelligence (Signit) aircraft based on the Bombardier Global 6000 business jets and is considering an expansion of the fleet by three to six additional units.
Join the Ukraine loan program to widen access. The EU has loaned Ukraine €90 billion ($140 billion) to cover about two-thirds of its financial and military needs in 2026 and 2027. That aligns with Ottawa, which has committed $8.5 billion in military aid since 2022, and with several Canadian firms, including Roshel, Dominion Dynamics and Sentinel R&D, building production partnerships with the Ukrainian industry.
Canada can also seek a cooperation agreement to explore integration into the EU’s IRIS² satellite constellation, as South Korea did in September.
Canada could use its multi-billion defence contracts to embed its companies in the EU’s supply chain. Ottawa recently awarded Germany’s Thyssenkrupp Marine Systems (TKMS) as the preferred supplier for up to 12 submarines—the largest defence procurement in Canadian history. Meanwhile, Sweden’s Saab has bid to build Gripen fighters and GlobalEye surveillance aircraft in Ontario and Quebec if Canada buys them.
Products made in EU factories count as European under SAFE and the loan’s buy-European rules, so work done at Roshel’s Czech joint venture and Davie’s Finnish shipyard qualifies. Ottawa could also leverage its submarine contract and fighter plane contracts to bring Canadian suppliers into the European supply-chain ecosystem.
Supply drones, water bombers and other defence equipment to Europe. The European Drone Defence Initiative, a network for detecting and halting hostile drones, is due to commence by the end of 2026. Ottawa is positioning to capitalize: it has awarded $50 million in contracts to six Canadian drone makers and opened a marketplace of about 400 vetted Canadian suppliers modelled on Ukraine’s Brave1defence-technology accelerator.
Ground vehicles and their parts were Canada’s largest category of permitted military exports in 2025, worth $930 million across all non-U.S. markets. Canadian firms could also pursue opportunities to build those as part of the EU’s Eastern Flank Watch, a project to strengthen defences along the bloc’s eastern borders.
Meanwhile, as EU braces for frequent wildfires every summer, Calgary-based De Havilland has a deal to supply 22 of its DHC-515 water bombers to six EU countries, with more deals expected soon.
Collaborate on Arctic surveillance. Canada and several north European countriesareconcerned about environmental impacts, in addition to rising defence and logistics needs in the fast-warming region. Canada’s RADARSAT radar satellites that see through cloud and darkness and are part of European Space Agency’s (ESA) Earth-observation program, could be expanded.
New EU space rules present a new frontier for Canadian firms. Since its induction in 1979, Canada remains the only non-European cooperating state of the ESA. Ottawa’s €407-million pledge to ESA in November 2025 was its largest ever and includes ESA’s new program of Earth-observation satellites for security and defence.
The proposed EU Space Act could also be a boon for Canadian operators, as the EU would waive some of its regulatory and fee requirements for jurisdictions it deems comparable with its framework.
Canada could be a launching pad for EU space crafts. Europe has committed €902 million through the ESA’s European Launcher Challenge to buy launches from five new European rocket companies, with flights due by 2030. While Canada cannot currently launch its satellites from its home base, that could change in a few years as Ottawa is spending $200 million to help develop a launch pad at Spaceport Nova Scotia, near Canso, to be ready by the end of 2026. The Spaceport developer has already secured a contract to launch rockets for Germany’s Isar Aerospace.
Technology, AI & Data: Plugging into EU
As the world continues to ramp up AI spending, there’s opportunity for Canada to work more closely with the EU—but that will require some regulatory groundwork first.
Despite Canada’s privileged access to EU, bilateral tech trade remains small. Last year the EU imported computers, telecom equipment and electronic components valued at €724 million from Canada, and exported €1.6 billion here.
Since 2001, the EU has recognized Canada’s private-sector privacy law as adequate, so companies can send personal data from the EU to Canadian businesses without the enhanced legal safeguards other countries require. Building on that fast-tracked path, the two sides launched a Digital Partnership in 2023, and opened talks on a digital trade agreement in March, laying the ground for more tech-related trade.
The growth potential
Associate membership status could help open door to the EU for Canadian companies.
Europe is spending heavily on AI and cloud. The EU’s InvestAI initiative, launched in February 2025, aims to mobilize €200 billion for AI, including €20 billion for seven large AI computing centres known as gigafactories, and the EU wants to triple its data-centre capacity in the next five to seven years. Europe’s cloud market was worth €61 billion in 2024, but European providers held only about 15% of it. Canadian companies are making inroads. Toronto-based AI company Cohere plans to combine with Germany’s Aleph Alpha, which works with German public bodies, to form a Canadian-led company with headquarters in Toronto and Berlin. Canada and Germany also launched a Sovereign Technology Alliance in February to reduce reliance on foreign technology. In addition, Ericsson, the Swedish telecom-equipment maker, is spending more than $630 million on research in Ottawa and Montreal under a 2024 agreement with the federal government. Mistral AI, the Paris AI model developer, is opening an office in Montreal, plans to open another in Toronto and signed an agreement with the Quebec government in June on using AI in public services.
Few Canadian companies have the capacity to scale up in Europe. CGI earned $6.2 billion from their European operations in their latest financial year. Brookfield, the Toronto asset manager, has committed €20 billion to AI infrastructure in France and up to US$10 billion to an AI data centre in Sweden since 2025. But most companies don’t have the scale: about 99% of Canada’s 48,400 tech firms are small or medium-sized, 85% employ fewer than 10 people and only about a quarter export. The U.S. takes two-thirds of Canada’s tech hardware exports, with the EU and U.K. combined accounting for about 11%.
Europe is moving to keep government cloud and AI work with European providers. The EU’s Cloud and AI Development Act, proposed in June 2026, would generally limit public bodies to cloud providers established in the EU. For sensitive work, providers would also have to be owned and controlled in the EU, with exception only for countries the Commission approves of, and the most sensitive work would carry no exception. Canada could be one of those chosen few jurisdictions.
However, Canada’s consumer data privacy law needs an update. Bill C-36, which would update Canada’s privacy law, has not yet passed. The last update was back in 2000—way before the proliferation of social media—and there are concerns that the EU’s approval of Canada’s privacy laws could be withdrawn.For now, personal data flows freely from the EU to Canadian businesses because the EU judges that law to protect data adequately in line with its own regulations. However, that judgement is reviewed every four years (the next is due in 2028).
Secure associated country status under the new cloud rules. Under the Cloud and AI Development Act, Canada could gain this status, allowing Canadian-controlled providers to bid for critical EU cloud and AI contracts on an equal footing with EUoperators. The catch is that infrastructure, staff, and customer data must stay in the EU, so the biggest winners would be Canadian firms already operating in Europe. Ottawa would have to give something back: keep its privacy legislation up to EU standards and open Canadian public contracts, including Ottawa’s own sovereign cloud purchases, to EU providers on equal terms.
Agree to accept each other’s product testing. The Canada-EU Digital Partnership Council, which first met in Montreal in December 2025, is exploring mutual recognition of testing for AI-enabled and connected products. A deal would let Canadian labs certify products for the EU market, so Canadian makers can test once for both markets.
Contributors:
Jordan Brennan, Managing Director
Shaz Merwat, Energy Policy Lead
Wilson Fink, Agriculture Policy Lead
Thomas Ashcroft, Global Policy Issues Lead
Services trade flows are for 2024, not 2025, and include the U.K., Norway, and Switzerland, none of which are EU members.
Average of 2022-2024.
Innovation, Science, and Economic Development Canada, ‘The Government of Canada announces investment in Prevost (Volvo Group Canada Inc.) in Sainte-Claire to support Canadian bus manufacturing and clean transportation’, October 16, 2026
Transport Canada, Electric Vehicle Affordability Program: Overview
Statistics Canada, Canadian international merchandise trade data, accessed through Innovation, Science and Economic Development Canada, Trade Data Online, “Canadian domestic exports to the European Union (EU-27), and imports, 2021 to 2025, using NAICS codes 11 (Agriculture, Forestry, Fishing, Hunting), 311 (Food Manufacturing), 312 (Beverage and Tobacco), and HS Codes 31 (Fertilizers), and Select agriculture-related codes from Equipment Manufacturing and machinery) current Canadian dollars, accessed October 27, 2026.
Statistics Canada, Canadian international merchandise trade data, accessed through Innovation, Science and Economic Development Canada, Trade Data Online, “Canadian domestic exports to the European Union (EU-27), and imports, 2025, using HS Codes 201, 202, 203, 20630, 20641, and 20649.
United Nations Statistics Division, UN Comtrade Database, HS Commodity Codes 0201 and 0202, Canada Export of goods to EU-27, 2025 United Nations Statistics Division, UN Comtrade Database, HS Commodity Codes 0201 and 0202, Canada Export of goods to EU-27, 2025
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates. This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/our-impact/sustainability-reporting/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.