

 EN


For the week of October 26th
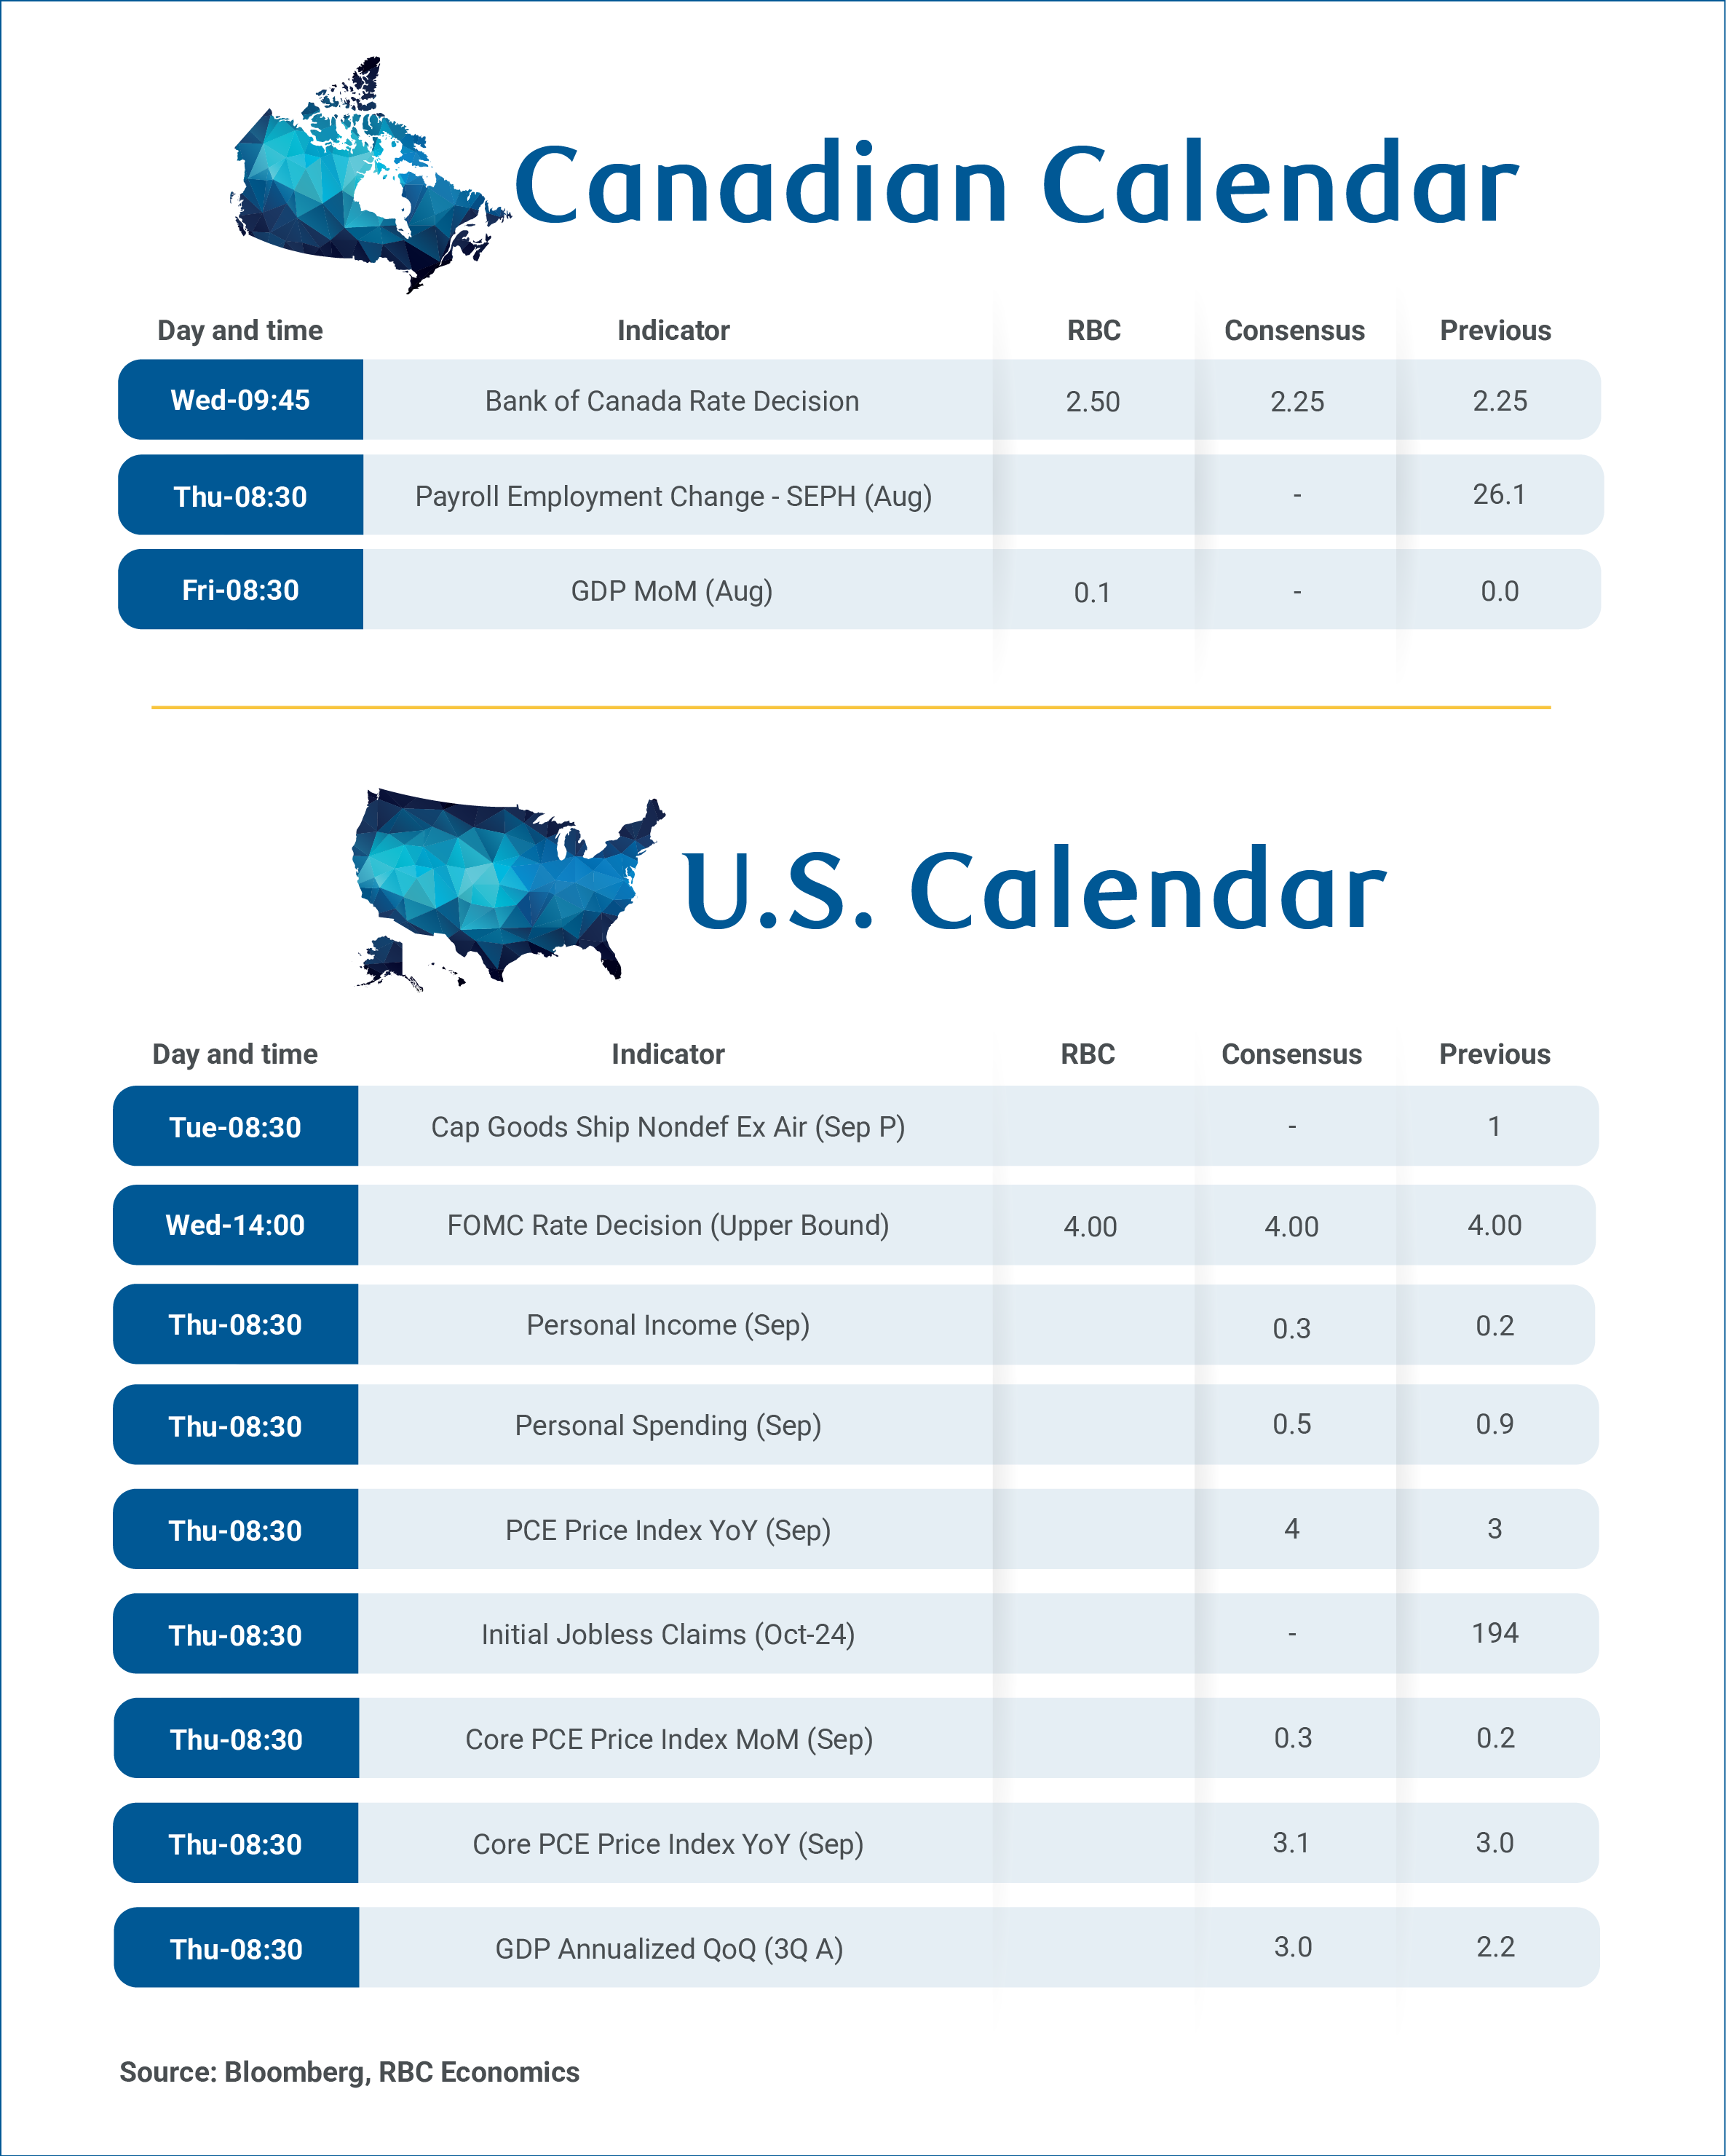
We are now pencilling in the Bank of Canada’s first interest rate hike of 25 basis points since March 2022 on Wednesday as it faces a pivotal decision amid evolving economic conditions.
But, we have very low conviction on the idea of a rate hike this soon, and it’s almost equally probable the central bank uses this meeting to tee-up a coming hike in December or January.
Importantly, our expectation of a move higher from the BoC on Wednesday is not because we believe there is an urgency to hike interest rates.
Instead, it’s driven by our interpretation of policymakers’ communication since Sept. 2nd, which has consistently emphasized a laser focus on safeguarding against future inflation risks from higher energy prices, and uncomfortable waiting for another inflation rise to materialize.
The case for patience is strong
In our view, the case for the central bank continuing to wait on the sidelines remains compelling.
The Canadian economy is improving, but still not strong. There is sufficient slack, in our view, that will slow inflation passthrough . Job growth has disappointed, and there is no evidence that elevated energy prices are bleeding into broader core inflation measures. Housing markets remain weak, and August gross domestic product data released next Friday should confirm that growth slowed in Q3 after surging in Q2.
Trade disruptions following the breakdown of Canada-United States’ trade talks, and imposition of new tariffs late August add another layer of complexity even as the Bank has downplayed this factor of late.
Meanwhile, the term structure of government bond yields has already done some of the central bank’s work. Five-year government bond yields have risen more than 40 basis points over the last three months, reflecting market expectations of rate increases.
And much of the borrowing by Canadian households and businesses are done at fixed rates, and interest rates for new loans have already been rising.
But the BoC’s risk calculus appears to have changed
Yet, communication ranging from the Sept. 2nd rate decision to Governor Tiff Macklem’s comments recently on the sidelines of the International Monetary Fund meetings repeatedly conveyed—whether intentionally or not—that the BoC no longer believes it can wait passively for inflation to materialize before acting.
This shift seems to reflect a recalibration of the central bank’s risk calculus. In particular, it suggests less of a focus on the here and now, but instead attention most on what lies ahead. To be fair, that forward outlook is, indeed, improving. The economy is expected to gradually improve, business optimism remains resilient despite recent trade disruptions with the U.S., and the central bank’s overnight rate—currently at the lower end of the neutral range—leaves room for measured increases without triggering economic distress.
In part, our growth forecasts for 2027 was a factor in our prior base case projection of rate hikes beginning in Q1.
Ghost of post-pandemic inflation surge
What’s also likely weighing on the central bank are the cautionary lessons of the post-pandemic inflation surge of 2022-23 that demonstrated how supply-side shocks and persistent cost pressures can overwhelm an economy surprisingly quickly.
There may indeed be value in some insurance against a repeat of that episode. While conditions today differ in many respects to 2022, West Texas Intermediate oil prices have averaged $95 a barrel since the last rate decision—54% higher than the same period last year. As long as they stay there, cost pressures will continue building throughout the economy as Canadians continue to absorb what was, for many of them, the largest inflation shock of their lives just a few years earlier.
The BoC will be using a new forecasting tool (PRIMA) in October, designed in large to better account for supply side shocks to inflation.
A hike now doesn’t change our outlook for Canada
While we don’t see an immediate need for the BoC to hike now, at the same time, a 25-basis-point increase in the overnight rate on Wednesday won’t materially change our medium-term economic outlook compared to a December or January hike.
Although it slightly increases the odds of a growth slowdown in Q4, particularly in heavily interest rate sensitive sectors like housing, our base case forecast already assumed 100 basis points of increases in 2027, contingent on a gradually improving economy.
Shifting the timing of the first of those hikes does not significantly impact the growth outlook. So, rather than the rate hike itself, we will be monitoring for any communication that helps us understand the Bank of Canada’s expected path of interest rates ahead – how many more hikes and when.
Ultimately, the signal of a rate hike on October 28thhas a larger meaning we shouldn’t ignore: Central banks do not have the same patience for inflation they might have had in the past, and are willing to act preemptively to guard against it.
-
We expect Canadian GDP edged up 0.1% in August, slightly below the 0.2% advance estimate from Statistics Canada a month ago, but above the flat reading in July. That would leave the monthly data tracking broadly in line with our forecast for a 1.8% Q3 GDP increase following the 3.3% surge in Q2. Early indicators for August GDP point to a pullback in oil extraction. Wholesale trade volumes fell 1.4% and manufacturing production was likely little changed. But consumer indicators have remained firmer — advance estimates pointed to an increase in August retail sales — and construction spending has been rising.
-
The Federal Reserve is expected to hold the fed funds target range unchanged on Wednesday after hiking for the first time since 2023 in September. FOMC members continue to signal that more hikes will follow, but comments after the last decision suggest a gradual approach. We expect two 25-basis-point rate hikes ahead before the end of Q1 2027.
About the authors:
Frances Donald is the Chief Economist at RBC and oversees a team of leading professionals, who deliver economic analyses and insights to inform RBC clients around the globe. Frances is a key expert on economic issues and is highly sought after by clients, government leaders, policy makers, and media in the U.S. and Canada.
Nathan Janzen is an Assistant Chief Economist, leading the macroeconomic analysis group. His focus is on analysis and forecasting macroeconomic developments in Canada and the United States.
Explore the latest from RBC Economics:
Q3-26 Canadian Business Outlook Survey: More firms plan cost pass-through
Canadian inflation ticked higher in September
Canada’s housing market retreats as rates hikes and trade war escalation collide
Share these insights with your network:
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

