

 EN


Next week brings the September inflation picture — and we do not expect CPI will be reassuring. Headline inflation remains an oil price story – we forecast headline CPI at +0.6% m/m, pushing the year-over-year pace up to 3.7%.
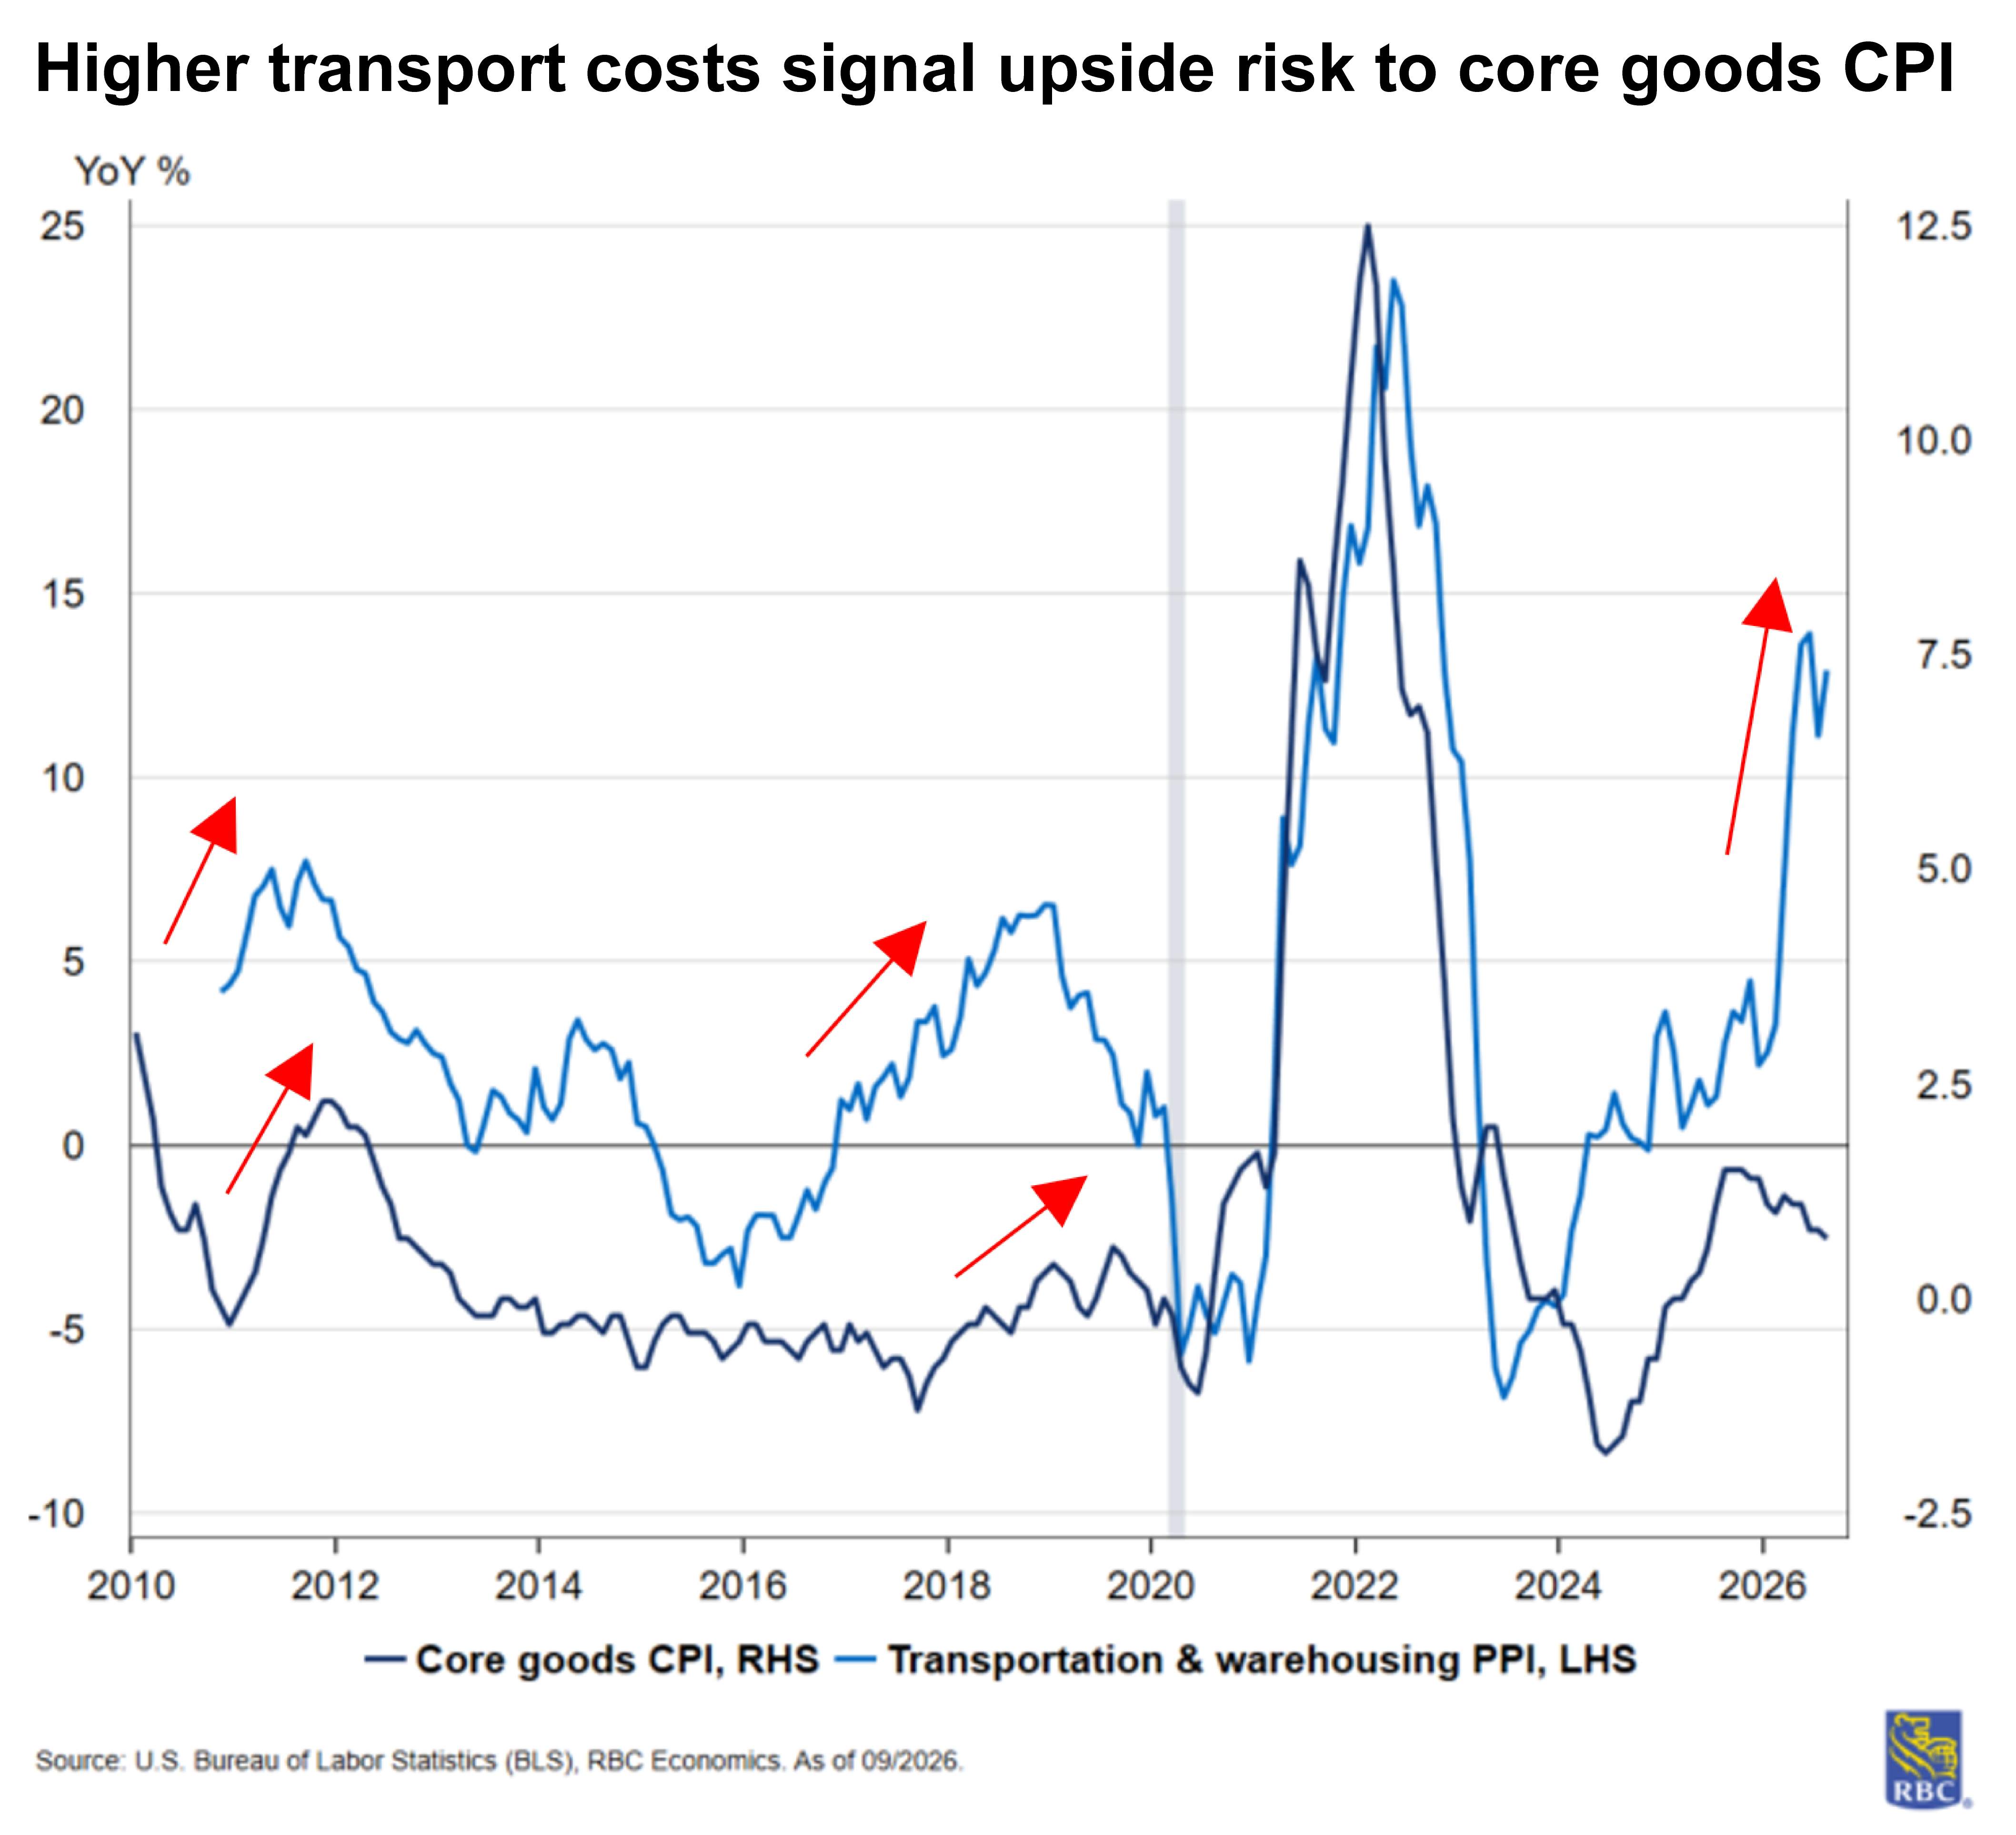
More concerning will be core CPI. We expect a more modest +0.2% m/m print (rounding-down), but the year-over-year pace is expected to nudge higher to 2.5%. The risk remains that we see limited prospect of a material deceleration in core inflation, and September’s CPI report won’t fully capture the upside risks ahead. Supercore inflation has consistently printed at or above 3% since March and has begun to reaccelerate. Core goods pressures continue to build – motor vehicle parts and equipment prices have risen in response to tariffs, which is now translating to higher prices for new and used cars. Problematically, sizeable risk sits in the pipeline from both tariffs and geopolitical disruption — and the core goods backdrop is where we expect to see the most immediate spillover from higher diesel prices. Freight services PPIs have been ugly — we will get a better read with September PPI on Thursday.
We expect to see another sizable jump in PPI of +0.9% m/m and core PPI at +0.4% m/m. Within PPI, trade services — reflective of margins between wholesaler and retailer acquisition costs and selling prices — has trended negative for two consecutive months, signaling potential margin compression. A third negative print would be concerning, since this would signify that the volatile trade services print is settling in “margin compression” territory.
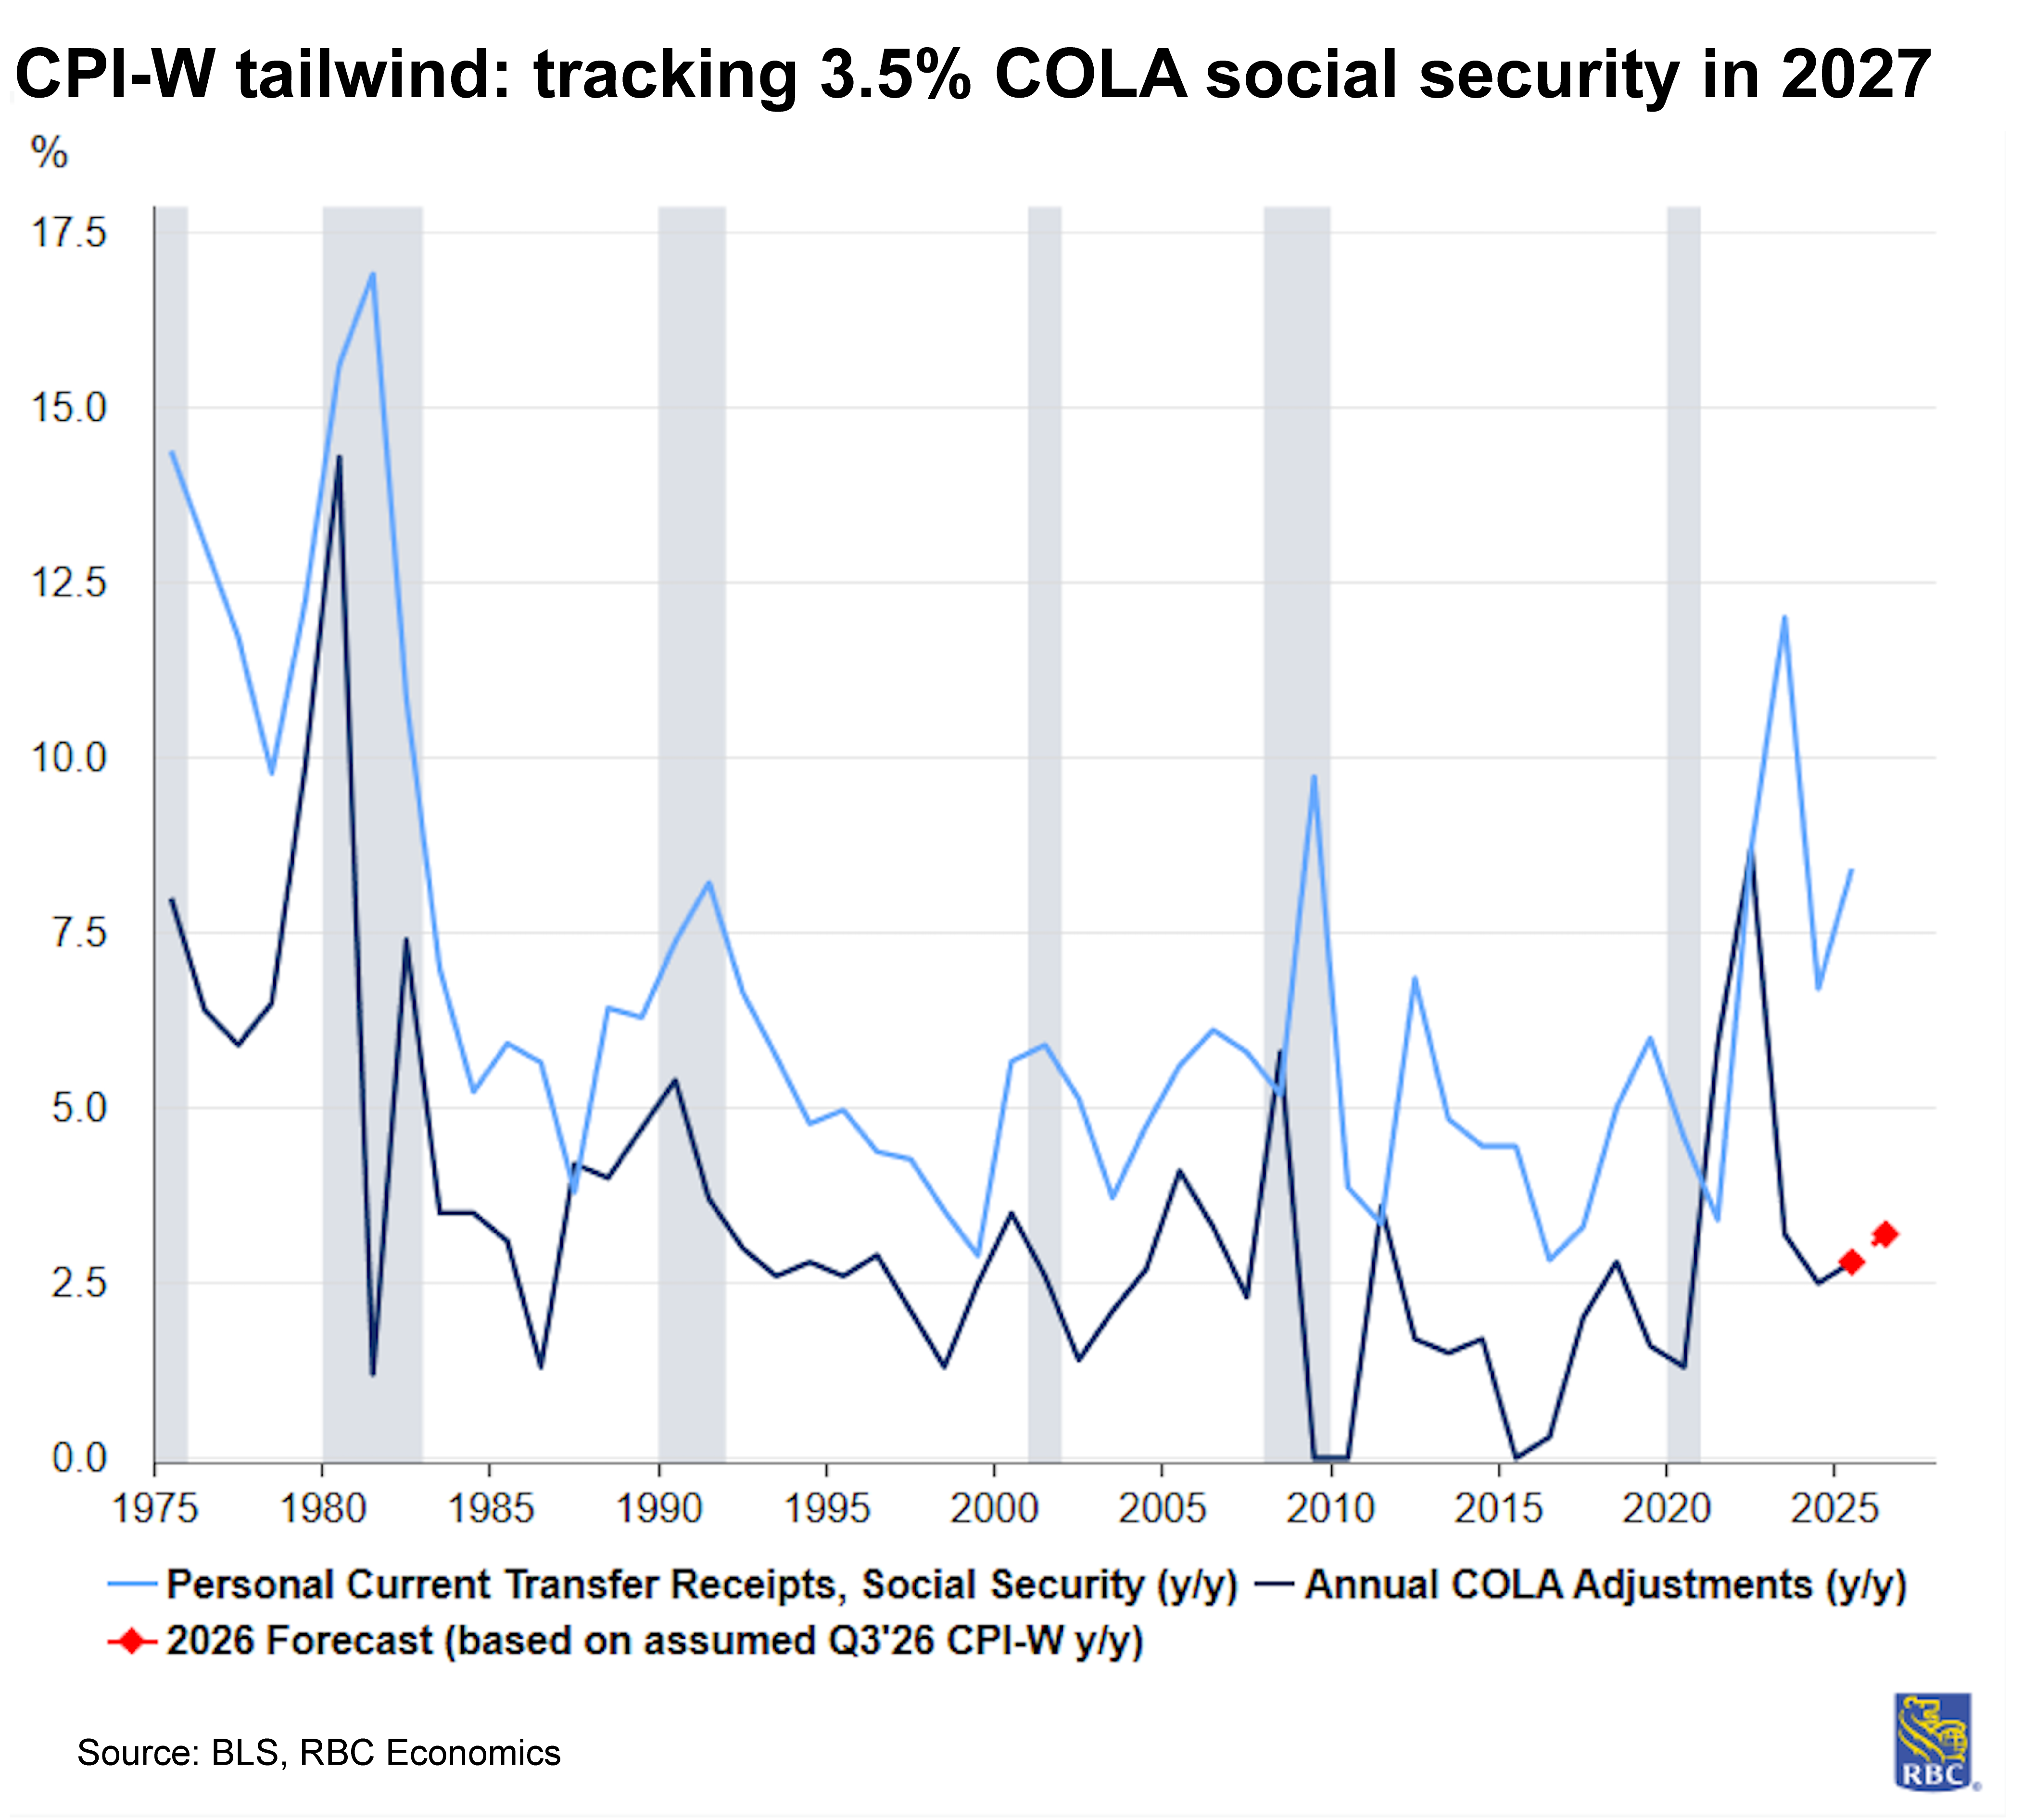
If August personal spending is any indication, real consumer demand remains exceptionally strong even in the face of inflationary pressures. Year-over-year growth in average weekly earnings has remained stable, but of growing importance is non-labor sources — transfers, rent, and interest and dividend income — supported by strong equity valuations and a higher rate environment. Come January, retirees are set to benefit from a sizeable cost-of-living adjustment (COLA) to Social Security income just as base effects begin to ease year-over-year headline prints. September’s CPI-W will matter here, since Q3 price growth is the input into the COLA calculation. The bottom line: there is minimal prospect for any help from core services from a demand perspective.
We are also slated to get September advance retail sales, which we expect will look strong on the surface at +0.8% m/m. But we expect the control group will point to moderate growth after a strong August reading. On a month-over-month basis, nonstore spending (i.e., online retailers) has been volatile in the summer due to seasonal quirks surrounding the timing of Prime Day. We will be closely watching this category for signs of consumer fatigue, specifically among middle-income consumers who are increasingly stretched as interest payment burdens rise, savings draw down, and reliance on credit deepens. Still, high income consumers will continue to drive the bulk of consumer spending.
About the authors:
Mike Reid is Head of US Economics at RBC. He is responsible for generating RBC’s US economic outlook, providing commentary on macro indicators, and producing written analysis around the economic backdrop.
Carrie Freestone is a Senior US Economist at RBC. She is responsible for generating RBC’s US economic forecasts across GDP, employment, and inflation, and providing macro commentary through publications, presentations, and the media.
Imri Haggin is an US Economist at RBC, where he focuses on thematic research. His prior work has centered on consumer credit dynamics and treasury modeling, with an emphasis on leveraging data to understand behavior.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

