

 EN


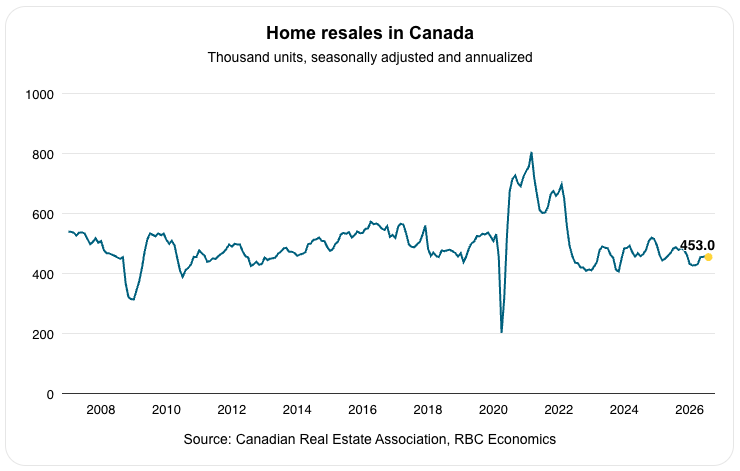
Canada’s housing market hit pause in August after five consecutive months of gains with resales declining 0.7% month-over-month seasonally adjusted—retreating to levels in May. The pullback coincided with an escalation in trade tensions, which appears to have rattled buyer confidence while prompting more sellers to list.
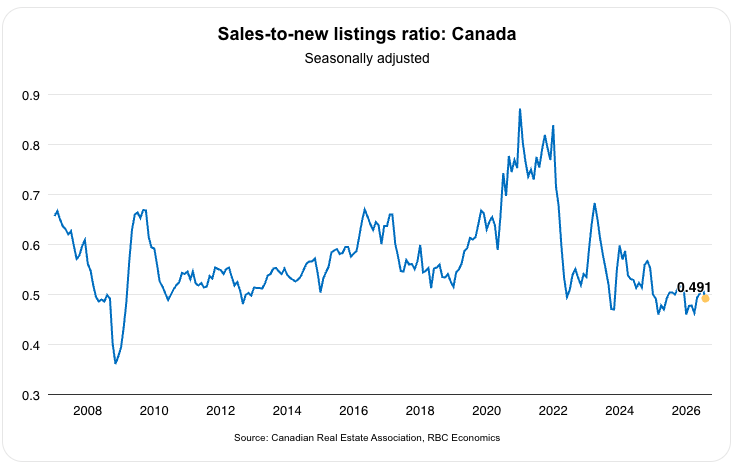
New listings grew 3.3% m/m, pushing the sales-to-new-listings ratio lower to 49%—technically still balanced territory which should cushion prices against sharper declines.
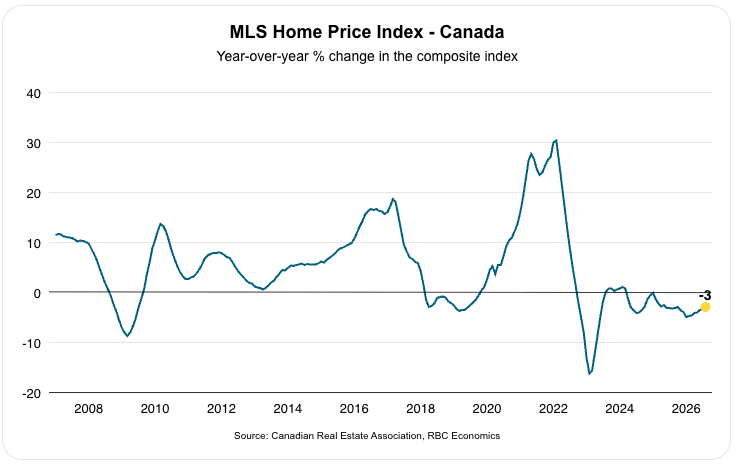
CREA’s composite price measure was little changed from July, and year-over-year price declines slowed to -3%, continuing the deceleration defining the market since January.
A temporary detour, not a derailment
We’re reading the August resale slowdown as more of a pause than inflection point. Trade tensions escalated last month, making economic uncertainty tangible again after months of adaptation.
As households navigate tariff headwinds and sentiment rebuilds, we expect stabilization to take hold over the back half of 2026 and into 2027—though the regional picture will be decidedly mixed.
Early signs of regional rebalancing
Vancouver—one of the nation’s softest market—saw resales edge up in August, crossing the 2,000 mark for the first time in nine months. Prices in Vancouver continued to edge lower, but the pace of declines has been decelerating.
That broadly mirrors signs of stabilization in Canada’s other hardest hit housing market, Toronto, where home prices edged slightly lower in August from July, following small increases in June and July after declining for most of the prior year.
Ottawa, likewise, saw improvement with annual growth in the MLS Home Price Index cresting into positive territory for the first time in 2026. This marks an important milestone, but we could see more volatility before annual price changes firmly establish positive ground.
Prices remained underwater from a year ago across most of Ontario and British Columbia as well. Atlantic Canada, Quebec, and parts of the Prairies in contrast saw prices stay firmly positive—though appreciation continues to slow from earlier in the year.
The balanced sales-to-new-listings ratio seen at the national level now characterizes most regions, though pockets of seller advantage persist in Saskatoon, Regina, Winnipeg, Sherbrooke, Saint John and Halifax—albeit with weakening intensity.
Improving market mechanics still intact
Despite the August pause, the mechanics underpinning the market’s modest tightening earlier in the summer are likely to re-emerge. New listings are still below a year ago, which has helped stabilize inventory and rebalance supply and demand.
That said, resales still have a distance to cover before returning to the 10-year average. This fragility was evident in August, and we expect it to persist in the face of trade tensions and economic headwinds. While conditions are expected to improve gradually, any pickup is poised to be incremental rather than dramatic.
About the author:
Rachel Battaglia is an economist at RBC, providing forecasts for the Canadian provincial economies and analyzing key trends in housing and consumer spending.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

