

 EN


The Bottom Line:
Canadian inflation held at 3% year-over-year in August, unchanged from July. Energy price growth remained elevated but was little changed, with gasoline prices edging lower from July while remaining 23% above year-ago levels. Food inflation continued to put pressure on household budgets but ticked lower to 2.8% year-over-year in August, the lowest since late 2024.
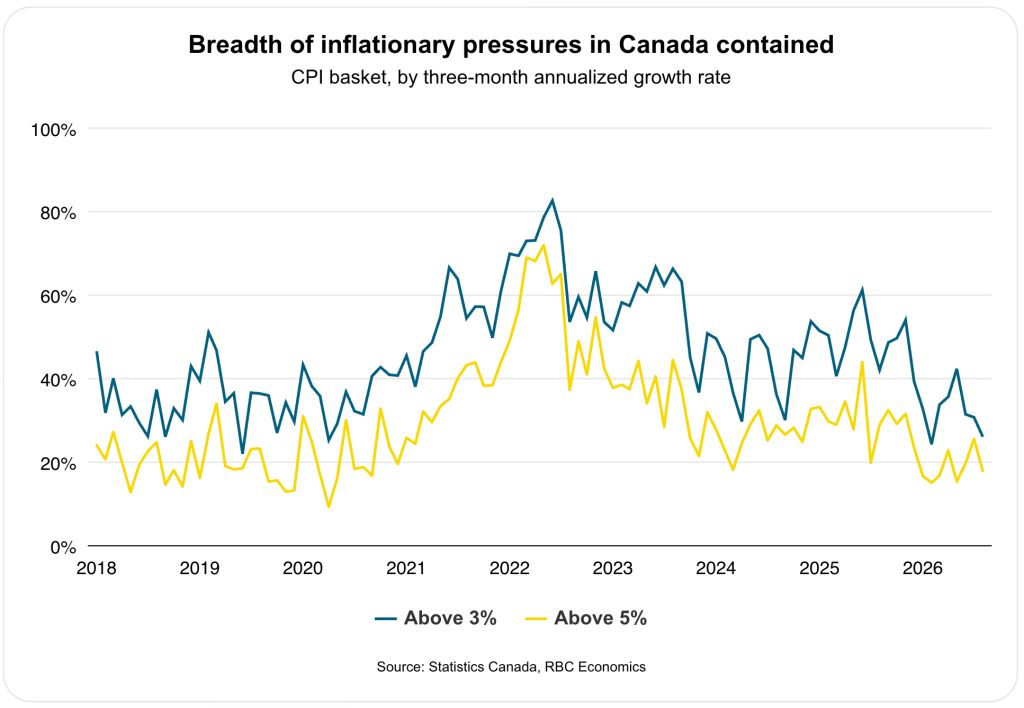
Underlying inflation pressures remained comparatively contained. CPI excluding food and energy edged up to 2.1% year-over-year, while the Bank of Canada’s preferred CPI-trim and CPI-median measures remained close to the 2% target. Measures of inflation breadth were also contained, suggesting that unusually strong price growth remained concentrated in a relatively narrow group of categories.
There continued to be limited evidence that elevated energy costs were generating significant second-round inflation. Price growth remained high for energy-intensive categories such as air travel but had not spread materially across the broader consumer basket. The risk of greater pass-through will rise the longer oil prices remain elevated, making the breadth and persistence of underlying price pressures more important than month-to-month movements in headline inflation.
The August report was broadly consistent with our base case that the Bank of Canada will hold interest rates through the remainder of 2026 before gradually raising rates in 2027 as the economy strengthens. Risks around that forecast are increasingly tilted toward an earlier hike, particularly if elevated energy prices persist while the economy and labour market continue to recover. But so far, the evidence has been limited, and we will continue to monitor energy pass-through effects closely.
The details:
-
Headline CPI rose 0.2% m/m on a seasonally adjusted basis in August, leaving the annual inflation rate unchanged at 3%.
-
Energy prices were 15.4% higher than a year ago, compared with 16.6% growth in July.
-
Gasoline prices fell 0.9% from July but remained 23% above year-ago levels.
-
Food price inflation was 2.8% year-over-year, compared with 3% in July. Grocery prices increased 2.8%, down from the 3.1% in July, and this marked the first time in over two years, grocery price growth lagged overall inflation.
-
CPI excluding food and energy came in at 2.1% year-over-year, continuing to point to comparatively contained price pressures outside the most volatile categories.
-
The Bank of Canada’s preferred core measures remained close to target. CPI-trim was 1.9% year-over-year, while CPI-median was 2% year-over-year, leaving their average unchanged from last month.
-
The trim services excluding shelter measure sometimes referred to as “supercore” was 2.6% year-over-year, compared with 2.5% in July. And the three-month annualized rolling average was down slightly from 2.8% in July to 2.7%.
-
Measures of inflation breadth remained contained. The share of CPI basket components growing faster than 3% over the past three months slipped to 25.9% from 30.6% in July, while the share grew faster than 5% down to 17.7% from 25.4%.
-
Airfares were 15% higher than a year ago, compared with a 12% increase in July.
-
Clothing prices declined 1.1% year-over-year in August after rising 0.9% in July, driven by lower men’s (-2.3%) and children’s (-1.9%) clothing prices, partially offset by unchanged women’s clothing.
About the author:
Abbey Xu is an economist at RBC. She is a member of the macroeconomic analysis group, focusing on macroeconomic forecasting models and providing timely analysis and updates on economic trends.
This article is intended as general information only and is not to be relied upon as constituting legal, financial or other professional advice. The reader is solely liable for any use of the information contained in this document and Royal Bank of Canada (“RBC”) nor any of its affiliates nor any of their respective directors, officers, employees or agents shall be held responsible for any direct or indirect damages arising from the use of this document by the reader. A professional advisor should be consulted regarding your specific situation. Information presented is believed to be factual and up-to-date but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the authors as of the date of publication and are subject to change. No endorsement of any third parties or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
This document may contain forward-looking statements within the meaning of certain securities laws, which are subject to RBC’s caution regarding forward-looking statements. ESG (including climate) metrics, data and other information contained on this website are or may be based on assumptions, estimates and judgements. For cautionary statements relating to the information on this website, refer to the “Caution regarding forward-looking statements” and the “Important notice regarding this document” sections in our latest climate report or sustainability report, available at: https://www.rbc.com/community-social-impact/reporting-performance/index.html. Except as required by law, none of RBC nor any of its affiliates undertake to update any information in this document.

